

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
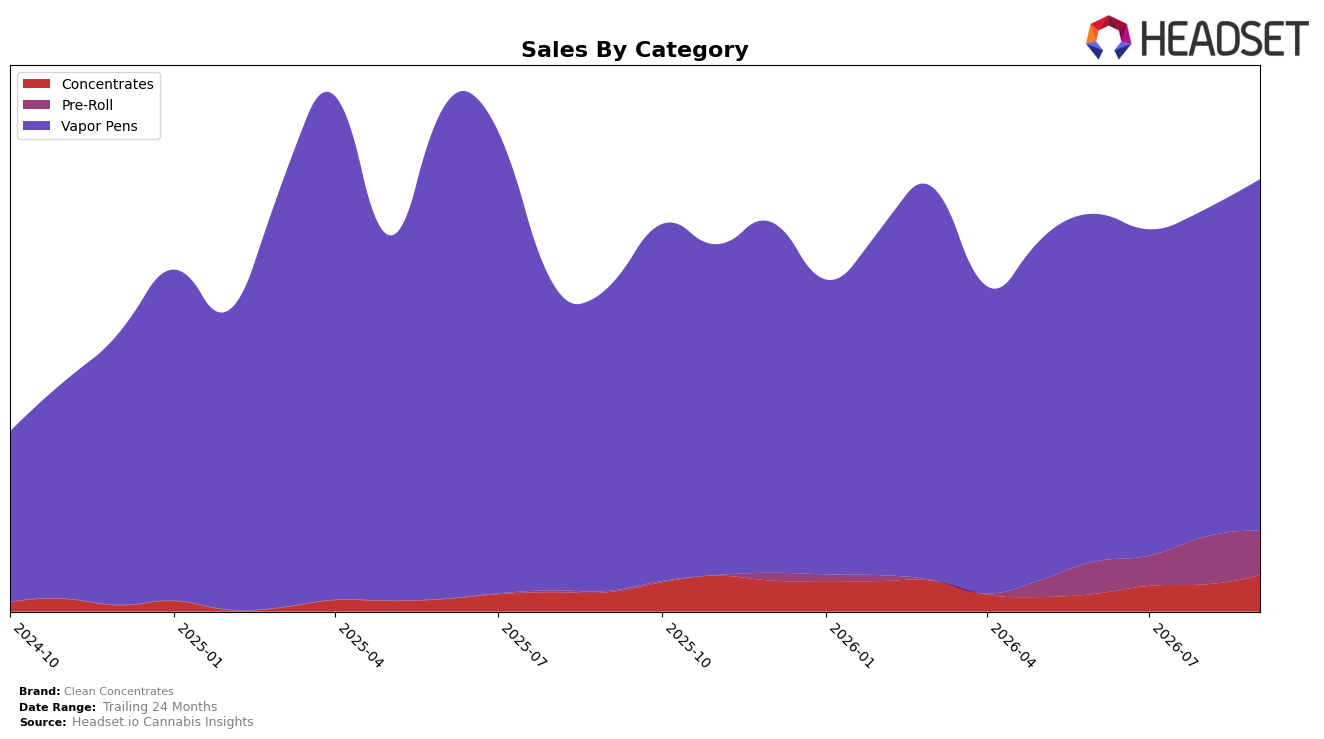
Clean Concentrates concentrated 81.50% of September 2026 sales in Vapor Pens with 15.88% YoY growth and 7.50% MoM, while Pre-Roll reached a 10.16% share on a 5,283.71% YoY surge but slipped 6.71% MoM; Concentrates held 8.33% share with 89.47% YoY and 34.12% MoM. Despite total brand sales up 33.48% YoY and an average price down 30.78% YoY to $14.78, the category tilt remains Vapor Pens-led, and the mix shift—Pre-Roll’s explosive YoY coupled with MoM pullback versus Concentrates’ double-digit MoM—implies demand is broadening beyond a single category while pricing resets.
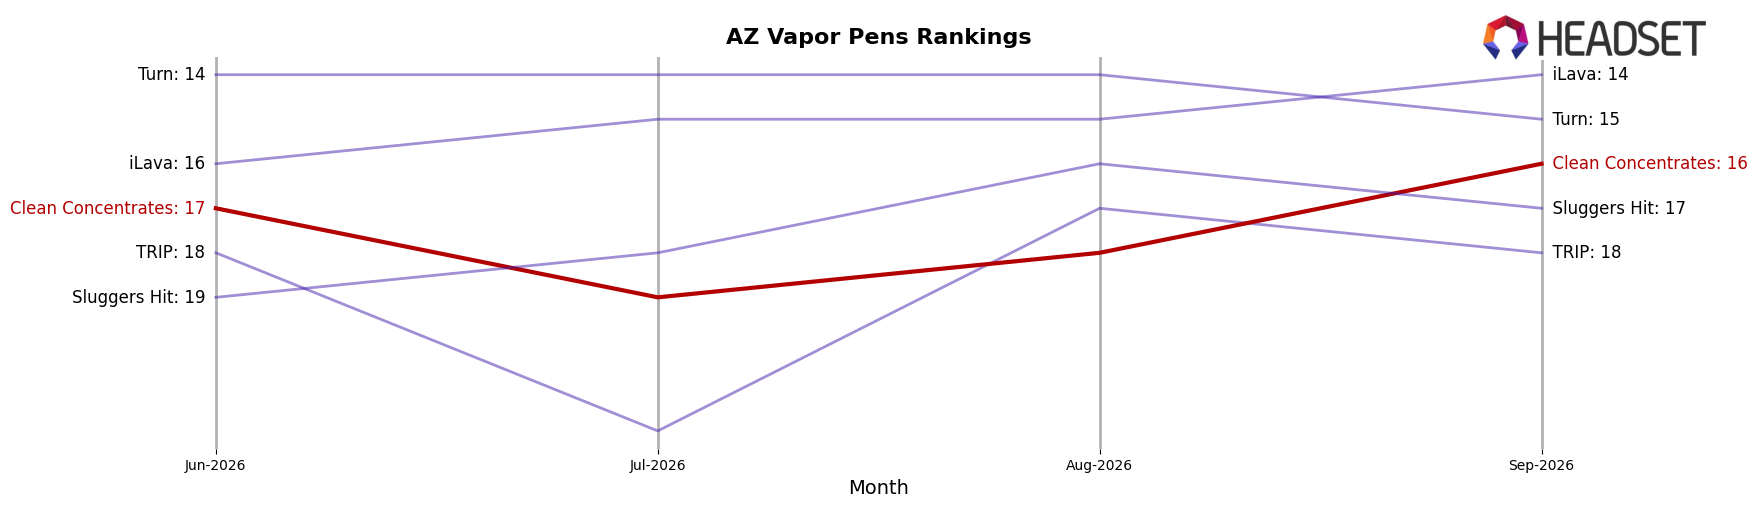
With Vapor Pens ranked 16 in Arizona and holding an 81.50% share of brand sales, incremental gains of 7.50% MoM in that category need to translate into rank movement, while the 34.12% MoM in Concentrates and 10.16% share in Pre-Roll indicate emerging lanes to de-risk reliance on one pillar. The pattern—brand sales up 33.48% YoY alongside a 30.78% YoY price drop—signals a volume-led posture where expanding Concentrates and stabilizing Pre-Roll MoM can improve mix resilience without abandoning the Vapor Pens anchor.
Competitive Landscape
Clean Concentrates sits at rank 16 in September 2026, improving 2 positions year over year from rank 18 while slipping 1 spot since June 2026 when it was rank 17, and it remains 4 places below its peak rank 12 from July 2025; by contrast, Abstrakt climbed from rank 5 to rank 2 alongside a 133.9% year-over-year sales change, while Dime Industries fell from rank 2 to rank 4 despite a 10.8% year-over-year sales increase. The flat top-tier positions—Mfused holding rank 1 year over year and Select steady at rank 3 with an 18.4% lift—signal that mid-pack gains of 1–2 ranks, like Clean Concentrates’ 2-rank YoY rise and 1-rank quarter-over-quarter dip, are unlikely to convert into top-10 penetration without a step-change, implying the current trajectory points to stabilization in the mid-teens rather than breakout advance.
Notable Products
The sharpest move in September 2026 was Purple Urkle Infused Pre-Roll (1g) dropping 28.1% MoM to rank 6, while Blueberry Cough Distillate Compact Disposable (1g) climbed 21.3% to rank 3. Blueberry Cough Distillate Compact Disposable (2g) rose 12.4% at rank 2 and Strawberry Cough Distillate Compact Disposable (2g) advanced 22.2% at rank 4, putting three Vapor Pens in the top five. With Vapor Pens holding ranks 2–5 and Pre-Rolls split between rank 1 and rank 6, the mix implies Clean Concentrates is consolidating around flavored disposables while trimming exposure to lower-velocity infused pre-rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

