

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Savvy is stocked at 683 licensed dispensaries across Illinois, New Jersey, and 9 other states, 155 of them in Illinois, with the deepest coverage in Chicago, Springfield, Normal, Quincy, and Schaumburg. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
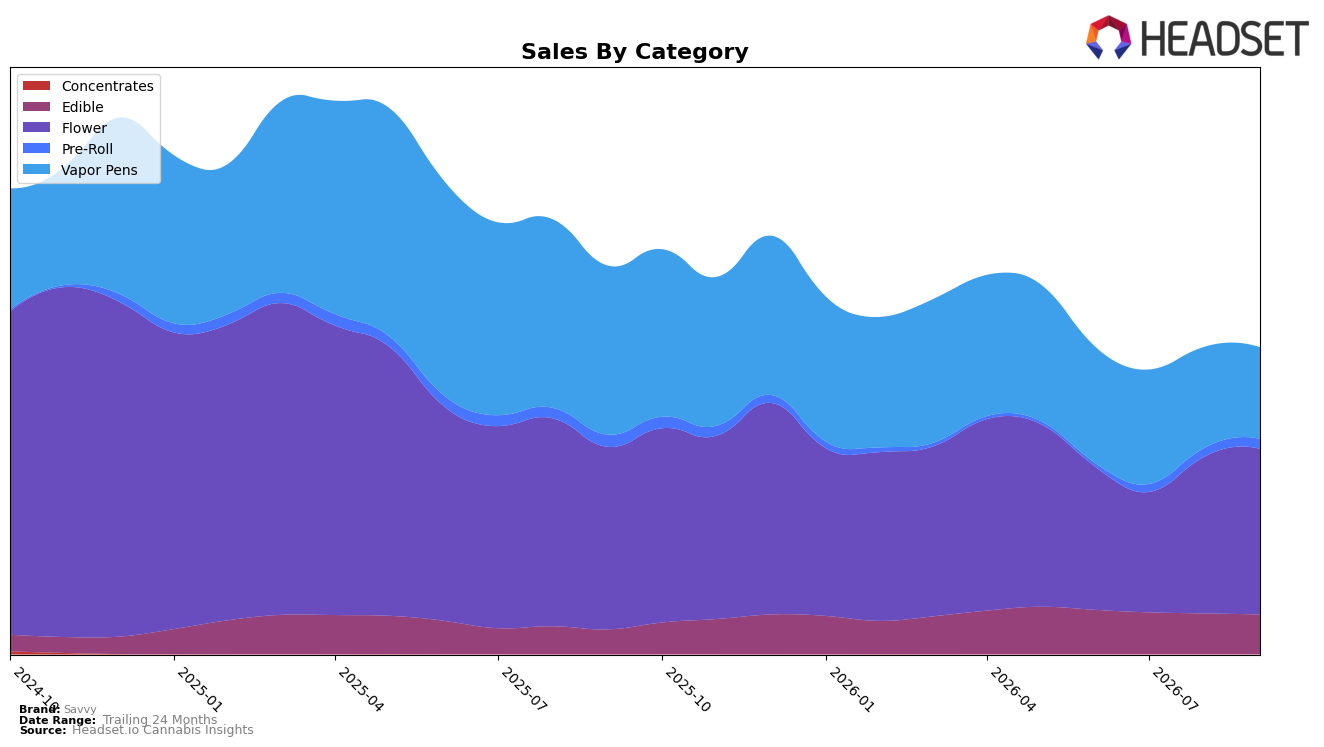
September 2026 category mix concentrates in Flower at 54.07% share with a 5.56% MoM lift despite a -9.28% YoY decline, while Vapor Pens at 29.86% share fell -9.40% MoM and -45.87% YoY; Edible expanded YoY by 61.03% but slipped -2.54% MoM at 12.89% share, and Pre-Roll gained 15.61% MoM after a -18.30% YoY dip at 3.18% share. Combined with a -21.05% brand-level YoY sales change and an -18.10% YoY average price shift to $27.95, the mix indicates the portfolio is pivoting toward Flower and Edible volume while Vapor Pens pressure the aggregate, implying a tactical shift toward categories with steadier MoM momentum and less YoY drag.
Ranking at number 5 in Vapor Pens in Illinois alongside a -45.87% YoY contraction and -9.40% MoM drop suggests share defense in that category requires reallocation, while Flower’s 5.56% MoM growth and Edible’s 61.03% YoY rise indicate clearer paths to regain trajectory. With a -31.76% 24‑month sales change and Pre-Roll’s 15.61% MoM uptick from a 3.18% base, the pattern implies prioritizing Flower and scaling Edible to offset Vapor Pens volatility, using targeted pricing after an -18.10% YoY average price move to stabilize mix and protect rank-sensitive segments.
Competitive Landscape
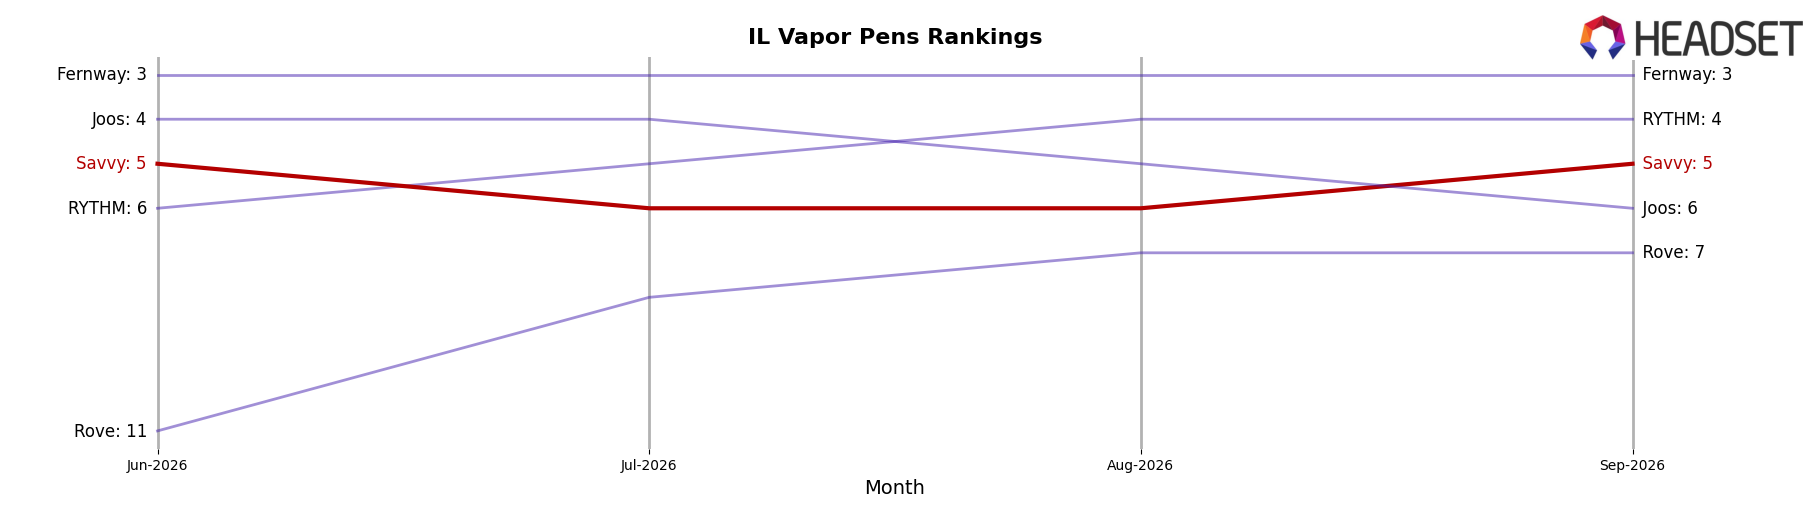
Savvy sits at rank #5 in Illinois Vapor Pens in September 2026, a drop of 2 positions year over year from #3, and unchanged from #5 in June 2026, while its peak of #3 in March 2026 marks a 2-rank slide since that month; in contrast, &Shine moved up from #2 to #1 with 38.35% year-over-year sales growth and Fernway jumped from #13 to #3 with 308.84% growth, outpacing Savvy’s rank trajectory as RYTHM climbed from #5 to #4 with 44.16% growth. The combination of a 2-position year-over-year decline to #5 and three months stalled at #5 implies Savvy is ceding momentum to faster-advancing competitors and must adjust to avoid further share erosion.
Notable Products
Guap - Jungle Juice Macro Dosed Gummy (50mg) posted the steepest decline in September 2026 at -14.0% MoM while sitting at rank 6, and Guap - CBD/THC 1:1 Peachy Punch RSO Gummy (100mg CBD, 100mg THC) fell -11.9% MoM at rank 5, indicating demand softness in value and 1:1 formats. In contrast, Guap - CBN/THC 1:2 Melon Crash Macro Dose RSO Gummy (50mg CBN, 100mg THC) rose 11.7% MoM to hold rank 3, while the top two SKUs each declined between -1.0% and -5.0% at ranks 1 and 2, concentrating share at the top even as momentum rotates toward functional CBN blends. Eight of the top ten are Edible SKUs, with Flower entrants debuting at ranks 9 and 10 without MoM baselines and a combined $165,279 in September 2026 sales, implying category breadth is widening but still anchored in macro-dose gummies. The mix suggests Savvy is tilting toward functional formulations within Edibles while early Flower placements test breadth without yet displacing the gummy-led core.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

