

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Connected Cannabis Co. is stocked at 606 licensed dispensaries across California, New York, and 3 other states, 400 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Diego, San Francisco, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
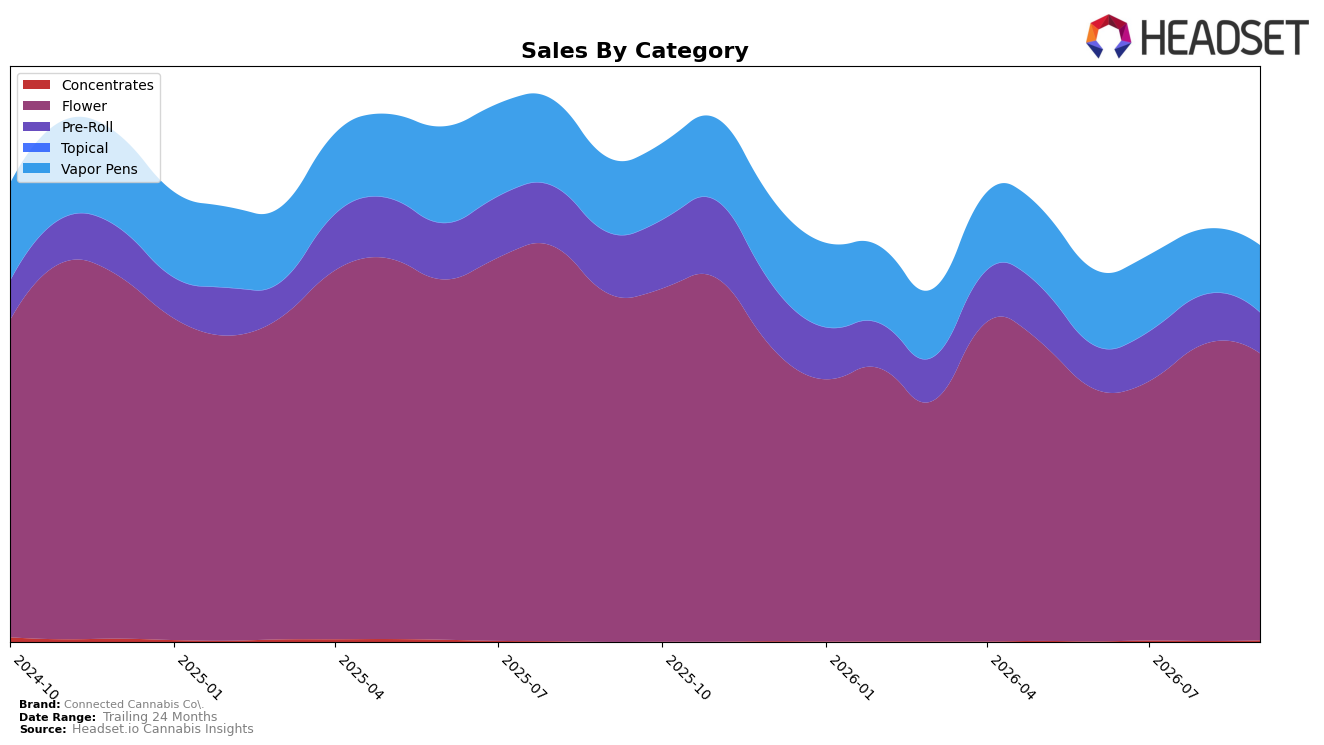
Connected Cannabis Co. concentrated 72.51% of September 2026 sales in Flower, down 17.62% year over year and 3.39% month over month, while Vapor Pens held 16.86% share with a 10.13% YoY decline but a 2.59% MoM uptick. Pre-Roll fell to 10.24% share with sales down 33.23% YoY and 17.31% MoM, as Concentrates rose to 0.39% share on a 5,635.83% YoY surge and 68.59% MoM growth from a small base; average price across the brand dipped 0.23% YoY. The pattern implies over-reliance on Flower is dragging overall results amid a brand-level sales decline of 18.11% YoY, while modest MoM growth in Vapor Pens and outsized but tiny-base gains in Concentrates are the few positive mix offsets.
With Flower ranked 18 in Arizona and holding a 72.51% mix, the category’s 17.62% YoY contraction and 3.39% MoM slippage point to weakening competitive footing where the brand is most exposed, whereas Vapor Pens’ 2.59% MoM growth against a 10.13% YoY decline suggests tactical traction that is not yet large enough at 16.86% share to change trajectory. Pre-Roll’s 17.31% MoM and 33.23% YoY drops at 10.24% share indicate share leakage in value-oriented formats despite a 0.23% YoY average price decrease, implying that near-term positioning should pivot toward stabilizing core Flower while scaling Vapor Pens and selectively nurturing Concentrates to rebalance risk.
Competitive Landscape
Connected Cannabis Co. sits at rank 20 in California Flower for September 2026, down 7 positions year over year from rank 13, and just 1 position higher than June 2026 when it was rank 21; in contrast, STIIIZY rose from rank 2 to rank 1 while expanding sales by 47.8%, and Oakfruitland jumped from rank 11 to rank 5 on 73.5% sales growth, indicating that share is consolidating at the top as Connected Cannabis Co.’s trajectory drifts away from its peak rank of 11 in August 2025 and implies the brand must counter accelerating up-market gains to avoid further rank erosion.

Notable Products
Toad Venom (3.5g) delivered the standout move with a +78.9% month-over-month surge to rank 1 in September 2026, while Permanent Marker (3.5g) slid -34.0% to rank 7, marking the steepest decline among the top SKUs. Biscotti (3.5g) climbed +18.4% to rank 3 as Gascotti (3.5g) fell -15.4% to rank 5, and Juici (3.5g) edged up +3.5% at rank 2; eight of the top ten are Flower SKUs, concentrating demand in a single format despite two Pre-Roll entries at ranks 6 and 10. The mix points to a pivot toward flagship eighths led by Toad Venom (3.5g), with volatility clustered in select legacy strains suggesting SKU pruning or batch-driven scarcity will shape near-term assortment strategy.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

