

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
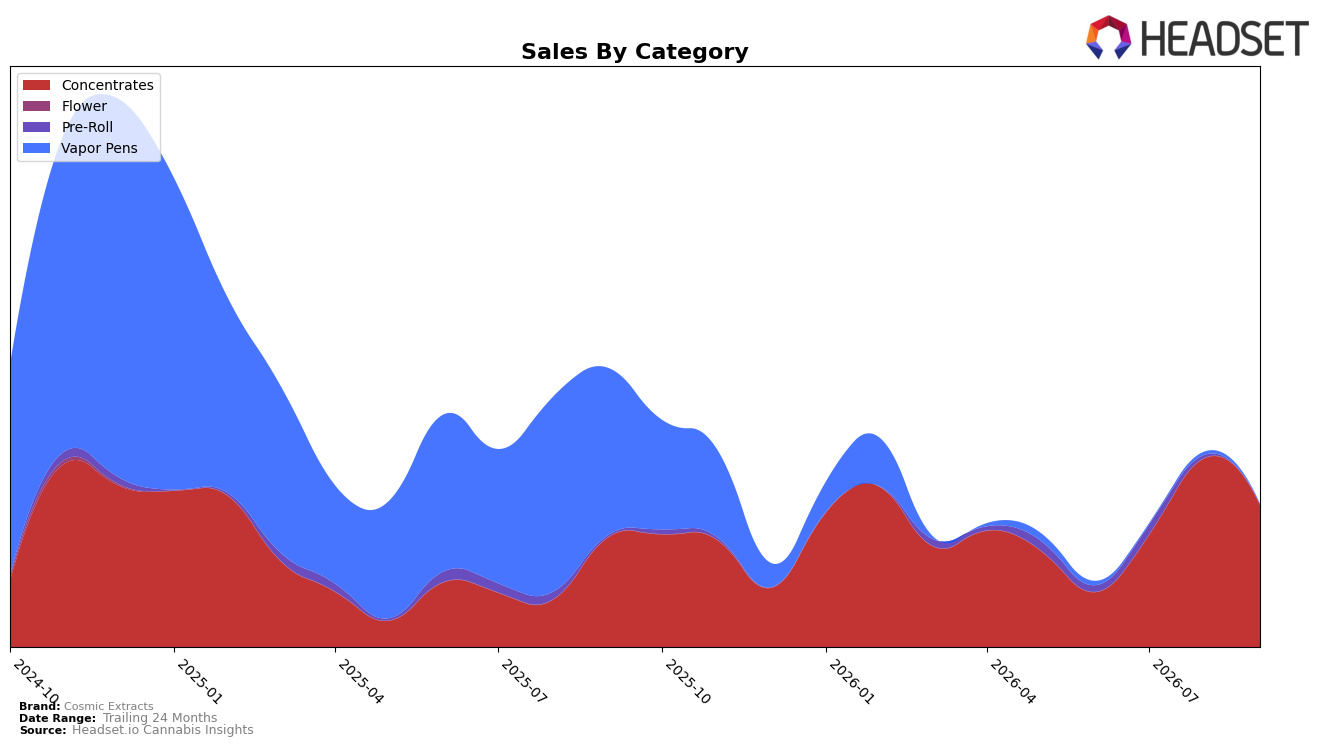
In September 2026, Cosmic Extracts concentrated almost entirely in Concentrates at 99.48% category share while Pre-Roll slipped to 0.52%, indicating a sharper pivot than typical seasonal mix shifts. Concentrates sales rose 29.33% year over year but fell 24.99% month over month, whereas Pre-Roll contracted 56.58% year over year and 72.51% month over month; alongside a 26.46% year-over-year rise in average price to $38.05, this pairing implies volume contraction paired with premium mix expansion. With overall brand sales down 48.83% year over year against a 6.84% decline over 24 months, the divergence between a rising Concentrates YoY and a steep MoM drop suggests a pull-forward or lumpy demand pattern rather than a broad-based recovery.
Within Saskatchewan Concentrates, Cosmic Extracts held rank 8 while maintaining a 99.48% mix in the format, signaling a niche-first stance that trades breadth for depth. The 29.33% YoY gain in Concentrates alongside a 24.99% MoM dip, coupled with a 56.58% YoY decline in Pre-Roll and a 72.51% MoM drop, points to reliance on fewer, higher-priced SKUs that lift price metrics but expose the brand to rank volatility at position 8. The pattern implies that September 2026 positioning is defensible when demand skews toward premium Concentrates, but the thin 0.52% Pre-Roll buffer and the 48.83% brand-level YoY decline leave limited insulation if category momentum softens further.
Competitive Landscape
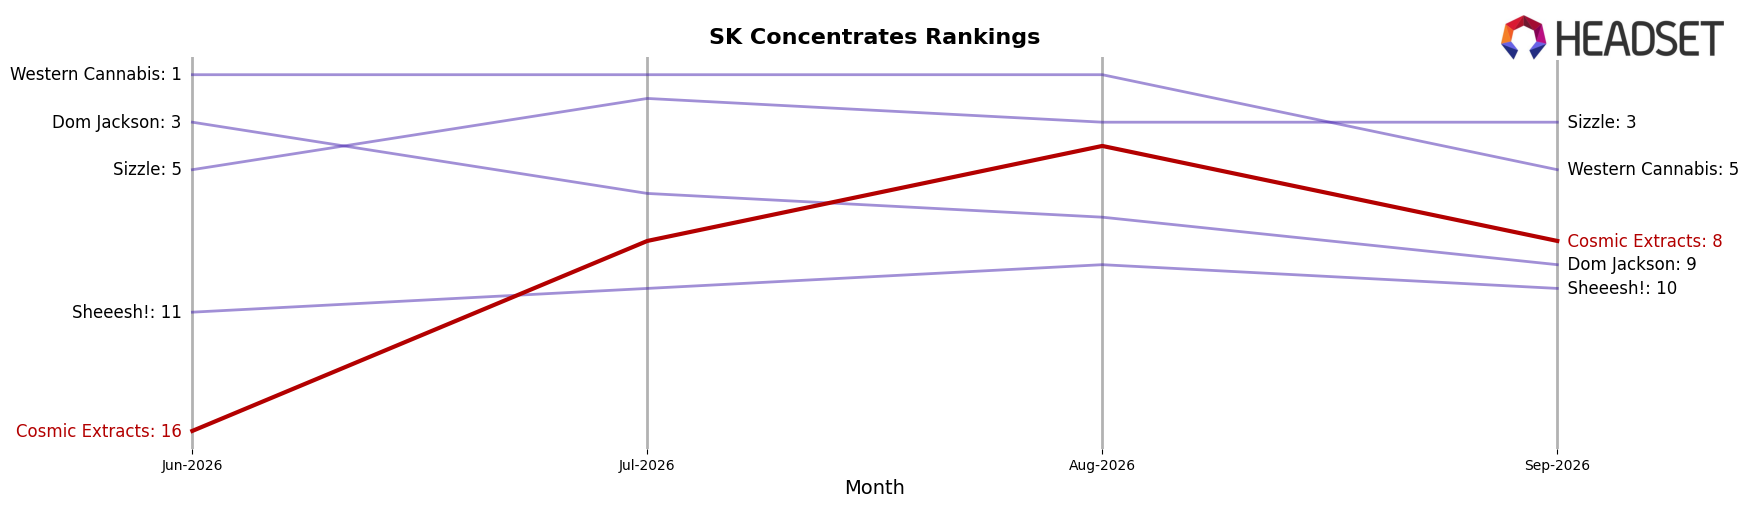
Cosmic Extracts sits at rank #8 in SK Concentrates in September 2026, down 3 places year over year from #5, but up 8 places versus June 2026 when it was #16; its peak of #4 in August 2026 and the one-month slide of 4 ranks into September contrast with BoxHot rising from #23 to #4 alongside a 527.6% year-over-year sales change and 7 Acres jumping from #13 to #2 with 372.3% year-over-year growth. Meanwhile, category stability among leaders is mixed, with Sizzle moving from #2 to #3 despite a -16.3% year-over-year sales change, and Herba Farms edging from #3 to #1 on 13.1% year-over-year growth; this split between momentum brands and softening incumbents implies Cosmic Extracts’ quick ascent then pullback signals a volatility-driven positioning where sustaining mid–top tier share will depend on converting August’s #4 spike into steadier rank retention.
Notable Products
Cereal Milk Live Rosin (1g) led September 2026 with a -24.9% month-over-month drop while holding rank 1, and Grapefruit Live Rosin (1g) fell -28.2% at rank 2. Together these declines at the very top imply category demand or pricing pressure within Concentrates is compressing velocity despite leadership positions, pointing to a need to rebalance mix away from overexposed SKUs. Bangerine Mints Infused Pre-Roll (1g) entered at rank 3 with $176 in sales and no prior-month baseline, and two of the top three SKUs are Concentrates, indicating concentration risk if live rosin softness persists. The pattern suggests Cosmic Extracts is reliant on a narrow live rosin core and should accelerate diversification into Pre-Rolls to stabilize rank and margin trajectory.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

