

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
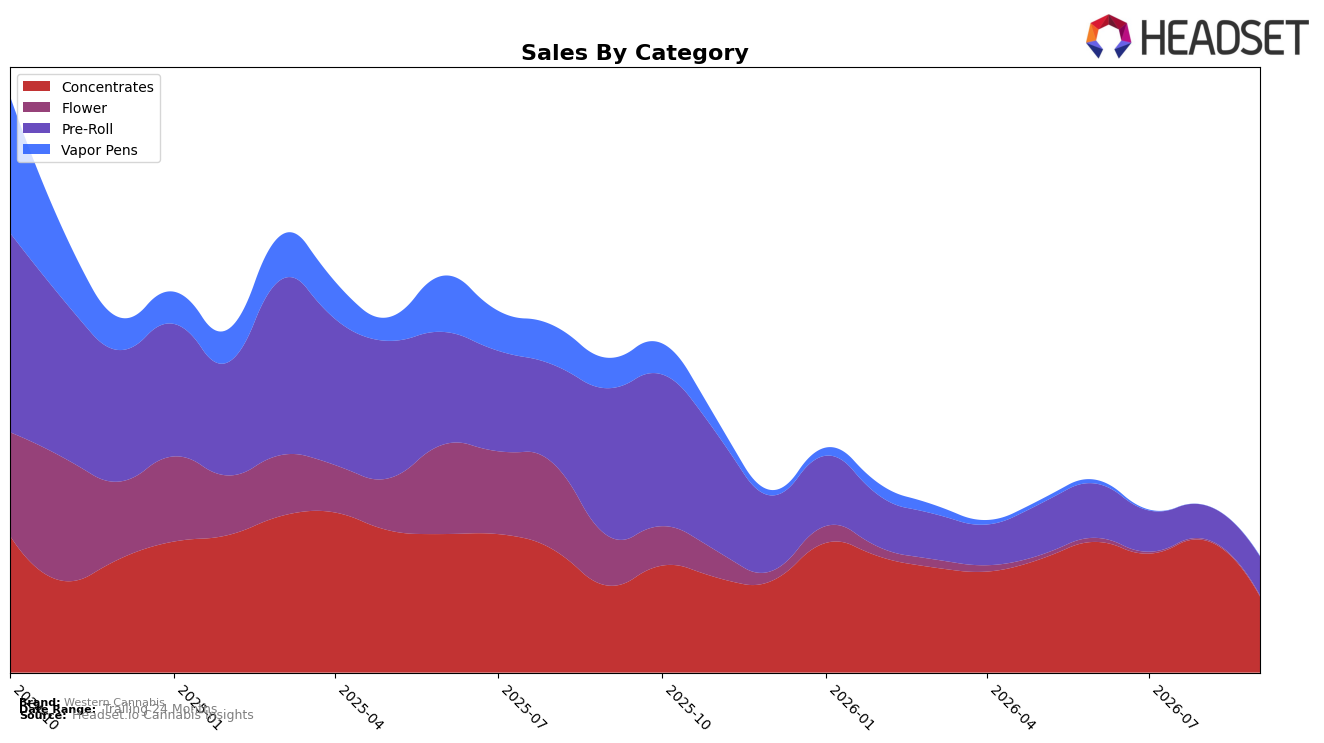
In September 2026, Western Cannabis concentrated 65.43% of sales in Concentrates, where year-over-year sales fell 12.53% and month-over-month declined 42.53%, while Pre-Roll rose to 33.30% share with a 14.80% month-over-month increase despite a 73.83% year-over-year drop; Flower contracted to 0.87% share with a 97.94% year-over-year decline and a 10.50% month-over-month dip, and Vapor Pens slipped to 0.40% share with a 98.48% year-over-year decrease. With an average price down 3.92% year over year to $25.56 and Concentrates ranked 5th in Saskatchewan, the mix indicates a pivot toward a two-category core where Pre-Roll is backfilling some Concentrates volatility but cannot offset the 63.04% brand-level year-over-year contraction.
The combination of a 42.53% month-over-month pullback in Concentrates alongside a 14.80% month-over-month lift in Pre-Roll suggests Western Cannabis is trading depth in its lead category for broader basket reach, but the 97.94% year-over-year collapse in Flower and the 98.48% year-over-year fall in Vapor Pens limit cross-category resilience. Holding a 5th-place rank in Concentrates while Pre-Roll expands share to 33.30% implies a positioning shift toward price-accessible formats and away from a multi-category footprint, meaning the brand competes as a specialist with narrowing optionality rather than a balanced portfolio player.
Competitive Landscape
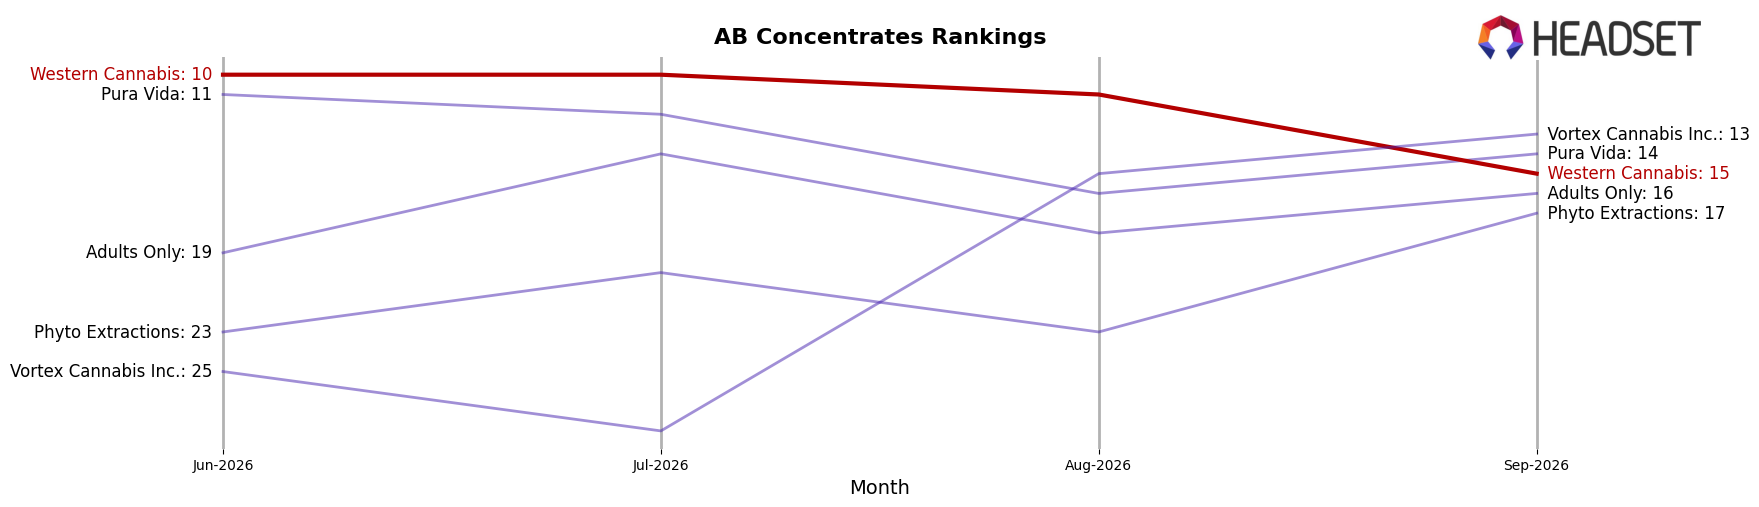
Western Cannabis sits at rank #15 in AB Concentrates in September 2026 after sliding 4 places year over year from #11, and dropping 5 positions from June 2026 when it was #10, despite a peak at #5 in February 2026; meanwhile, BoxHot held #1 year over year at #1 with sales up 5.8%, and Sticky Greens surged from #61 to #5 on 2,757.0% YoY growth, indicating Western Cannabis is ceding share to faster movers at the top and mid-tier. The combination of a 4-rank YoY decline to #15 and a 5-rank slide from three months ago, while peers like Dab Bods maintained #3 with 60.2% YoY growth and 3Saints improved from #5 to #4 with 15.3% YoY growth, implies Western Cannabis is on a downward trajectory that will require either mix reset or promotional intensity to avoid further rank erosion.
Notable Products
Electric Cherry Shatter (1g) posted the steepest decline at -53.5% while falling to rank 5, eclipsing the +50.7% jump of Orange Creamsicle Pre-Roll 12-Pack (6g) at rank 2, and Multipack of Madness Shatter (1g) slid -34.5% even as it held rank 1. Four of the top ten are Concentrates and five are Pre-Roll SKUs, but Concentrates skewed negative with -37.3% and -12.1% drops among top shatter items, whereas Pre-Roll momentum centered on a single high-growth pack alongside a -21.7% pullback at rank 9. The mix signals a pivot where multi-pack Pre-Rolls are absorbing demand that is exiting legacy shatter formats, implying near-term merchandising and promo weight should migrate from Concentrates toward scalable Pre-Roll bundles.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

