

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
CULTA is stocked at 81 licensed dispensaries across Maryland, with the deepest coverage in Baltimore, Silver Spring, Annapolis, Frederick, and Hagerstown. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
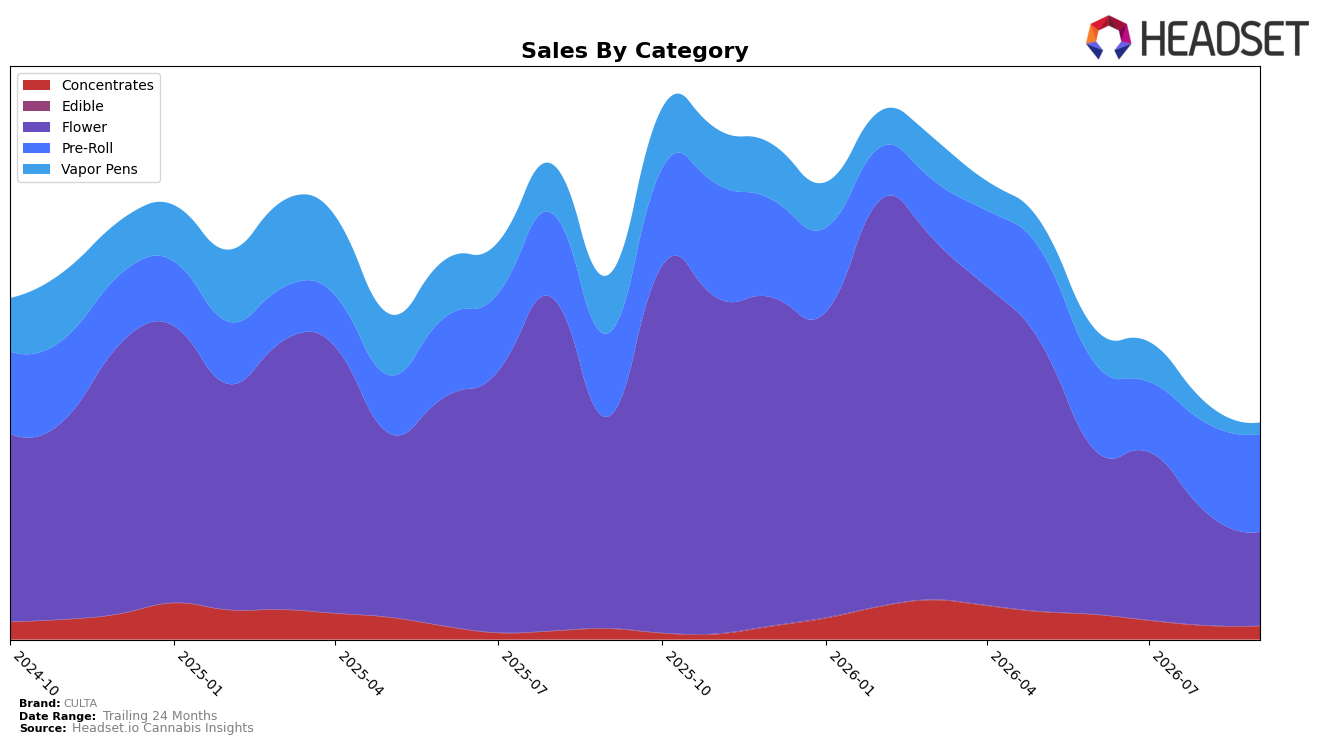
CULTA’s category mix in September 2026 tilts toward Pre-Roll at 45.26% share (ranked 8th in Maryland Pre-Roll), with Pre-Roll sales up 17.48% year over year and 9.91% month over month, while Flower holds 43.42% share but is down 55.76% year over year and 17.76% month over month. Smaller lines split: Concentrates at 6.10% share grew 26.62% year over year but slipped 2.69% month over month, Vapor Pens at 5.21% share declined 80.60% year over year and 44.05% month over month, and Edible at 0.01% share contracted 91.79% year over year and 87.61% month over month. Against a brand-level sales decline of 40.65% year over year and a 27.43% year-over-year drop in average price to $20.36, the mix indicates a pivot toward lower-price Pre-Rolls and away from high-ticket Flower and Vapor Pens, concentrating volume where rank is defensible and demand is more elastic.
The shift places CULTA as a value-weighted player anchored in Pre-Rolls (rank 8) and insulated by growth in Concentrates (+26.62% year over year) while de-risking exposure to categories with steep contractions like Vapor Pens (-80.60% year over year) and Flower (-55.76% year over year). With Pre-Roll momentum (+9.91% month over month) offsetting Flower retrenchment (-17.76% month over month), the brand’s pricing posture ($20.36 average; -27.43% year over year) suggests a deliberate trade-down strategy that preserves share in Maryland through mix realignment rather than premiumization, implying near-term positioning around high-frequency, lower-price formats while premium recovery is postponed.
Competitive Landscape
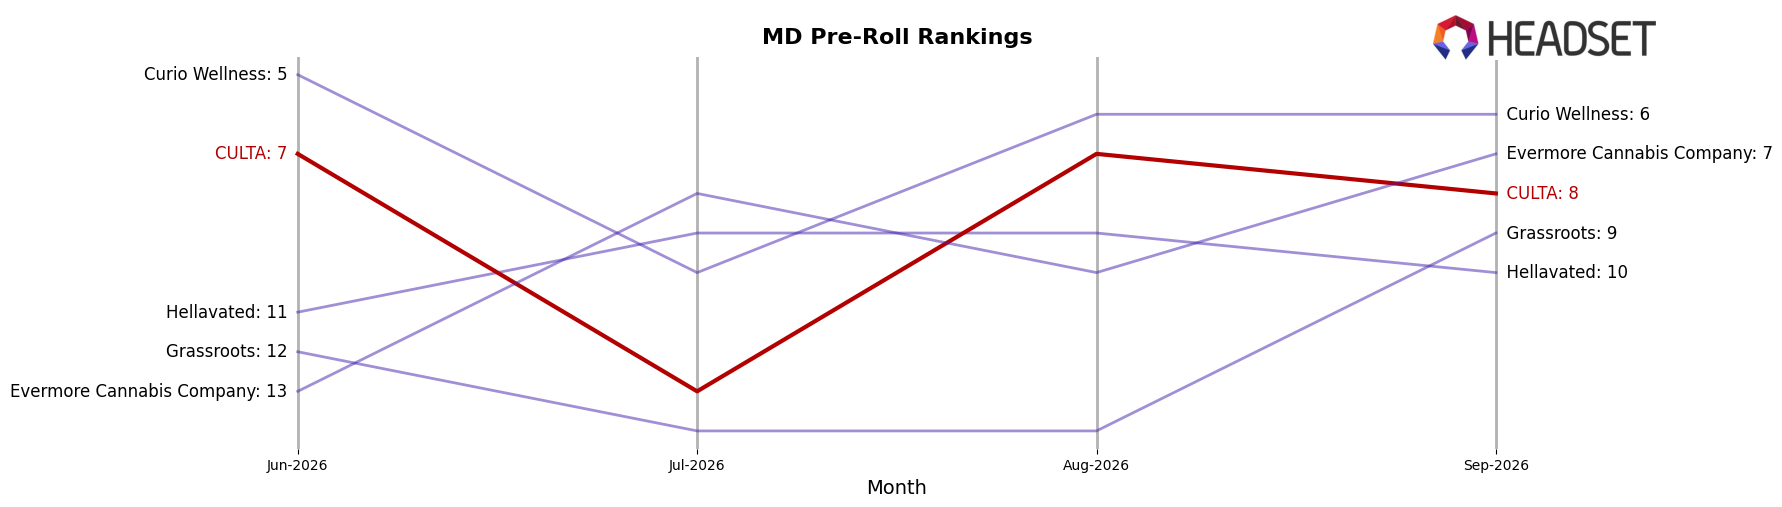
CULTA is ranked #8 in MD Pre-Roll in September 2026, improving 1 position year over year from #9, but sliding 1 position from June 2026’s #7 while still trailing its peak of #5 from September 2024; meanwhile, Strane jumped from #8 to #2 with 106.38% YoY sales growth and SunMed held #1 with 30.99% YoY growth, indicating that CULTA’s modest rank gain amid faster-moving rivals points to share pressure that, if unaddressed, implies a gradual drift toward the lower half of the top 10 rather than a return to the #5 peak.
Notable Products
Sugar Rush Pre-Roll 2-Pack (1g) posted the steepest decline at -41.6% MoM while sliding to rank 6, and Black Cherry Cream Pre-Roll 2-Pack (1g) fell -18.2% MoM at rank 4, indicating demand is consolidating away from mid-tier pre-rolls. In contrast, Amnesia OG Pre-Roll 2-Pack (1g) delivered a +53.6% MoM gain to reach rank 9, and Flower SKUs like Pink Nectar (3.5g) and Lava Lamp (3.5g) held ranks 7 and 10 as a counterweight to pre-roll volatility, with Pink Nectar (3.5g) generating $49,146. With eight of the top ten positioned in the Pre-Roll category, the portfolio is concentrated in formats prone to sharper swings, implying CULTA’s near-term commercial direction leans on pre-roll throughput while Flower provides stability.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

