

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
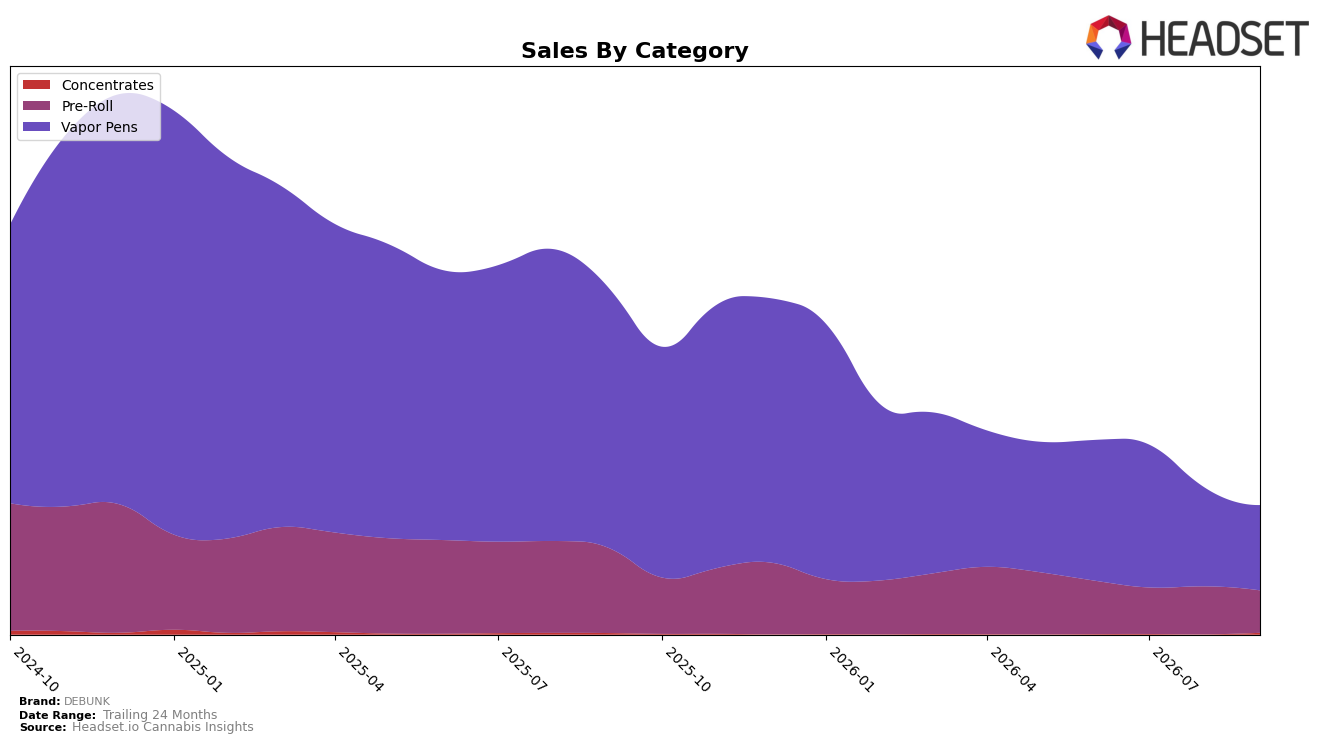
DEBUNK concentrated 65.91% of September 2026 sales in Vapor Pens while Pre-Roll contributed 32.72%, with Concentrates at 1.37%. Year over year, Vapor Pens fell 67.29% and Pre-Roll declined 50.34%, but Concentrates increased 15.57%; month over month, Vapor Pens dropped 13.71% and Pre-Roll slid 11.54% while Concentrates surged 532.90%. With an average price down 0.08% year over year and Vapor Pens ranked 21 in British Columbia, the mix skews toward a shrinking core while a nascent Concentrates line expands from a small base, implying reliance on Vapor Pens is increasingly costly to overall momentum.
The mix shift toward a smaller but rapidly accelerating Concentrates slice alongside double‑digit contractions in Vapor Pens and Pre-Roll suggests DEBUNK’s positioning is drifting from volume-led inhalables to a niche potency/value pocket. The 21 rank in Vapor Pens in British Columbia combined with a 67.29% Vapor Pens decline and a 50.34% Pre-Roll decline implies weakening shelf priority in the two largest lanes, while the 532.90% month-over-month jump in Concentrates indicates a tactical foothold where assortment depth or promotional rotation created outsized lift; strategically, this pattern implies DEBUNK should defend share in core inhalables while leaning into Concentrates to stabilize mix and reduce exposure to Vapor Pens volatility.
Competitive Landscape
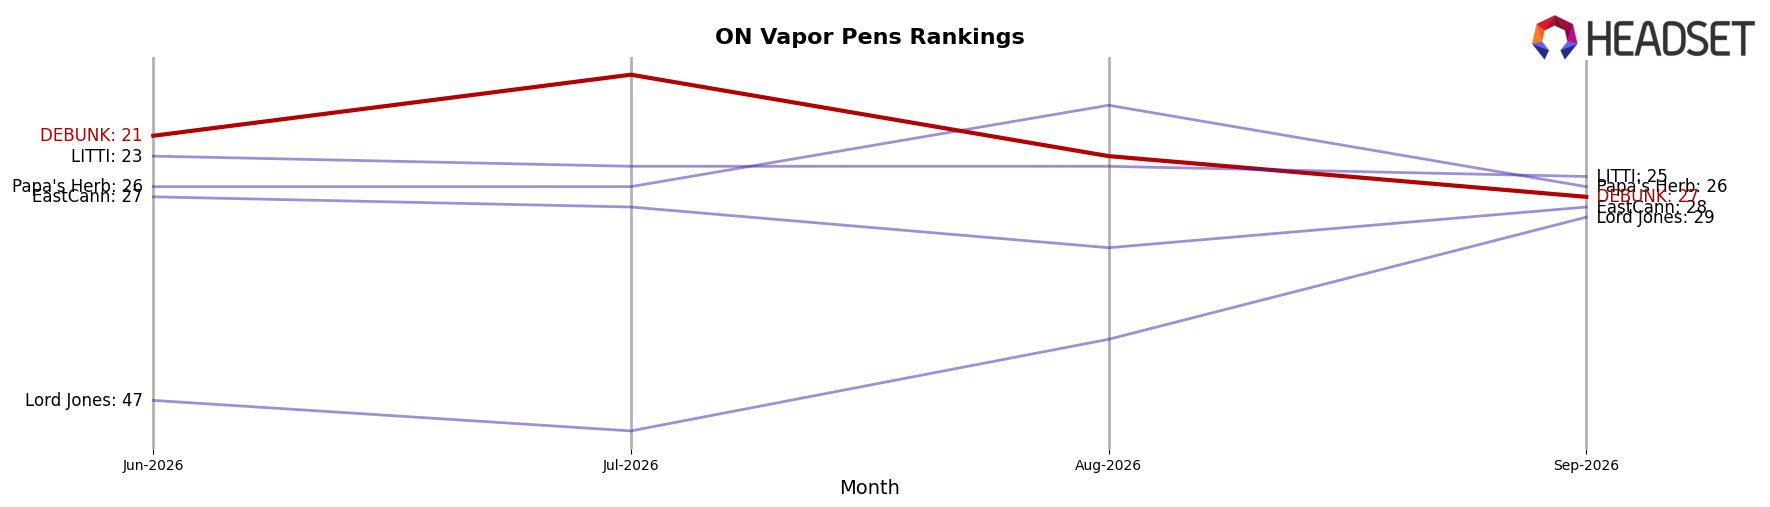
DEBUNK sits at rank #27 in ON Vapor Pens in September 2026, down 18 positions from its peak of #4 in January 2025 and sliding 6 places from #21 in June 2026; year over year its rank deteriorated by 18 spots from #9 to #27. In contrast, Spinach climbed from #4 to #1 with 172.5% YoY sales growth, while Kolab moved up from #14 to #5 alongside 93.0% YoY growth, indicating DEBUNK’s relative share is being ceded to faster risers at the top. The pattern implies DEBUNK’s trajectory has shifted from a January 2025 high-water mark toward the lower tier by September 2026, pointing to competitive displacement rather than short-term volatility.
Notable Products
ICE - Glass Apple Liquid Diamond Cartridge (1g) posted the steepest movement in September 2026 with a -23% month-over-month decline, sliding to rank 6 while ICE - Melonade Liquid Diamond Cartridge (1g) advanced +18% at rank 5. ICE - Moon Drops Liquid Diamonds Cartridge (1g) held rank 1 with a modest +7% gain, whereas Moon Drops Triple Bubble Hash Infused Pre-Roll 5-Pack (2.5g) dipped -8% at rank 2. Four of the top ten are Vapor Pens, and with two additional Vapor Pens at ranks 7–10 debuting or holding without MoM comps, the mix indicates a pivot toward cartridges despite softness in one SKU; this suggests DEBUNK is consolidating around Vapor Pens as its commercial anchor.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

