


Where to Buy
Direct (CA) is stocked at 11 licensed dispensaries across California, with the deepest coverage in San Diego, La Mesa, Chula Vista, Encinitas, and Lemon Grove. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
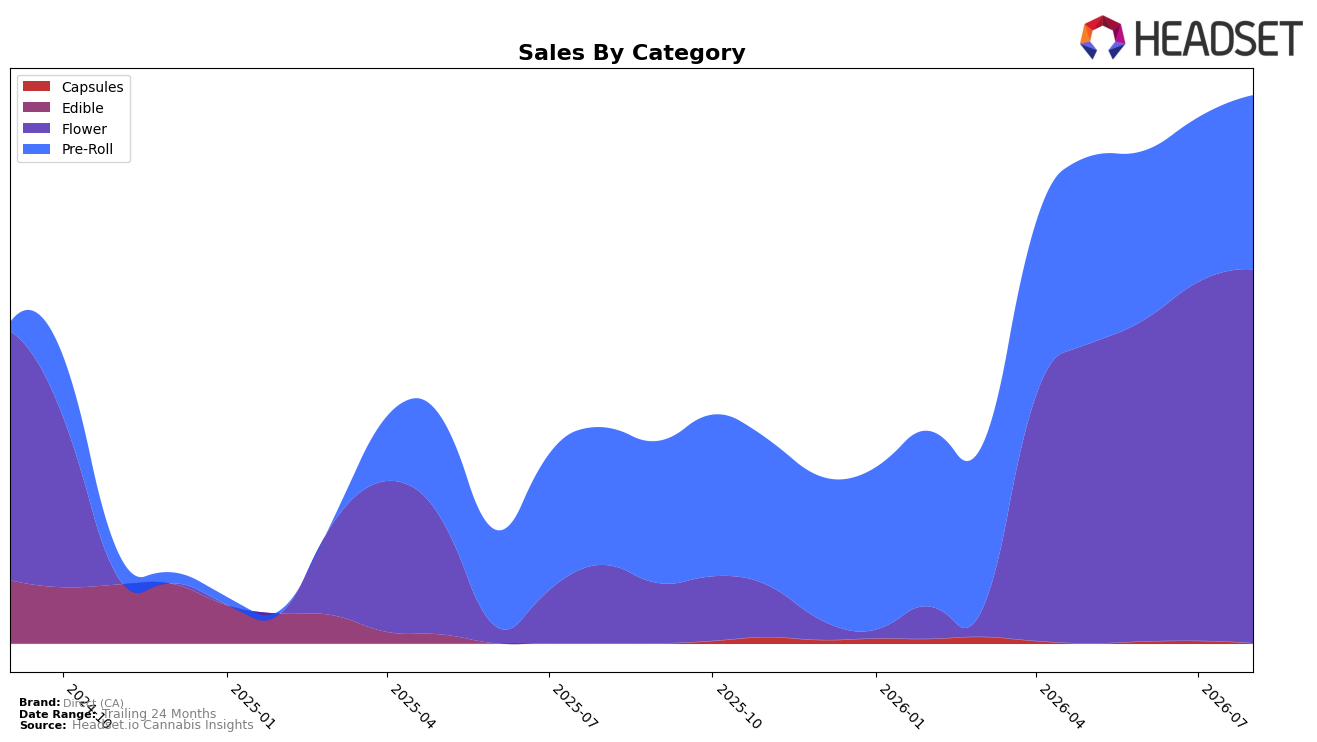
Direct (CA) concentrated 68.19% of August 2026 sales in Flower and 31.78% in Pre-Roll, with Capsules effectively rounding to 0.03% after a 93.03% month-over-month drop. Flower expanded 378.83% year over year and 4.20% month over month, while Pre-Roll grew 26.74% year over year and 5.91% month over month, indicating a tilt toward higher-velocity inhalables. With overall brand sales up 154.37% year over year and average price up 32.46%, the mix shift suggests volume-led gains in Flower at a higher average price point of $16.51, implying the brand is trading customers into larger Flower baskets while relying on Pre-Roll for incremental monthly lift.
Despite the heavy Flower orientation, a rank of 93 in California Flower places Direct (CA) deep in the long tail, even as Flower’s 378.83% year-over-year surge outpaced Pre-Roll’s 26.74% and held a 4.20% month-over-month gain versus Pre-Roll’s 5.91%. The near-exit of Capsules at 0.03% share and a 93.03% month-over-month decline consolidates resources into Flower and Pre-Roll, but the contrasting rank position with a 68.19% Flower share implies the brand’s positioning is breadth-limited within the category: maintaining momentum likely requires translating Flower growth into rank gains and using Pre-Roll’s faster month-over-month growth to widen entry points.
Competitive Landscape
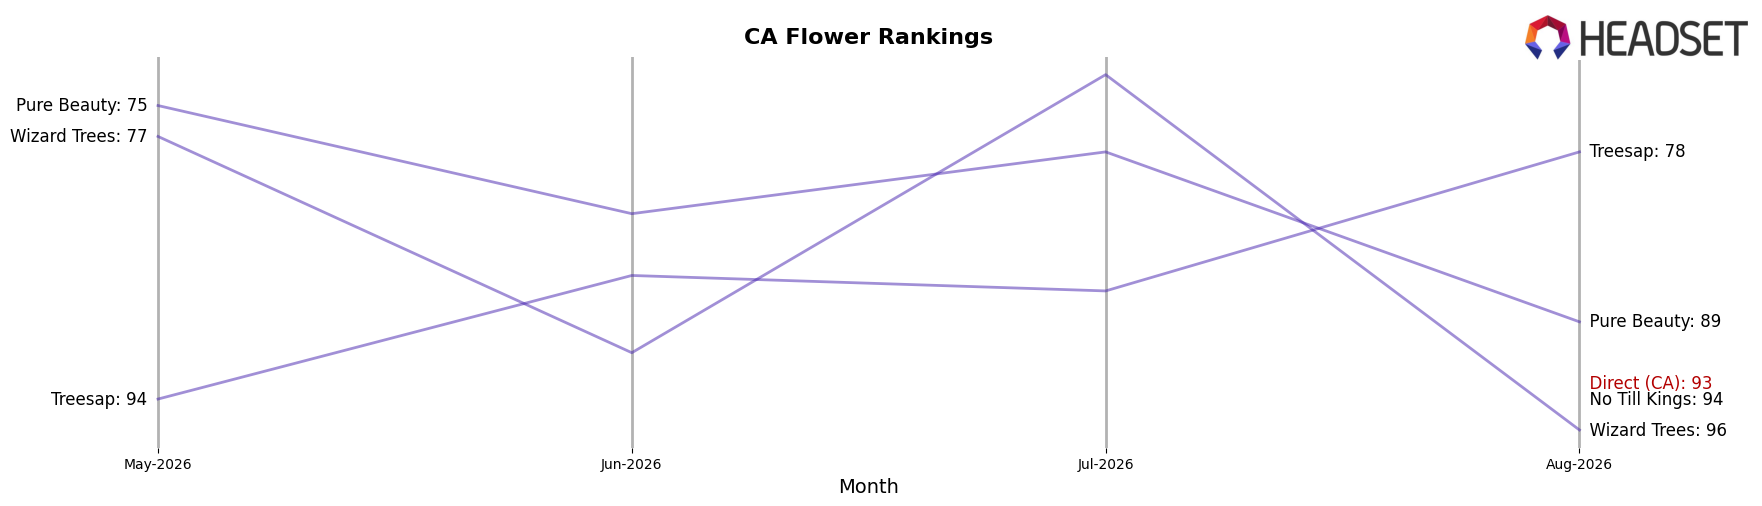
Direct (CA) sits at #93 in CA Flower for August 2026, improving 155 positions from #248 year over year and advancing 30 spots from #123 three months ago, while also hitting its peak rank at #93 in August 2026; in contrast, STIIIZY moved from #2 to #1 year over year with 50.40% sales growth, and CannaBiotix (CBX) slid from #1 to #3 with a -16.00% sales change, indicating Direct (CA)’s ascent is tied to mid-tier share recovery rather than top-tier displacement and implies a trajectory toward stable mid-pack relevance if momentum from a 155-rank YoY climb and a 30-rank three-month rise persists.
Notable Products
Biscotti Pre-Roll (1g) posted the standout movement in August 2026 with a month-over-month gain of 45.4% while climbing into rank 6, contrasted against Guava Pre-Roll (1g) slipping 6.3% at rank 4 and Frosting (3.5g) down 6.4% at rank 10. The top three positions are concentrated in Pre-Rolls—Skywalker OG Pre-Roll (1g) at rank 1 up 11.7% and Jack Herer Pre-Roll (1g) at rank 2 up 13.1%, with Lemon Haze Pre-Roll (1g) at rank 3 up 8.6%—indicating that Pre-Rolls account for three of the top five slots. Crazy Cookies Sugar Shake (14g) in Flower accelerated 39.7% at rank 7, while Astronaut (14g) entered at rank 8 with $29,862 and Crazy Cookies (3.5g) appeared at rank 9, signaling a secondary push from value and larger-format Flower alongside steady Pre-Roll momentum. The mix implies Direct (CA) is tilting assortment and demand capture toward Pre-Rolls for velocity while selectively leaning into value Flower to broaden basket options.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

