

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
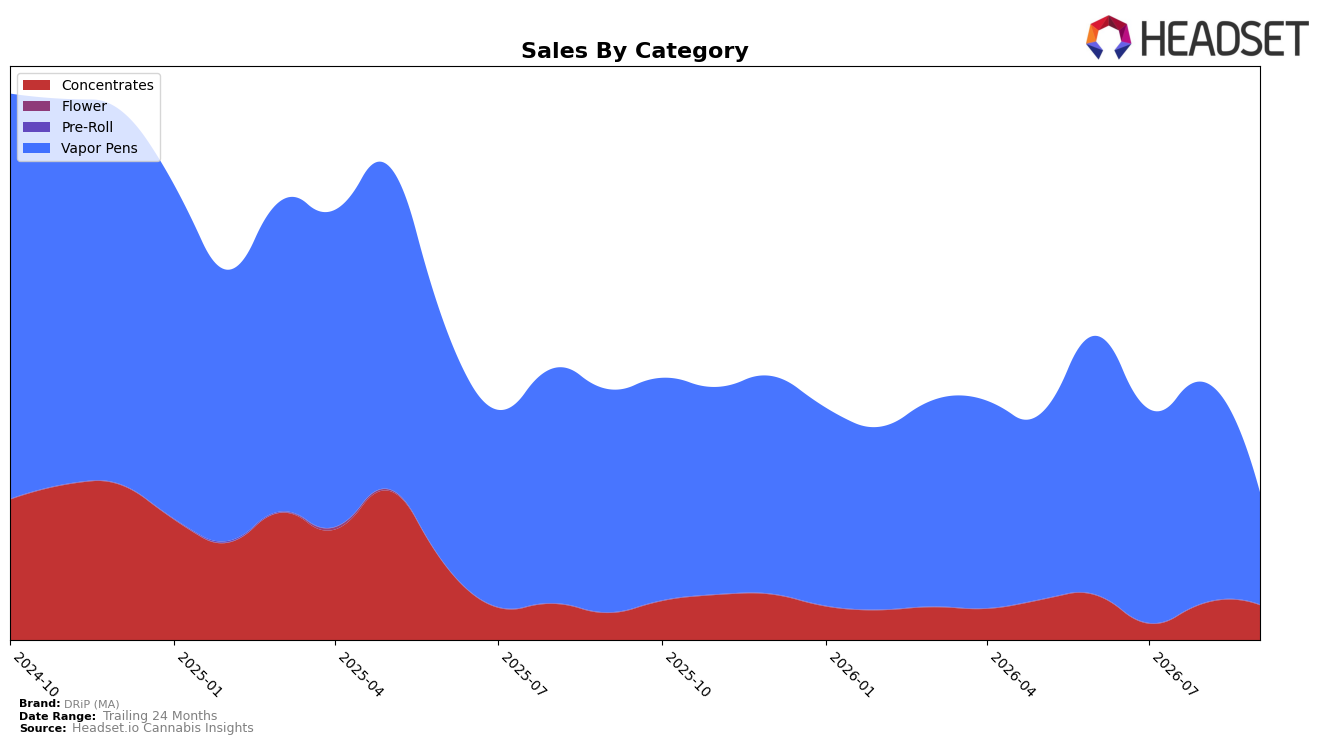
In September 2026, DRiP (MA) concentrated 76.50% of sales in Vapor Pens while allocating 23.50% to Concentrates, a mix that moved alongside a 49.77% YoY decline in Vapor Pens and a 29.39% YoY gain in Concentrates. Month over month, Vapor Pens fell 49.12% while Concentrates slipped 5.16%, with the average brand price down 41.66% YoY to $22.48, indicating price compression coinciding with the category shift. With Vapor Pens ranked 62 in Massachusetts, the data implies dependency risk in the lead category as share concentration in a rapidly contracting segment can amplify volatility rather than stabilize revenue.
The simultaneous 49.77% YoY contraction in Vapor Pens and 29.39% YoY expansion in Concentrates suggests DRiP (MA) is repositioning toward lower-priced, potency-driven formats without yet escaping mix exposure, as 76.50% of sales still sit in the declining anchor. The 49.12% MoM drop in Vapor Pens against only a 5.16% MoM dip in Concentrates implies that incremental shifts into Concentrates can cushion near-term swings, while the 41.66% YoY price reduction aligns with share migration into value tiers. Netting these dynamics, the pattern implies that accelerating mix diversification away from the 62-ranked Vapor Pens slot into Concentrates could reduce variance and rebuild rank headroom in Massachusetts even if overall category demand remains uneven.
Competitive Landscape
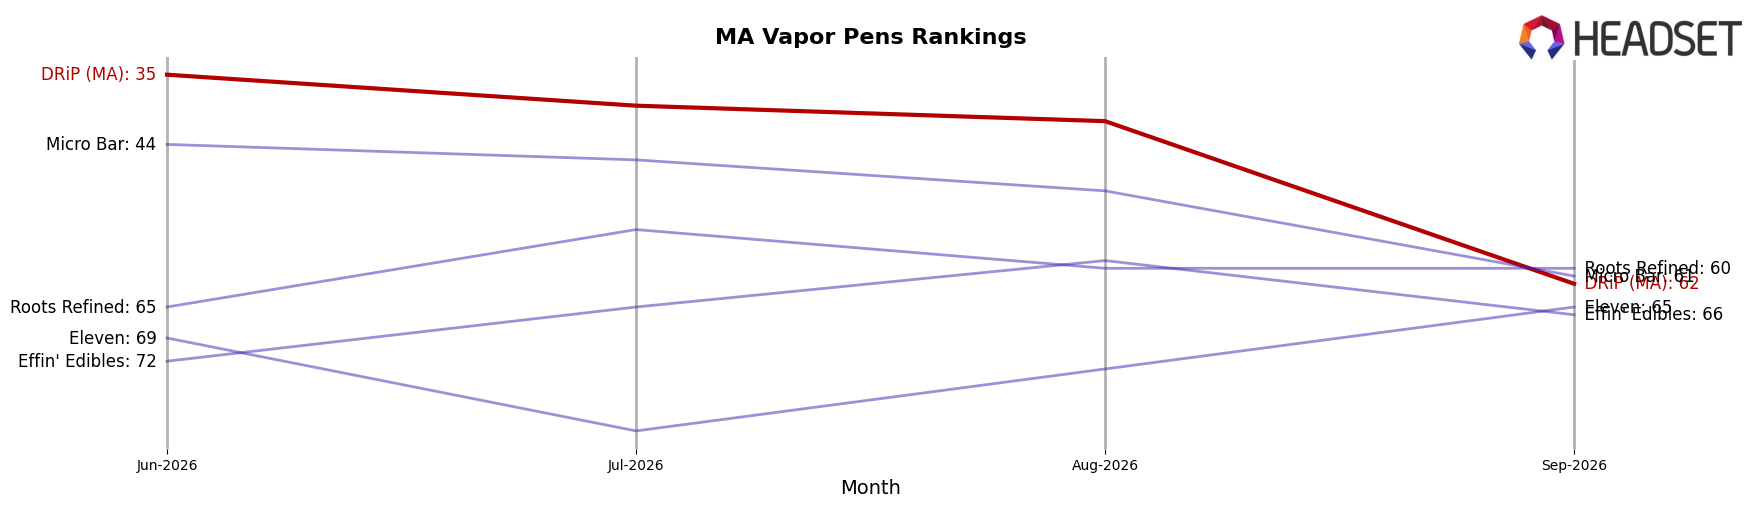
DRiP (MA) sits at rank #62 in MA Vapor Pens in September 2026 after a year-over-year slide from #37, a 25-place decline, and a quarter-over-quarter drop from #35, a 27-place fall; this contrasts with Jeeter jumping from #23 to #4 alongside 421.5% YoY sales growth and Fernway holding #1 with a 43.6% YoY increase while Select remains #2 despite an 11.7% YoY decline, indicating DRiP (MA) has ceded share since its #23 peak in October 2024 as momentum consolidates at the top.
Notable Products
Blueberry Pie Distillate Cartridge (1g) delivered the clearest movement in September 2026 with an 85% month-over-month increase and a rise to rank 1, while Lava Dawg Distillate Cartridge (1g) fell 54% month over month and slid to rank 6. Three Vapor Pens sit in the top five and six of the top ten are Vapor Pens, with Lava Dawg Live Resin Cartridge (1g) up 36% at rank 3 and GMO Live Resin Cartridge (1g) down 16% at rank 5. The Soap Live Resin Disposable (1g) dropped 56% to rank 7 despite top-10 placement and Blueberry Pie Distillate Cartridge (1g) led category dollar volume at $25,780. The pattern implies DRiP (MA) is consolidating around a few winning Vapor Pen SKUs while pruning or repositioning underperforming pen formats to sustain rank leadership.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

