

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
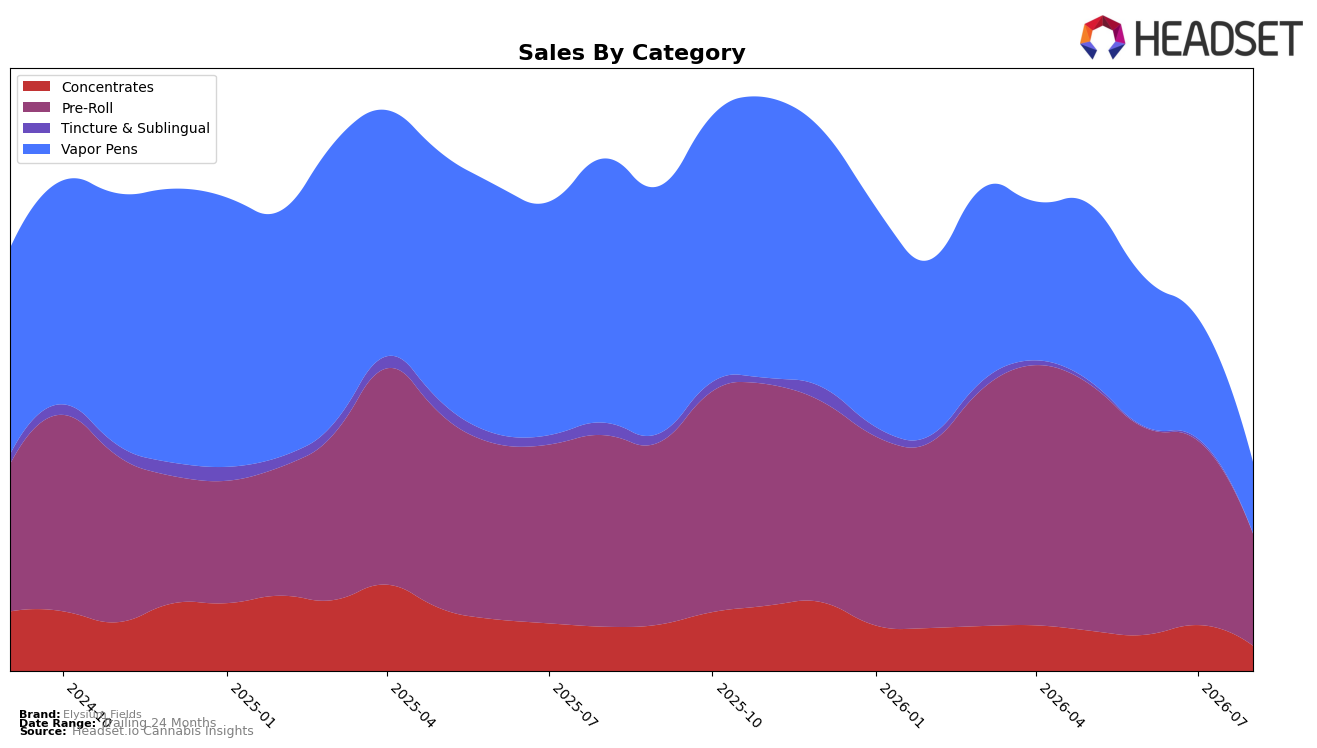
In August 2026, Elysium Fields concentrated 52.9% of sales in Pre-Roll while Vapor Pens held 33.8% and Concentrates 12.5%, with Tincture & Sublingual at 0.7%; this mix coincided with a brand-level year-over-year decline of 58.6% and a 24-month decline of 46.1%. Pre-Roll volume contracted with a 41.2% YoY drop and a 39.0% MoM dip as average price sat at $4.37, while Vapor Pens fell faster at 72.7% YoY and 40.6% MoM with a higher average price of $18.37; Concentrates dropped 41.4% YoY and 43.5% MoM, and Tincture & Sublingual plunged 88.9% YoY and 53.1% MoM. With a category concentration that tightened into lower-priced Pre-Rolls and an average price down 31.8% YoY, the pattern implies a deliberate pivot toward value packs and multi-unit offerings to defend unit throughput as premium-led segments retreat.
Elysium Fields’ rank of 33 in Oregon Pre-Roll, paired with Pre-Roll share at 52.9% and Vapor Pens at 33.8%, suggests a positioning anchored in accessible inhalables where price elasticity is driving trade-down. The sharper contraction in Vapor Pens at 72.7% YoY versus Pre-Roll at 41.2% YoY, alongside a 40.6% MoM dip in Vapor Pens against a 39.0% MoM dip in Pre-Roll, indicates that premium-adjacent formats are ceding wallet share to budget Pre-Roll; this implies the brand’s near-term competitive edge will rely on sustaining sub-$5 average price packs while rationalizing low-velocity, higher-priced SKUs to stabilize rank and share.
Competitive Landscape
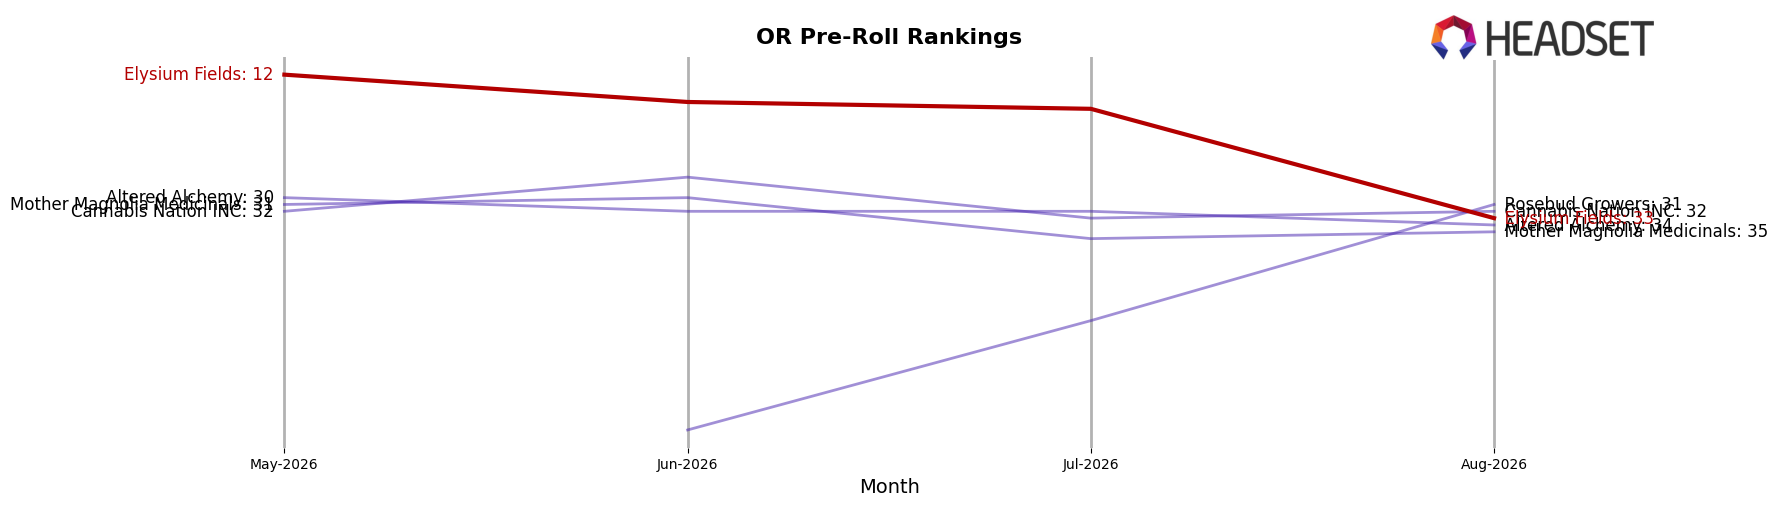
Elysium Fields sits at rank #33 in OR Pre-Roll in August 2026, down 15 positions year over year from #18, and 21 spots below its May-to-August trajectory after ranking #12 three months ago; the brand is also 22 places off its March 2026 peak of #11, indicating a sustained slide in share-of-shelf visibility relative to earlier in the year. In contrast, STiCKS held #1 year over year and remains #1 currently while growing sales 96.2%, and Kaprikorn rose from #5 to #2 with 128.9% sales growth, while Hellavated slipped from #2 to #3 alongside a 19.9% sales decline; this divergence implies Elysium Fields’ rank trajectory is signaling lost velocity amid intensifying top-tier gains, and without a reversal the brand risks drifting from mid-pack relevance to lower-tier status.
Notable Products
Blueberry Octane Pre-Roll (1g) posted the steepest movement in August 2026 with a -46.1% month-over-month drop, sliding to rank 3, while Frozen Bananas Pre-Roll (1g) mirrored the downturn at -46.4% and sat at rank 7, indicating compression among previously faster-moving SKUs. In contrast, Hawaiian Durban Pie Pre-Roll (1g) rose 35.4% month over month to rank 1, outpacing the broader lineup and signaling a shift in buyer preference toward single-gram Pre-Roll leaders over mid-pack variants. With eight of the top ten products concentrated in the Pre-Roll category and only one Vapor Pens SKU in the top ten at rank 9, mix is skewing toward combustibles even as volatility persists. This pattern implies Elysium Fields is consolidating around flagship Pre-Roll formats while ceding variety depth, a direction that favors high-velocity single SKUs over a balanced portfolio.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

