

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Private Stash is stocked at 36 licensed dispensaries across Oregon, with the deepest coverage in Portland, Eugene, Ontario, Astoria, and McMinnville. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
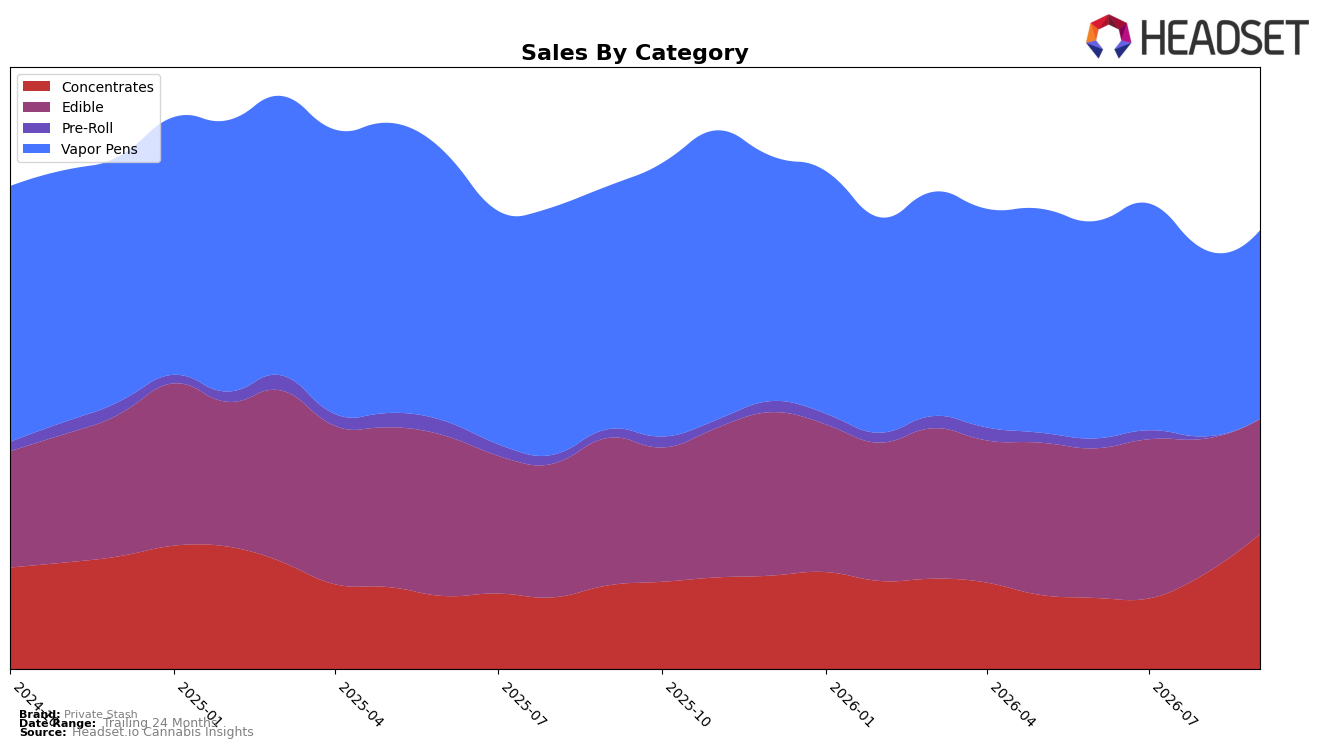
Private Stash concentrated its mix in three categories in September 2026: Vapor Pens at 43.00% share (rank 26 in Oregon Vapor Pens), Concentrates at 30.79% share, and Edible at 26.21% share. Year over year, Concentrates expanded 61.48% while Vapor Pens fell 22.52%, and month over month, Concentrates surged 42.14% as Edible contracted 15.01%; this divergence occurred alongside a modest 0.94% MoM uptick in Vapor Pens. With overall brand sales down 9.19% YoY and average price up 6.38%, the pattern implies volume has shifted away from Edible and partly from Vapor Pens into higher-velocity Concentrates, concentrating risk in two categories moving in opposite YoY directions.
The shift toward Concentrates (up 61.48% YoY and 42.14% MoM) against declines in Edible (down 22.02% YoY and 15.01% MoM) and pressure in Vapor Pens (down 22.52% YoY despite a 0.94% MoM lift) positions Private Stash as increasingly reliant on a growth pocket while its historical anchor category carries a September 2026 rank of 26 in Oregon. With average price up 6.38% and brand sales down 9.19% YoY, the mix suggests a trade-up or fewer units sold, so maintaining momentum in Concentrates while stabilizing Vapor Pens’ 43.00% share becomes the practical path to offset Edible drag and reduce exposure to rank slippage in a high-traffic aisle.
Competitive Landscape
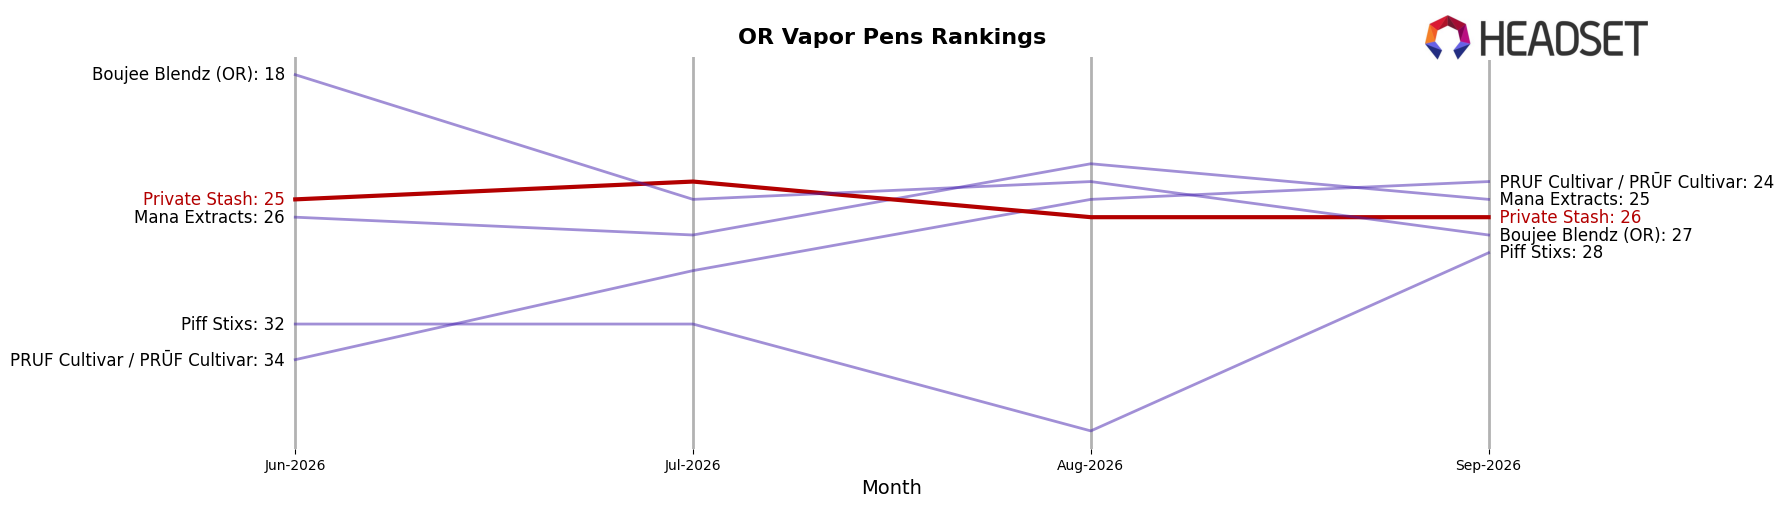
Private Stash sits at rank 26 in OR Vapor Pens in September 2026, down 4 positions year over year from rank 22 and slipping 1 place versus June 2026 when it was rank 25; despite having peaked at rank 19 in November 2025, the brand has not regained a top-20 foothold. Competitive context is tightening at the top: Entourage Cannabis / CBDiscovery held rank 1 year over year while its sales fell 15.2%, and FRESHY climbed from rank 5 to rank 3 with a 5.1% sales increase, indicating that headroom exists for share-taking even amid category softness. The combination of a 4-rank YoY decline and a 1-position slide quarter-on-quarter implies Private Stash is on a gradual downtrend that, absent a mix or distribution shift, risks further drift away from its November 2025 peak.
Notable Products
Mary Blueberry Blast Fruit Chew (100mg) posted the steepest decline in September 2026 at -35.3%, slipping to rank 8 while Hybrid Strawberry Is My Jam Fruit Chew Blast (100mg) fell -13.7% at rank 3. Hybrid Pink Lemonade Full Spectrum Fruit Chew Blast (100mg) still held rank 1 despite a -10.2% MoM dip, and Mango Serrano Full Spectrum Fruit Chew Blast 2-Pack (100mg) inched up +2.3% at rank 2. With eight of the top ten as Edibles and two SKUs tied around rank 4 seeing -15.7% and -15.1% declines, concentration in chews is high but softening at the top, implying Private Stash is leaning on a mature edible core while volatility at the tail suggests room to refresh flavors and formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

