


Where to Buy
Euphoria (MI) is stocked at 70 licensed dispensaries across Michigan and Oklahoma, 68 of them in Michigan, with the deepest coverage in New Buffalo, Grand Rapids, Monroe, Ann Arbor, and Battle Creek. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
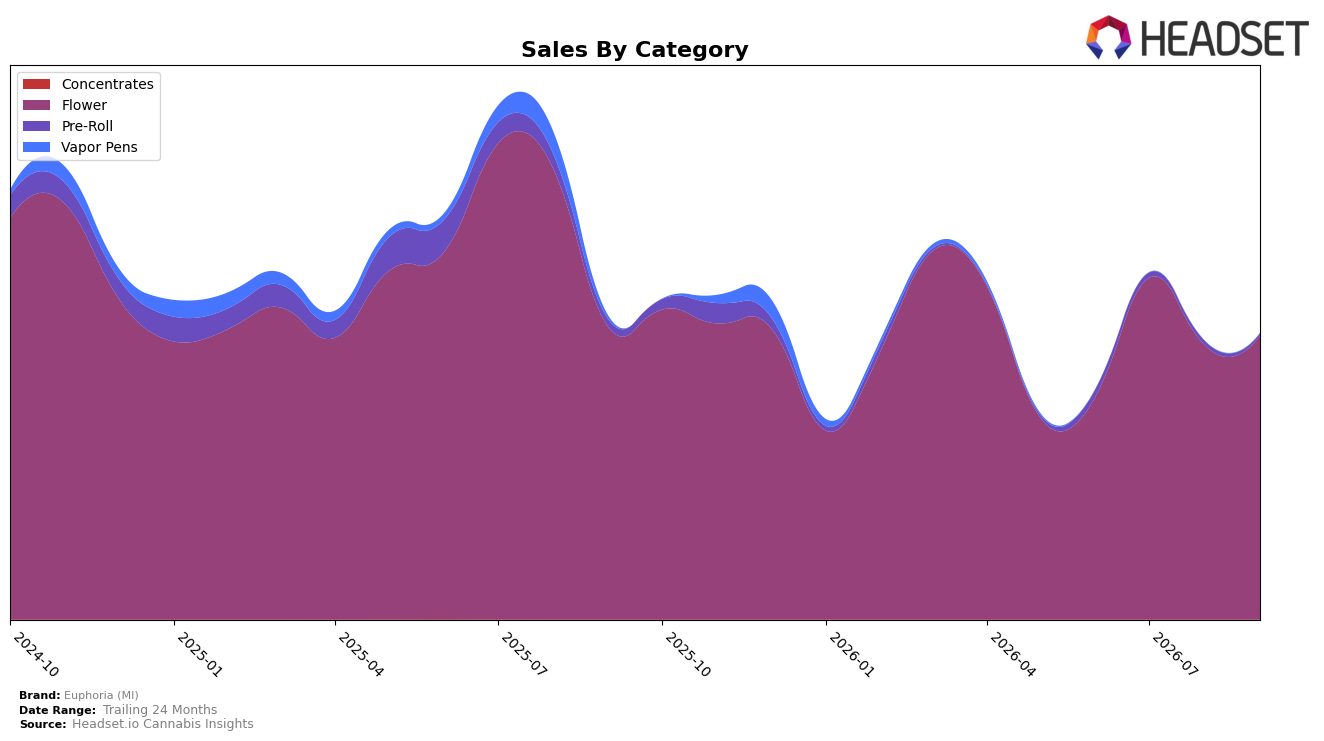
Euphoria (MI) concentrated 99.42% of September 2026 sales in Flower while Pre-Roll fell to 0.58% share, pairing a 3.55% month-over-month lift in Flower with a 57.31% month-over-month drop in Pre-Roll. Year-over-year, Flower declined 2.88% while Pre-Roll contracted 77.38%, against an overall brand sales decline of 5.71% and an average price decrease of 3.77%. With Flower ranked 25th in Michigan and its month-over-month growth outpacing the brand’s total trend, the mix indicates reliance on a single category for volume and a tactical deprioritization of Pre-Roll that reduces diversification risk coverage.
The shift toward a near-monoculture in Flower at 99.42% share alongside a 3.55% month-over-month gain, versus a 57.31% month-over-month contraction in Pre-Roll, implies a positioning that trades portfolio breadth for price-driven depth in core SKUs, consistent with a 3.77% year-over-year price reduction. Given the 2.88% year-over-year Flower dip and a 77.38% year-over-year Pre-Roll retreat, the brand’s 25th rank in Michigan Flower suggests competitive headroom is tied to sustaining Flower’s month-over-month momentum while selectively reintroducing incremental Pre-Roll presence to hedge against further single-category exposure.
Competitive Landscape
Euphoria (MI) sits at rank #25 in September 2026, improving 5 positions year over year from #30 while jumping 15 spots since June 2026 from #40, yet it remains 11 places below its peak at #14 from July 2025; in contrast, Play Cannabis advanced from #7 to #2 alongside 33.3% YoY sales growth and NOBO surged from #19 to #4 with 188.3% YoY sales growth, whereas category leader High Minded held #1 despite a 3.3% YoY sales decline. The combination of mid-tier upward mobility (+5 YoY ranks) and rapid short-term momentum (+15 ranks in three months), alongside competitors consolidating at the top (e.g., #7 to #2 and #19 to #4), implies Euphoria (MI) is on a recovery track but must convert recent rank gains into sustained share capture to avoid getting boxed out by faster risers.

Notable Products
Lemon Cream Cake (3.5g) delivered the standout movement with an 89% month-over-month gain and a rank at 1, while Donny Burger (3.5g) rose 19% to rank 8, indicating momentum concentrated at both the very top and the lower end of the top ten. Apples and Bananas (28g) in Flower edged up 4% while Lemon Cream Cake (28g) climbed 12% despite both listed at rank 4, and four of the top ten are Flower eighths, signaling skew toward smaller-format trial driving rank velocity. With eight of the top ten sitting in Flower and only one notable bulk entry, the mix implies Euphoria (MI) is leaning into premium eighths for traffic and using a few large-format SKUs to stabilize volume, with September 2026 dollar concentration anchored by Lemon Cream Cake (28g) at $78,024.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

