

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Fire Bros. is stocked at 236 licensed dispensaries across Washington, Michigan, and Oklahoma, 172 of them in Washington, with the deepest coverage in Seattle, Tacoma, Spokane, Bellingham, and Everett. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
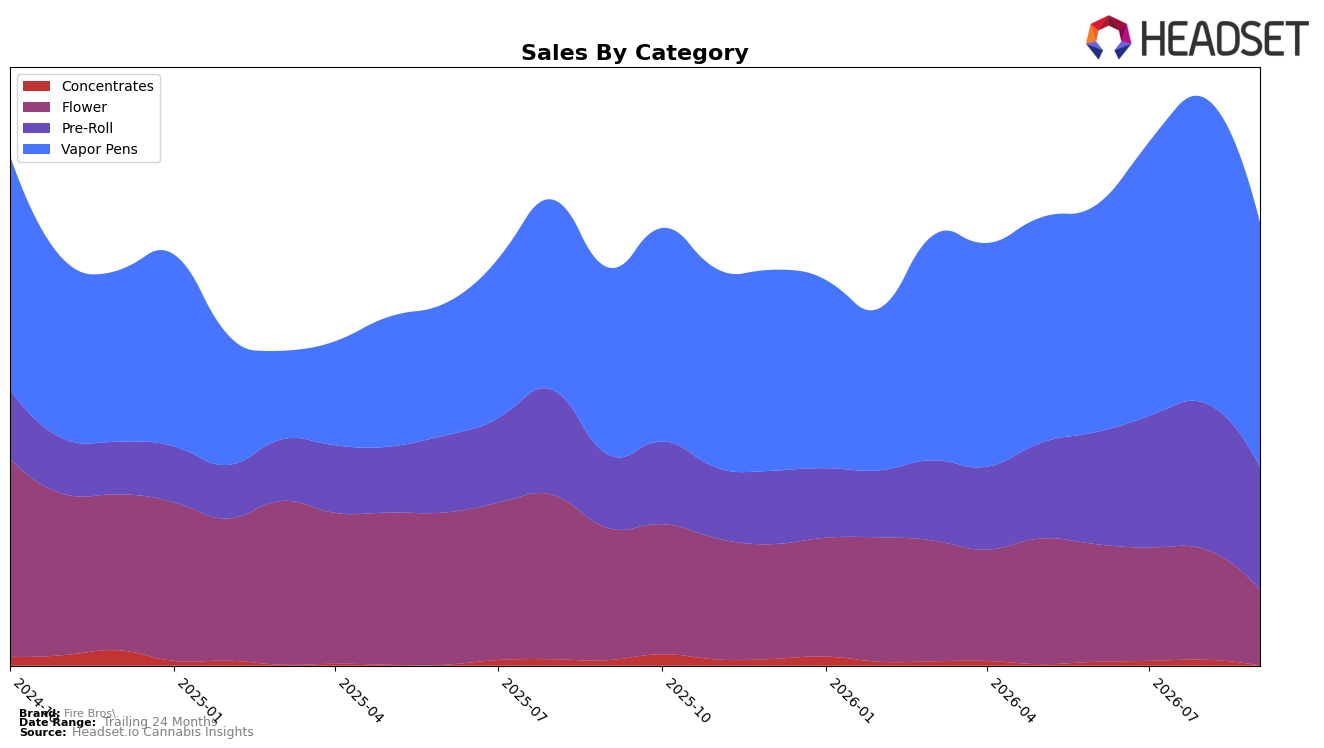
Fire Bros. concentrated over half of September 2026 sales in Vapor Pens at 51.01% share with a 27.99% year-over-year lift, even as month-over-month volume in the segment fell 18.76%; meanwhile, Pre-Roll expanded to 27.31% share with 53.90% year-over-year growth but declined 14.42% month-over-month. Flower shrank to 18.20% share with a 37.52% year-over-year drop and a 27.02% month-over-month decline, while Concentrates held 3.49% share with a 23.06% year-over-year decline and a 24.34% month-over-month slide. In price terms, the brand’s average ticket moved to $17.40 with a 3.96% year-over-year decrease, while Vapor Pens carried a $27.58 average versus $9.47 for Pre-Roll, indicating a mix shift toward lower-priced units despite Fire Bros. delivering 9.59% brand-level year-over-year growth; the pattern implies gains are driven by unit velocity in lower-priced formats while premium segments are contracting in the near term.
Given Vapor Pens rank 12 in Washington and posted 27.99% year-over-year growth alongside an 18.76% month-over-month dip, the category remains the brand’s anchor but with short-term headwinds, while Pre-Roll’s 53.90% year-over-year rise and 14.42% month-over-month pullback position it as the growth hedge as Flower retreats 37.52% year-over-year. With Pre-Roll averaging $9.47 versus Vapor Pens at $27.58 and the overall average price down 3.96% year-over-year, the widening gap suggests Fire Bros. is trading consumers into lower price points even as category share consolidates in two areas (51.01% Vapor Pens, 27.31% Pre-Roll); this implies the brand’s competitive positioning is tilting toward accessible, high-velocity formats at the expense of premium Flower and Concentrates, requiring reinforcement of margin management and differentiation within the two dominant formats to sustain the 9.59% year-over-year brand growth.
Competitive Landscape
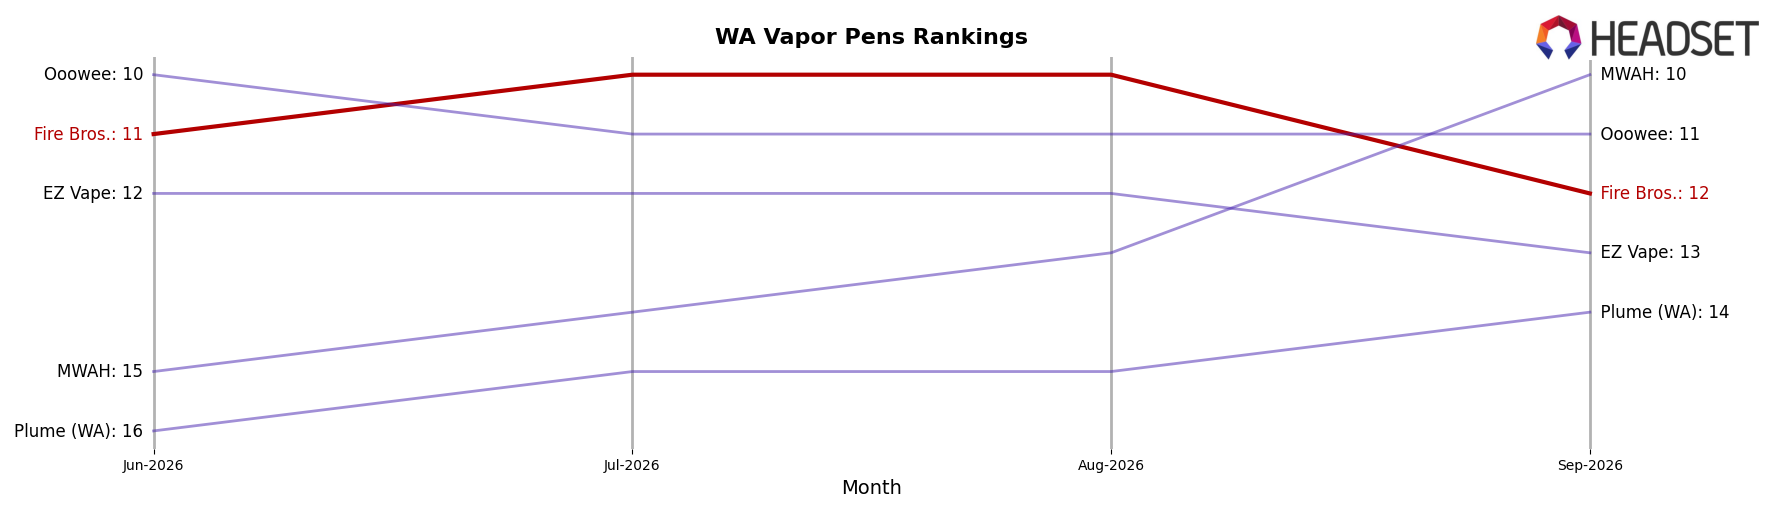
Fire Bros. sits at rank #12 in WA Vapor Pens for September 2026, unchanged YoY from #12, after slipping 1 spot from #11 in June 2026 and briefly peaking at #10 in August 2026; against this stagnation, Crystal Clear climbed from #3 to #1 with a 26.4% YoY sales gain while Mfused fell from #1 to #2 alongside a 30.9% YoY sales decline, indicating that Fire Bros.’ flat rank alongside competitor volatility implies a stable but non-advancing position that risks share drift unless conversion from peak-month momentum is sustained.
Notable Products
Pinyatti Pre-Roll 2-Pack (1g) posted the steepest retreat at -53.999% month over month while sinking to rank 10, and Jahmagic Pre-Roll 2-Pack (1g) also contracted by -22.342% at rank 8. At the top, Variety Pre-Roll 5-Pack (2.5g) held rank 1 despite a -7.030% decline, whereas Mixed Pre-Roll 5-Pack (2.5g) rose 13.631% to rank 6. With eight of the top ten SKUs concentrated in Pre-Roll 2-Packs and both 5-Pack formats diverging in momentum, the pattern implies Fire Bros. is leaning on multi-pack variety for stability while single-strain 2-Packs face sharper demand volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

