

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Focus North is stocked at 119 licensed dispensaries across Oregon, with the deepest coverage in Portland, Eugene, Bend, Beaverton, and Salem. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
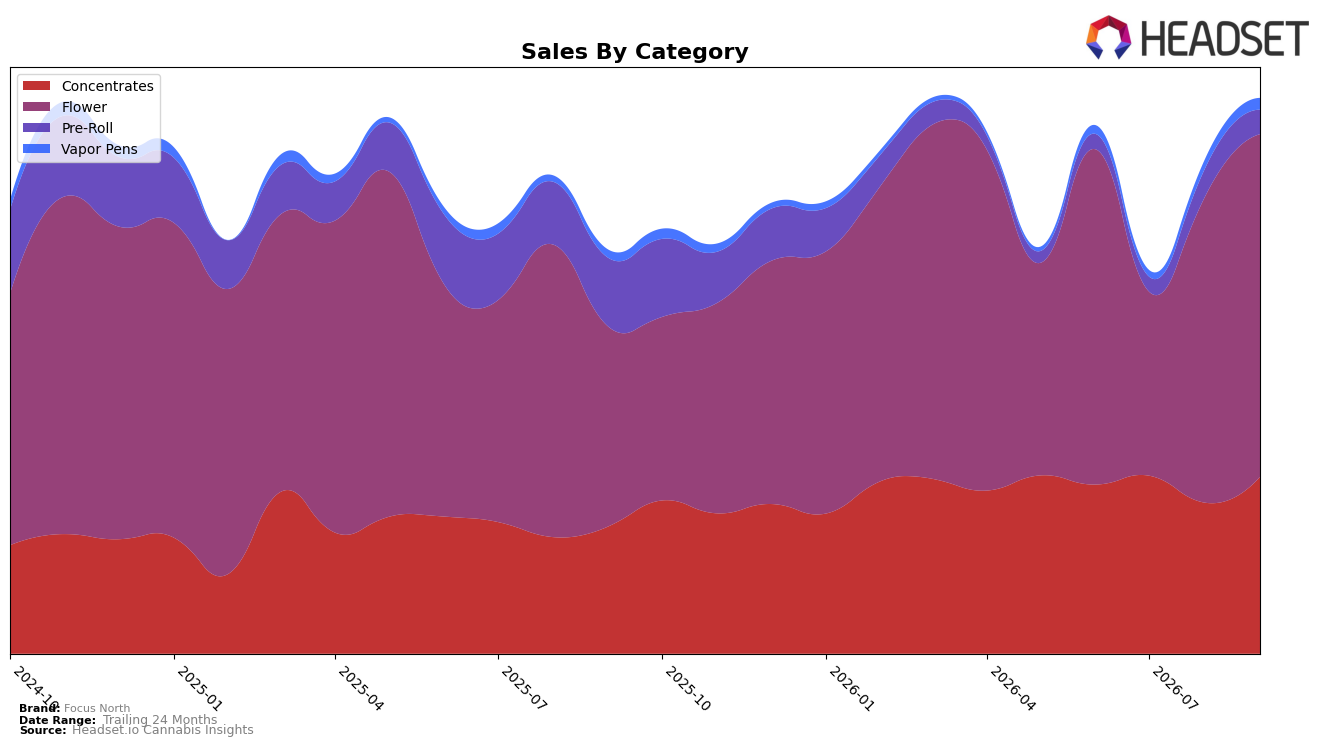
Flower expanded to 59.65% share with 68.71% year-over-year growth and 11.99% month-over-month, while Concentrates held 31.43% share with 36.58% year-over-year and 16.13% month-over-month; together these two categories now account for 91.09% of mix. In contrast, Pre-Roll contracted to 5.54% share with a 57.58% year-over-year decline and a 10.15% month-over-month drop, while Vapor Pens remain a small 3.38% share despite 21.36% year-over-year and 13.49% month-over-month gains. Average price rose 15.67% year-over-year to $35.34, with Flower priced at $34.18 and Concentrates at $52.66, indicating price-led contribution layered on volume expansion. The pattern implies Focus North is concentrating demand into Flower and Concentrates in September 2026, using price resilience to reinforce share even as Pre-Roll retrenches.
Ranked 15th in Flower in Oregon, the 59.65% Flower mix and double-digit month-over-month growth in both Flower (+11.99%) and Concentrates (+16.13%) position the brand to compete on depth where shoppers trade into higher-ticket segments. The 57.58% year-over-year decline in Pre-Roll and sub-6% share reduces breadth but raises focus on higher-price tiers, while Vapor Pens’ 13.49% month-over-month uptick from a 3.38% base offers optionality without diluting the core. Given total brand sales up 34.75% year-over-year alongside a 15.67% price lift, the mix shift implies a deliberate tilt toward categories that can sustain rank advancement in Flower and margin capture rather than rebuilding lower-priced Pre-Roll volume.
Competitive Landscape
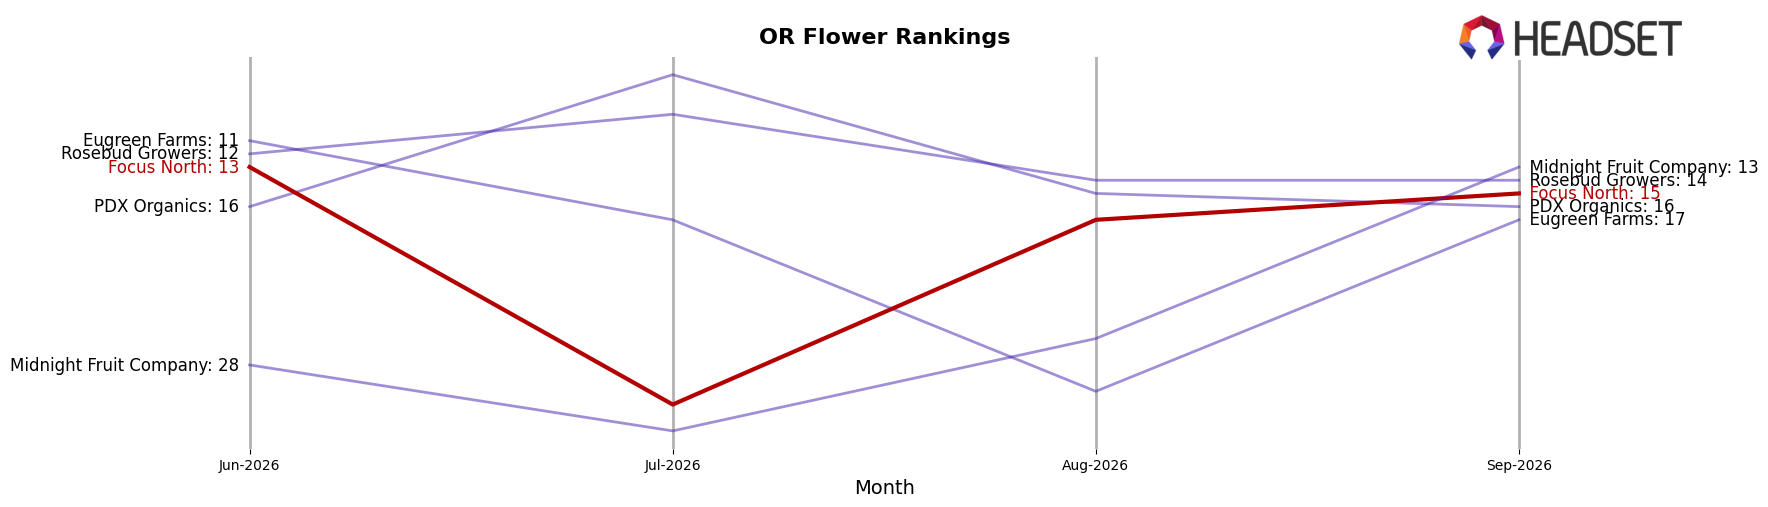
Focus North sits at rank #15 in September 2026, improving 10 positions from #25 year over year, but slipping 2 spots from #13 in June 2026 and sitting 4 places below its peak at #11 in March 2026; meanwhile, Grown Rogue moved up from #3 to #1 with 63.8% year-over-year sales growth and Oregrown surged from #16 to #3 with 169.7% growth, outpacing Focus North’s rank gains despite Focus North’s double-digit YoY climb. The combination of a YoY rank rise of 10 positions alongside a recent 2-position quarter-over-quarter dip implies Focus North has regained relevance year over year but is losing near-term share-of-mind to faster-accelerating leaders, signaling a need to convert past momentum into sustained, in-quarter rank defense.
Notable Products
El Chivo (Bulk) posted the steepest decline at -42.8% while sliding to rank 5, contrasting with Pot Roast (Bulk) jumping +55.8% at rank 1 and setting the pace for September 2026. Hash Burger (Bulk) added +34.8% at rank 4 as Pink Passion (1g) fell -33.9% at rank 6, and five of the top ten SKUs are Flower products, concentrating share at the top of the ranking. This split between a +55.8% surge and a -42.8% pullback in adjacent Flower SKUs implies the brand is shifting demand toward a narrower set of winning strains rather than broad lift across the portfolio.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

