

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
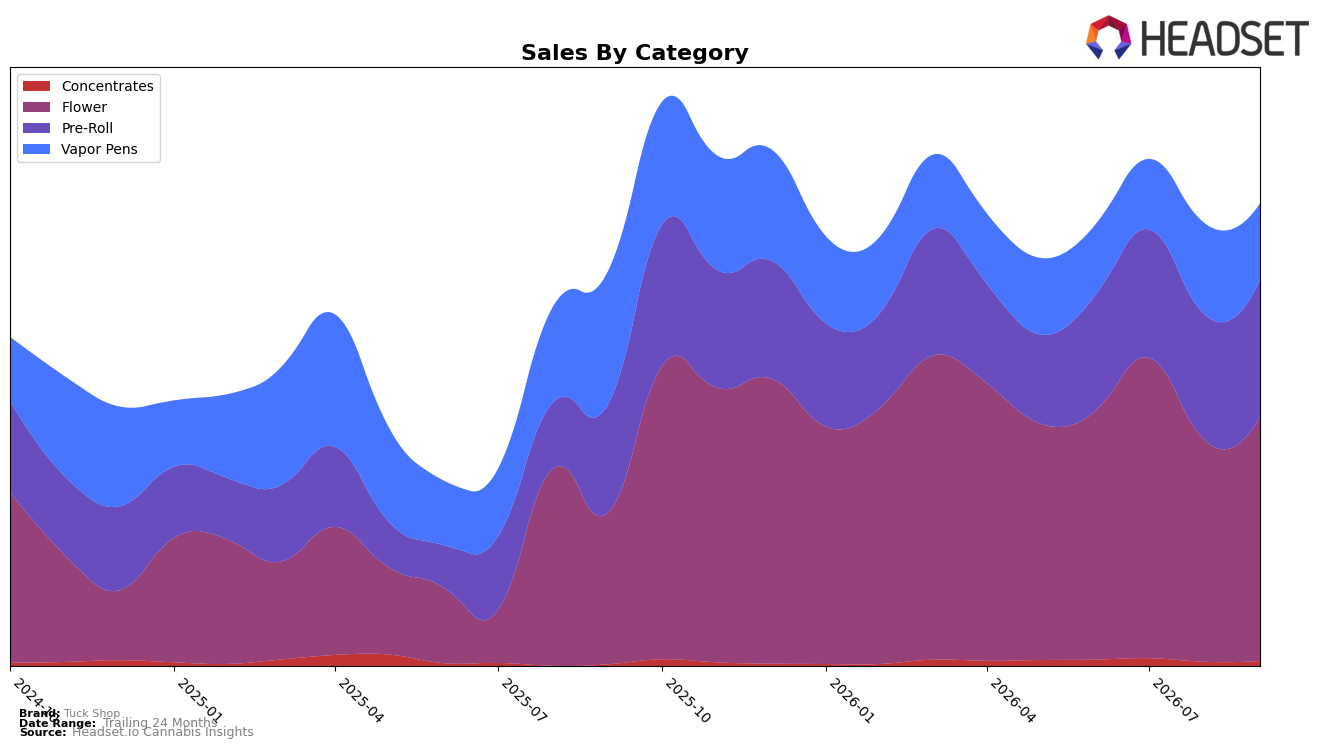
In September 2026, Tuck Shop’s mix concentrated further into Flower at 50.76% share with year-over-year growth of 57.47% and month-over-month growth of 9.79%, while Pre-Roll held 29.24% share with 23.90% YoY and 8.32% MoM. Vapor Pens contracted to 17.17% share with -39.79% YoY and -14.75% MoM, and Concentrates remained small at 2.83% share with 30.37% YoY and 5.84% MoM. With overall brand sales up 15.57% YoY and an average price up 2.87% to $36.30, the pattern implies Tuck Shop is leaning into higher-velocity inhalables led by Flower and Pre-Roll while actively retrenching from Vapor Pens.
Tuck Shop’s position in Ontario Flower at rank 25, alongside a 57.47% YoY and 9.79% MoM surge in Flower, indicates headroom tied to depth in core Flower rather than breadth across categories; the -39.79% YoY and -14.75% MoM in Vapor Pens suggests de-prioritization or portfolio pruning. The 23.90% YoY lift in Pre-Roll with 8.32% MoM, coupled with Concentrates growing 30.37% YoY but staying at 2.83% share, points to a strategy that consolidates around two primary inhalable formats while limiting exposure to underperforming vapes; this mix is likely to support incremental rank gains in Flower if execution continues to convert category momentum into share.
Competitive Landscape
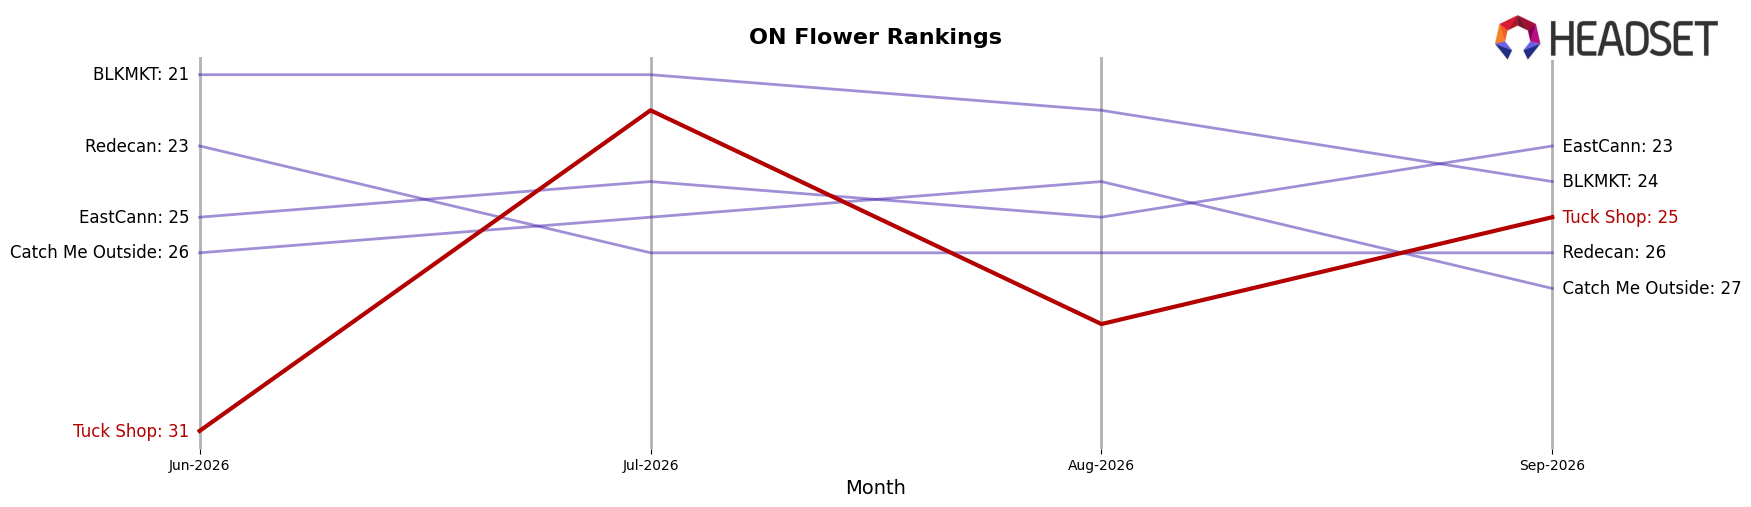
Tuck Shop sits at rank 25 in ON Flower in September 2026, improving 21 spots from rank 46 year over year, yet slipping 4 places from rank 21 at its July 2026 peak to rank 25 now while also falling -14.8% in position versus rank 31 three months ago; meanwhile, Spinach rose from rank 3 to rank 1 with year-over-year sales up 15.7%, and FIGR jumped from rank 14 to rank 5 with sales up 51.7%, indicating that Tuck Shop’s mid-pack climb is outpaced by leaders consolidating at ranks 1–5 and suggests the brand’s rank trajectory points to a need to convert short-term gains into sustained share to avoid being boxed out by faster risers.
Notable Products
Georgia Cream Pre-Roll 5-Pack (2.5g) delivered the outsized move in September 2026 with +144% MoM and a jump to rank 1, while Hawaiian Marker Pre-Roll (1g) fell -25% to rank 5; this spread signals a shift toward multi-pack value over single-stick formats. Pre-Rolls held six of the top ten slots, with Garlic Mintz Pre-Roll 5-Pack (2.5g) steadying near rank 2 at -1% MoM and Hawaiian Marker Pre-Roll 14-Pack (7g) up 8% at rank 4, whereas Vapor Pens like Hawaiian Marker Pure Cured Resin Disposable (1g) slipped -16% at rank 8; the category tilt implies lineup emphasis on pack-led Pre-Rolls over disposables. Flower steadied in the middle with Hawaiian Marker (7g) up 3% at rank 3 and Black Diamond X (7g) up 4% at rank 7 against a single raw sales leader of $139,666 for Hawaiian Marker (7g), suggesting core flower sustains baseline demand while growth concentrates in multi-pack Pre-Rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

