


Where to Buy
Gold Label Cannabis is stocked at 12 licensed dispensaries across Colorado, with the deepest coverage in Denver, Avon, Boulder, Colorado Springs, and Edgewater. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
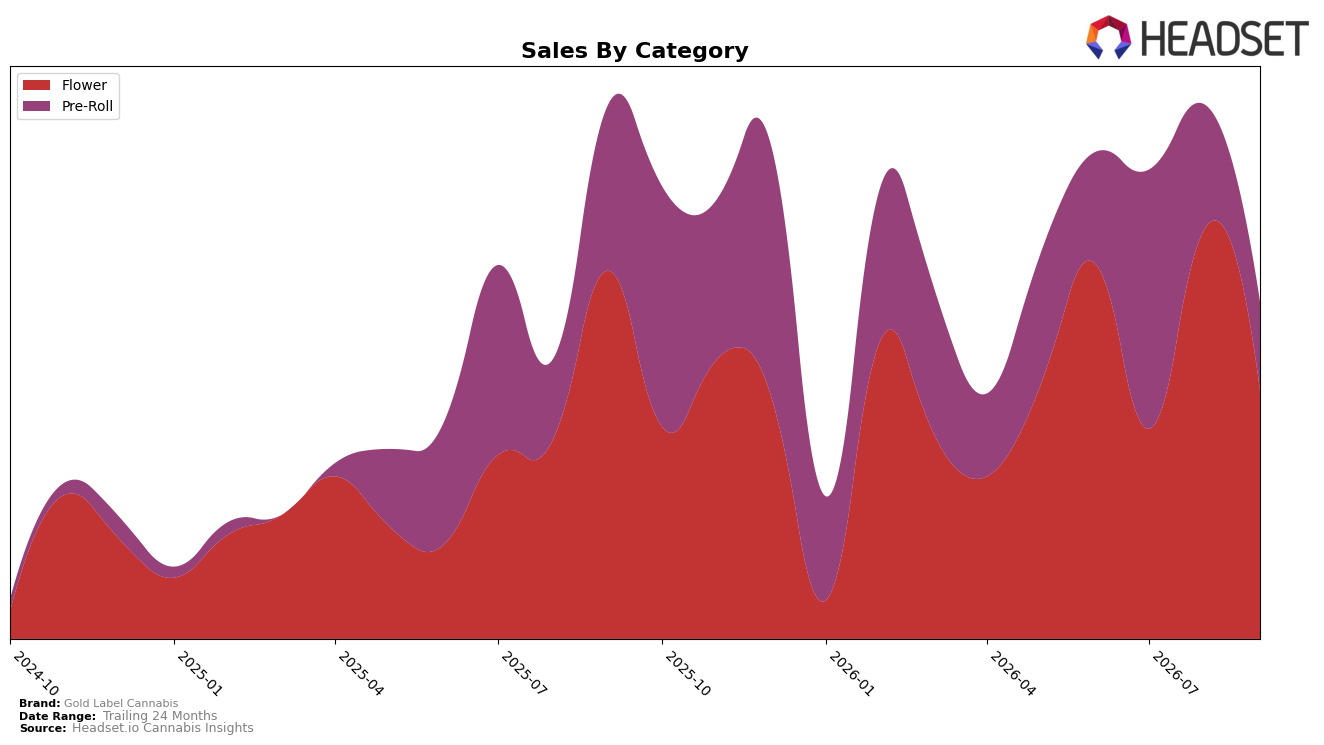
In September 2026, Gold Label Cannabis concentrated 73.51% of sales in Flower and 26.49% in Pre-Roll, with Flower down 32.45% year over year and 39.31% month over month, while Pre-Roll fell 46.27% year over year and 28.31% month over month. Average price rose 15.06% year over year to $17.98, with category price points diverging (Flower at $22.15 vs. Pre-Roll at $11.80), and the brand sat at rank 43 in Colorado Flower. The mix skews toward a higher-ticket Flower core that is contracting faster month to month than Pre-Roll in absolute share terms, implying volume sensitivity at higher price tiers and a need to recalibrate the portfolio to stabilize Flower without over-exposing to a steeper year-over-year decline in Pre-Roll.
The sharper month-over-month contraction in Flower at 39.31% versus 28.31% for Pre-Roll, coupled with a 15.06% year-over-year average price increase, implies price elasticity is eroding unit throughput in the flagship category while mix remains concentrated at 73.51%. Holding rank 43 in Colorado Flower amid a 32.45% year-over-year Flower decline and a brand-level year-over-year sales drop of 36.76% indicates positioning pressure centered on Flower pricing and pack architecture rather than category presence alone; the practical path is to defend share in Flower with tighter price-pack ladders while using Pre-Roll’s lower price point to moderate volatility without letting its 46.27% year-over-year decline dictate mix.
Competitive Landscape
Gold Label Cannabis sits at rank #43 in CO Flower for September 2026, slipping 1 position YoY from #42 and falling 8 spots from #35 in June 2026, despite peaking at #34 in August 2026 before a 9-rank pullback; meanwhile, Green Label Cannabis holds #1 with 38.0% YoY sales growth and Good Chemistry Nurseries advanced from #3 to #2 with 45.5% YoY growth, indicating that top-tier momentum is consolidating above Gold Label Cannabis even as Seed & Strain Cannabis Co. slid from #2 to #4 on a -33.5% YoY decline; the pattern suggests Gold Label Cannabis’s brief August 2026 peak was a short-lived spike, and the current downtrend toward the mid-40s implies share is being ceded to faster-advancing leaders rather than converting into sustained rank gains.

Notable Products
Gelato Mintz (3.5g) posted the steepest month-over-month decline at -65.8% and fell to rank 7, while Fuzzy Navel (3.5g) slid -32.3% yet held rank 2. At the top, Cake Tarts (3.5g) dropped -14.3% but stayed at rank 1, and the related Cake Tarts Pre-Roll (1g) was the lone gainer at +19.9% rising to rank 4. With four of the top ten coming from Flower and all Flower SKUs except rank 1 showing double-digit declines of -29.0% to -65.8%, the mix indicates reliance on a few flagship Flower strains while momentum is shifting toward select Pre-Rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

