

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
GRAS Cannabis is stocked at 53 licensed dispensaries across Oklahoma, Arizona, and Alaska, 46 of them in Oklahoma, with the deepest coverage in Tulsa, Oklahoma City, Miami, Enid, and Mustang. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
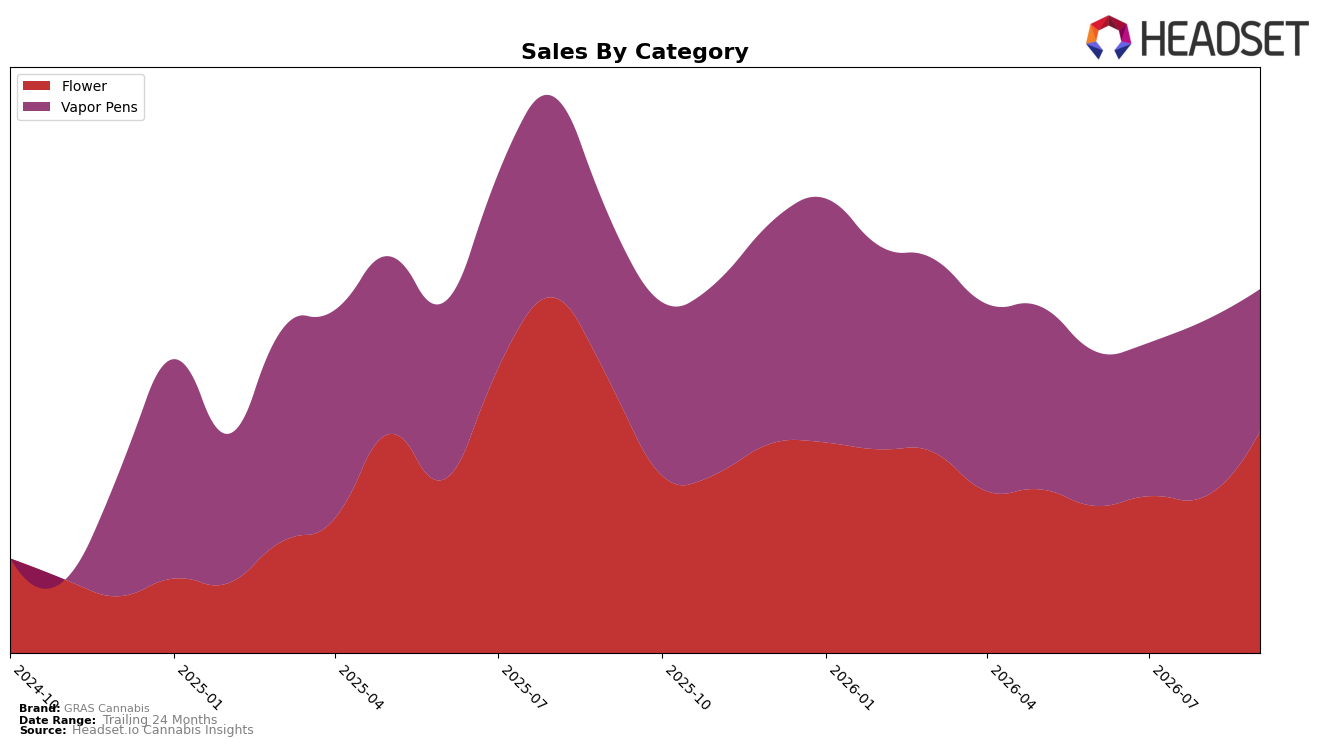
GRAS Cannabis concentrated 60.99% of September 2026 sales in Flower with a 41.83% month-over-month lift, while Vapor Pens held 39.01% share but declined 19.32% month-over-month; both categories were down year-over-year, with Flower at -19.05% and Vapor Pens at -13.69%. The category tilt coincides with a 7.06% lower average price year-over-year to $16.41, and a state-category position of rank 21 in Arizona Flower suggests mid-pack placement; the pattern implies GRAS Cannabis is leaning into Flower volume recovery to counter a brand-level -17.04% year-over-year drop despite weaker year-over-year category comps.
The swing toward Flower month-over-month alongside a concurrent pullback in Vapor Pens indicates a tactical reallocation toward the category where quick share recapture is more feasible, given a 41.83% Flower rebound versus a 19.32% Vapor Pen contraction. With Flower average price at 15.29 and Vapor Pens at 18.53, the mix shift combined with a 7.06% brand-wide price contraction implies a value-forward positioning aimed at defending unit velocity and stabilizing rank 21 in Arizona Flower, positioning GRAS Cannabis to trade mix for near-term share even if it compresses revenue per unit.
Competitive Landscape
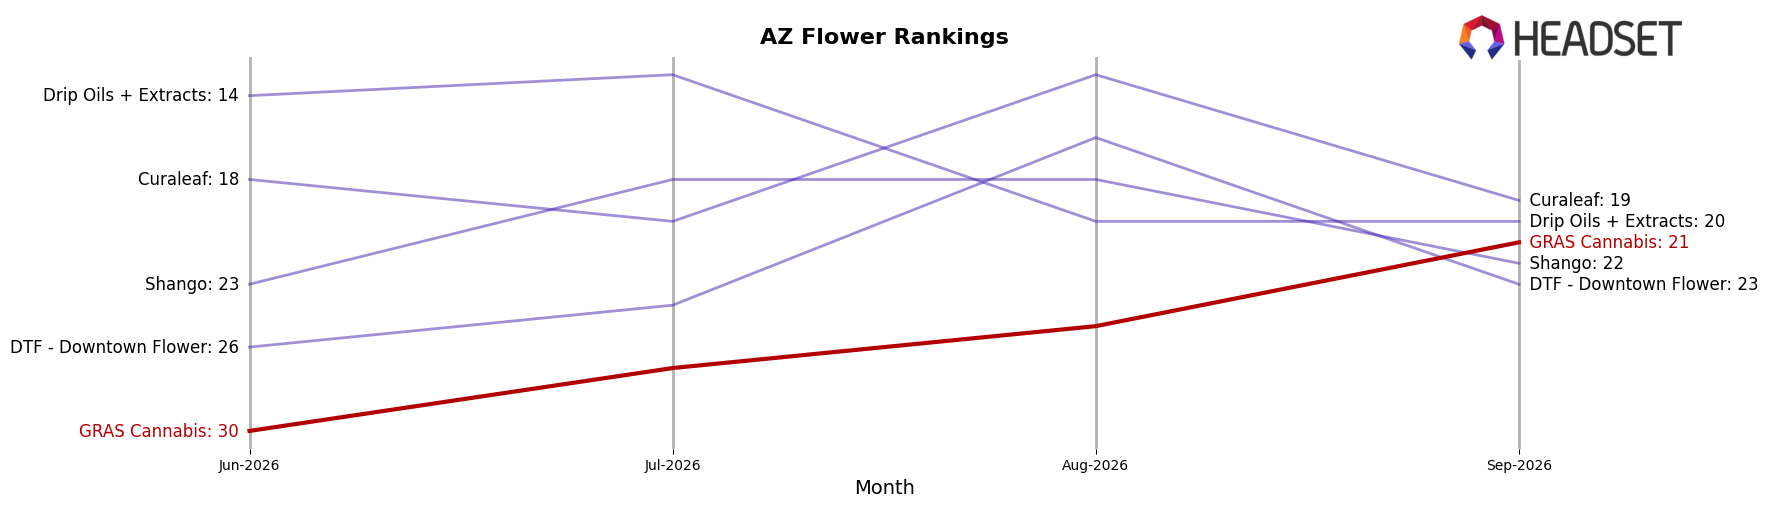
GRAS Cannabis sits at rank 21 in AZ Flower in September 2026, slipping 1 position year over year from rank 20 while improving 9 positions versus June 2026 when it was rank 30; against this backdrop, Find. moved from rank 3 to rank 2 and Loud Pax surged from rank 51 to rank 5, indicating competitive pressure concentrated in the top 5 as GRAS Cannabis remains 5 ranks off its peak of 16 from August 2025, so the flat-to-down YoY rank alongside recent quarter-over-quarter recovery implies mid-tier stability without momentum toward re-entry into the top 15 unless share shifts accelerate.
Notable Products
Strainbow Distillate Disposable (1g) posted the steepest decline in September 2026 at -16.2% MoM while sliding to rank 3, and Lychee Dream Distillate Disposable (1g) fell -30.5% MoM at rank 5, indicating concentrated pressure within disposables despite Golden Pineapple Distillate Disposable (1g) holding rank 2 with a smaller -7.6% MoM dip. Five of the top ten are Vapor Pens, yet four of those pen SKUs dropped between -13.0% and -30.5%, whereas Flower anchors the leaderboard with Jealousy (3.5g) at rank 1 and Jealousy (7g) at rank 6, and D2 Cheese (3.5g) up +6.6% MoM at rank 7. The mix signals a pivot toward Flower-led stability while disposable pens face sequential softness, implying GRAS Cannabis should lean into flagship Flower while triaging disposable flavor breadth and price points.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

