

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Brown Bag is stocked at 48 licensed dispensaries across Massachusetts and Arizona, 39 of them in Massachusetts, with the deepest coverage in Boston, Cambridge, Fall River, Great Barrington, and Northampton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
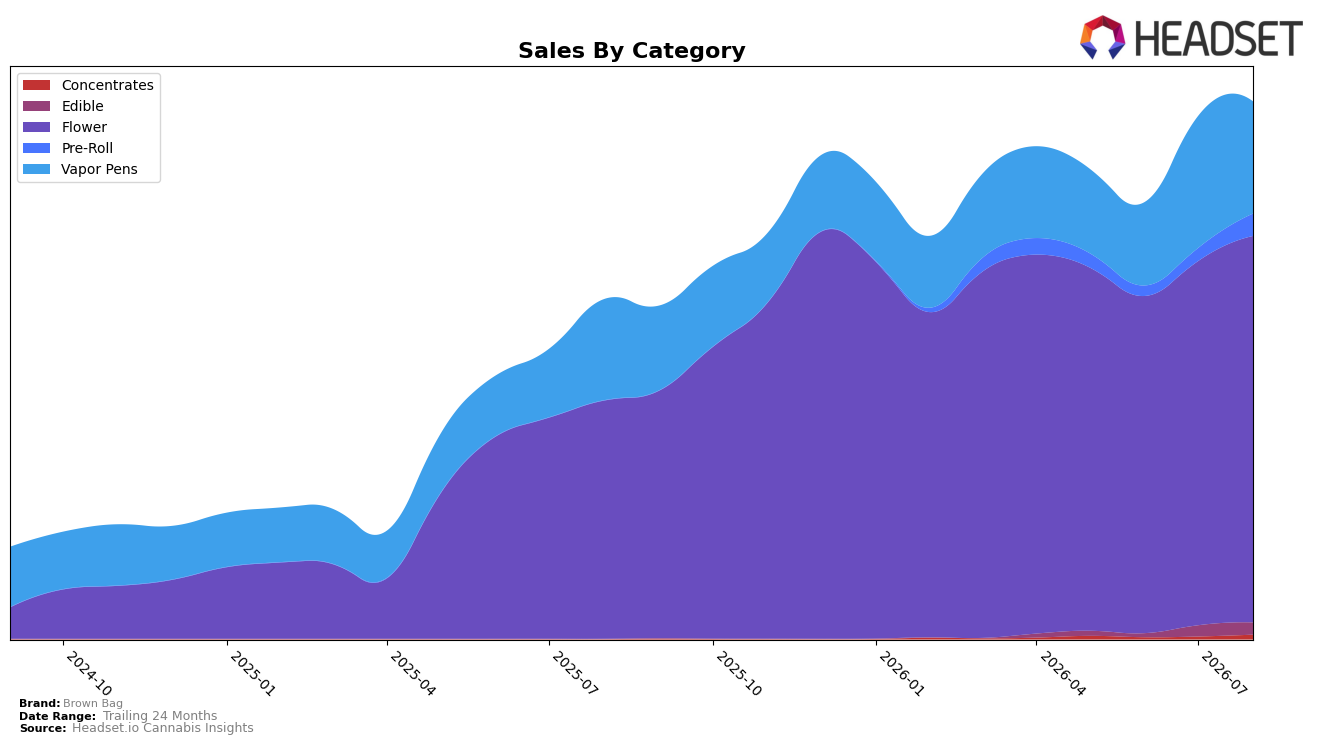
Brown Bag’s category mix in August 2026 was concentrated in Flower at 72.05% share, with Flower sales up 62.37% year over year and 6.11% month over month, while Vapor Pens held 20.77% share with a 10.46% year-over-year increase but a 15.53% month-over-month decline. Smaller lines shifted abruptly: Pre-Roll expanded 74.02% month over month to 4.13% share, Concentrates rose 70.31% month over month to 0.85% share, and Edible grew 8.90% month over month to 2.21% share, alongside a 44.77% year-over-year drop in average price that lowered the portfolio’s ticket. The pattern implies Brown Bag is using price to amplify Flower-led scale while pivoting incremental volume into Pre-Roll and Concentrates to diversify mix without diluting the core.
With Flower ranked 4 in Arizona and growing 62.37% year over year against a 6.11% month-over-month uptick, Brown Bag’s position is anchored in high-velocity Flower while Vapor Pens’ 15.53% month-over-month pullback signals selective retreat from slower-moving SKUs. The 74.02% month-over-month surge in Pre-Roll and 70.31% in Concentrates indicate a tactical expansion into lower-price and higher-potency occasions, supported by a 44.77% year-over-year reduction in average price that widens accessibility. The implication is a barbell positioning: defend a top-5 Flower seat through price-enabled throughput while seeding adjacency gains in Pre-Roll and Concentrates to hedge Vapor Pens volatility.
Competitive Landscape
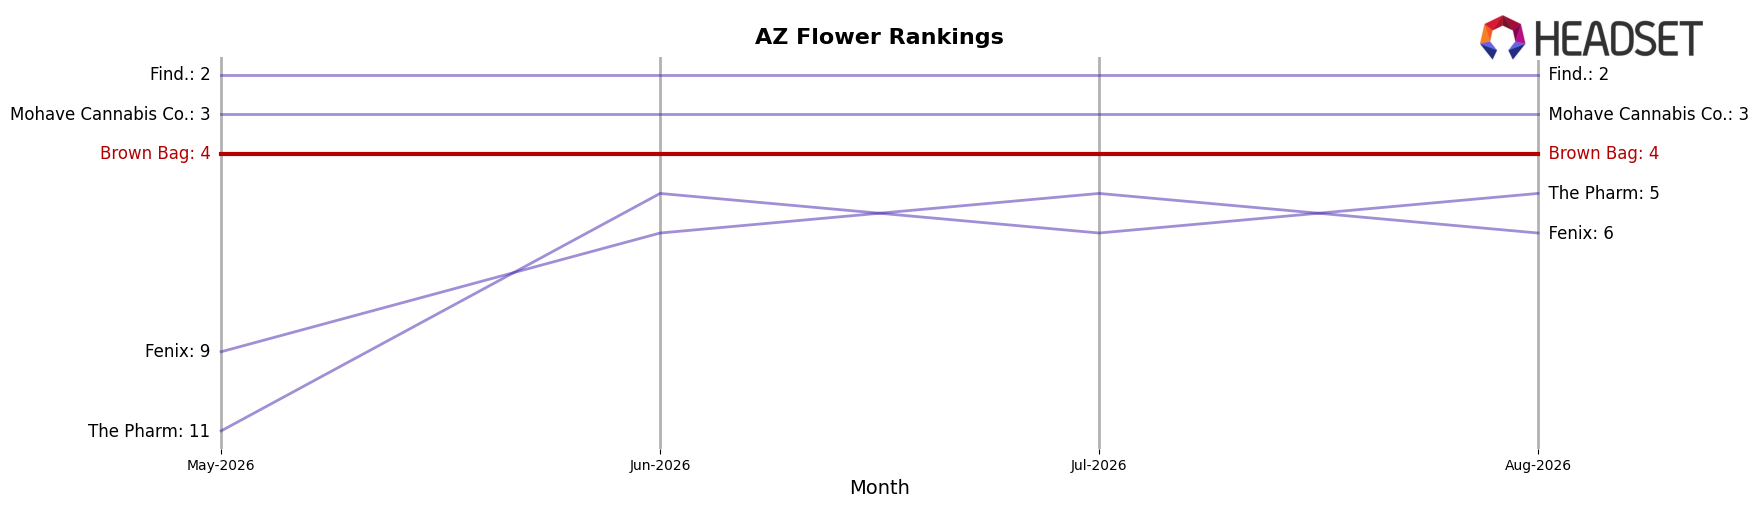
Brown Bag is ranked #4 in Arizona Flower in August 2026, unchanged from #4 year over year, and it also held #4 three months ago while previously peaking at #3 in April 2026; meanwhile, Just Flower held #1 both this year and last year and Find. climbed from #3 to #2 as Mohave Cannabis Co. slipped from #2 to #3. Competitor momentum is uneven, with The Pharm jumping from #21 to #5 on 290.0% year-over-year sales growth while Mohave Cannabis Co. advanced just 12.7% YoY and Find. expanded 40.2% YoY; Brown Bag’s flat rank suggests it is defending share against faster risers but not converting that defense into an upward move. The pattern implies a stall: without a catalyst to reverse the April 2026 slippage from #3 to a sustained #4, Brown Bag is likely to be boxed in by rising entrants and incremental gains from Find..
Notable Products
Illuminati Pre-Roll (1g) is the only top-10 SKU with a measured month-over-month change in August 2026, up 11.1% while holding rank 3, which contrasts with the flat or unreported MoM across the rest of the leaderboard and implies momentum is concentrated in a single Pre-Roll rather than broad-based. Ozark Hash (3.5g) sits at rank 1 and Pineapple Planet (3.5g) at rank 7, anchoring a Flower-heavy slate where five of the top ten are Flower SKUs, indicating category concentration even as Pre-Rolls occupy ranks 2, 3, 4, and 6. The presence of Pineapple Pakalolo Distillate Cartridge (1g) at rank 8 alongside Flower dominance shows limited diversification into Vapor Pens despite $43,762 in August 2026 sales. The pattern suggests Brown Bag is leaning into core Flower while selectively testing Pre-Roll-driven velocity, pointing to a commercial direction that prioritizes depth in Flower with targeted bets in ready-to-use formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

