

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Green Meadows is stocked at 25 licensed dispensaries across Massachusetts, with the deepest coverage in Worcester, Boston, Haverhill, Chicopee, and Clinton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
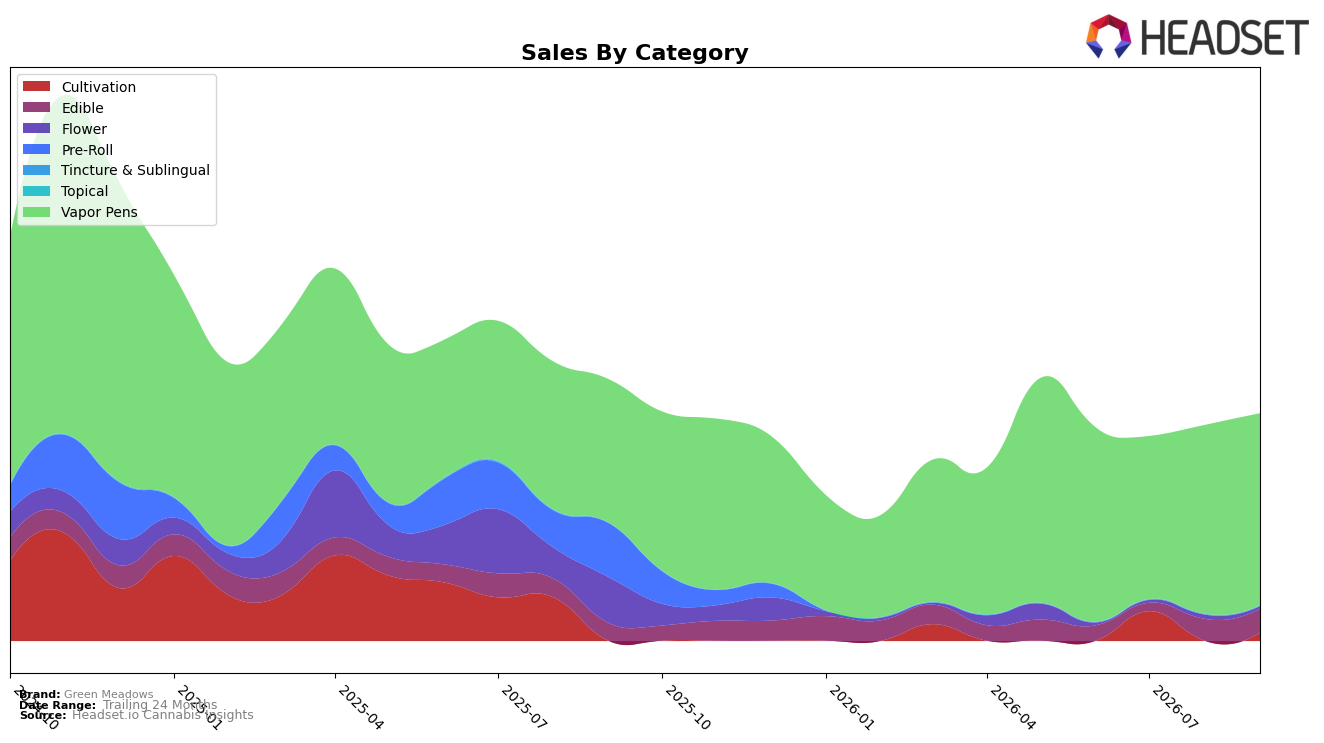
In September 2026, Green Meadows concentrated 88.20% of sales in Vapor Pens with a 1.72% month-over-month uptick and 34.00% year-over-year lift, while Edible held 10.75% share with an 8.13% MoM gain and 31.74% YoY growth; Flower shrank to 1.05% share with a -41.75% MoM slide and a -94.98% YoY contraction. Despite a brand-level YoY sales decline of 16.42% and a 162.08% YoY jump in average price to $31.82, the mix shows concentration into higher-priced inhalables alongside a small but faster-growing Edible pocket; the pattern implies reliance on one category for volume recovery and price-led revenue defense even as legacy Flower volumes retrench.
With Vapor Pens anchoring category presence yet sitting at rank 37 in Massachusetts, the 34.00% YoY category growth and 1.72% MoM rise point to share maintenance via depth rather than breadth, while Edible’s 8.13% MoM and 31.74% YoY gains create a secondary lane for basket diversification. Given Flower’s -94.98% YoY collapse and -41.75% MoM decline, the shift implies a positioning pivot toward higher-price-per-unit formats to offset unit softness, with September 2026 mix concentration increasing exposure to Vapor Pen rank volatility and suggesting that incremental Edible expansion is the most pragmatic hedge.
Competitive Landscape
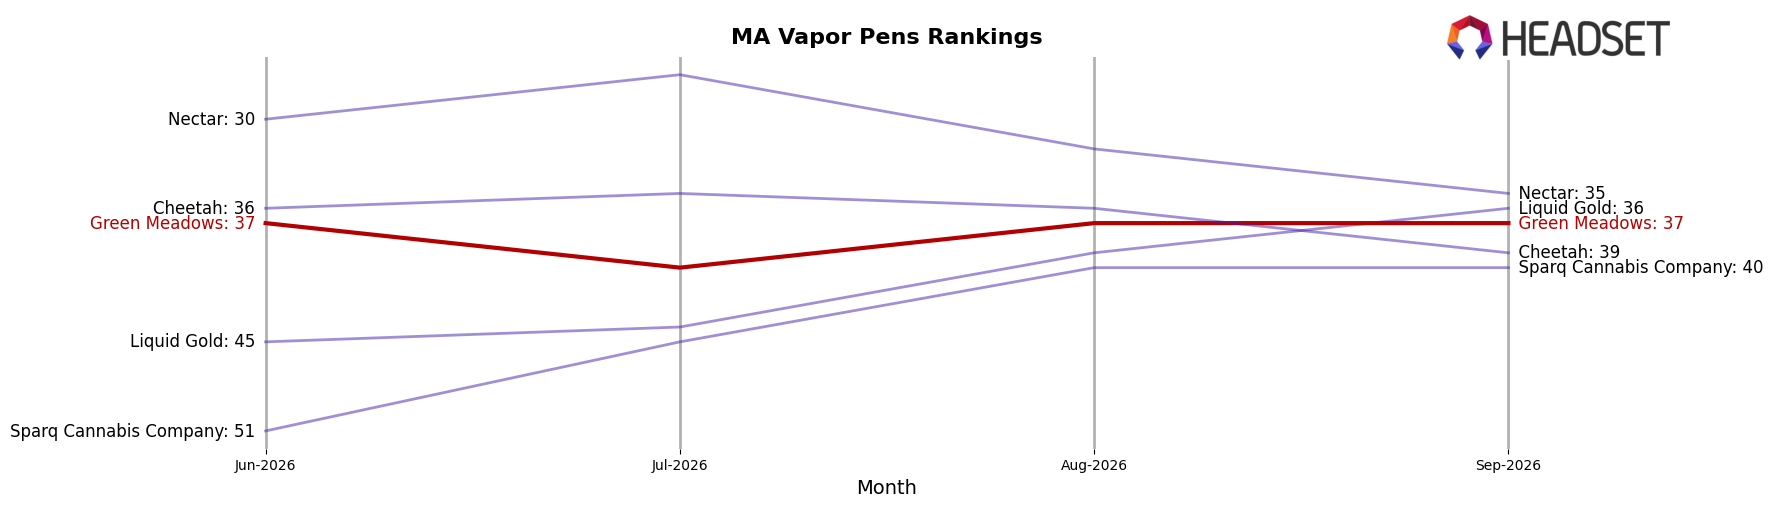
Green Meadows sits at rank #37 in MA Vapor Pens in September 2026, up 4 positions year over year from #41, yet still 15 spots below its peak at #22 in November 2024; versus the top of the market, Fernway held #1 with 0 rank movement while Jeeter surged from #23 to #4 alongside a 421.5% YoY sales increase, indicating competitive momentum concentrating at the top and mid-tier displacement. With Green Meadows flat at #37 for three months and competitors like Dime Industries improving from #6 to #5 on 63.0% YoY sales growth while Select stayed at #2 despite an 11.7% decline, the pattern implies Green Meadows’ modest rank gain is driven more by churn above it than by its own acceleration, suggesting limited near-term upward mobility without share-taking moves.
Notable Products
The Tank - Northern Lights Distillate Disposable (1g) posted the largest movement in September 2026 with a 101.7% month-over-month surge, climbing into rank 5 while The Tank - Granddaddy Purple Distillate Disposable (1g) fell 13.9% to rank 6. The Tank - Apricot Delight Distillate Disposable (1g) gained 82.6% to take rank 1, while The Tank - Super Lemon Haze Distillate Disposable (1g) rose 16.0% at rank 2 and The Tank - Blue Dream Distillate Disposable (1g) added 11.0% at rank 3. Four of the top five are Vapor Pens, indicating consolidation at the premium end despite The Tank - Mango GMO Distillate Disposable (1g) sliding 24.4% at rank 7 and Edibles like Dream Watermelon Gummies 20-Pack (100mg) holding nearly flat at -1.0% around rank 8 with approximately $7.2k in sales. The pattern implies Green Meadows is concentrating volume in a narrower set of high-velocity pens while allowing slower pen SKUs and steady Edibles to play a supporting role.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

