

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Halara is stocked at 185 licensed dispensaries across California, New York, and Washington, 160 of them in California, with the deepest coverage in San Francisco, San Jose, Sacramento, San Diego, and Santa Rosa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
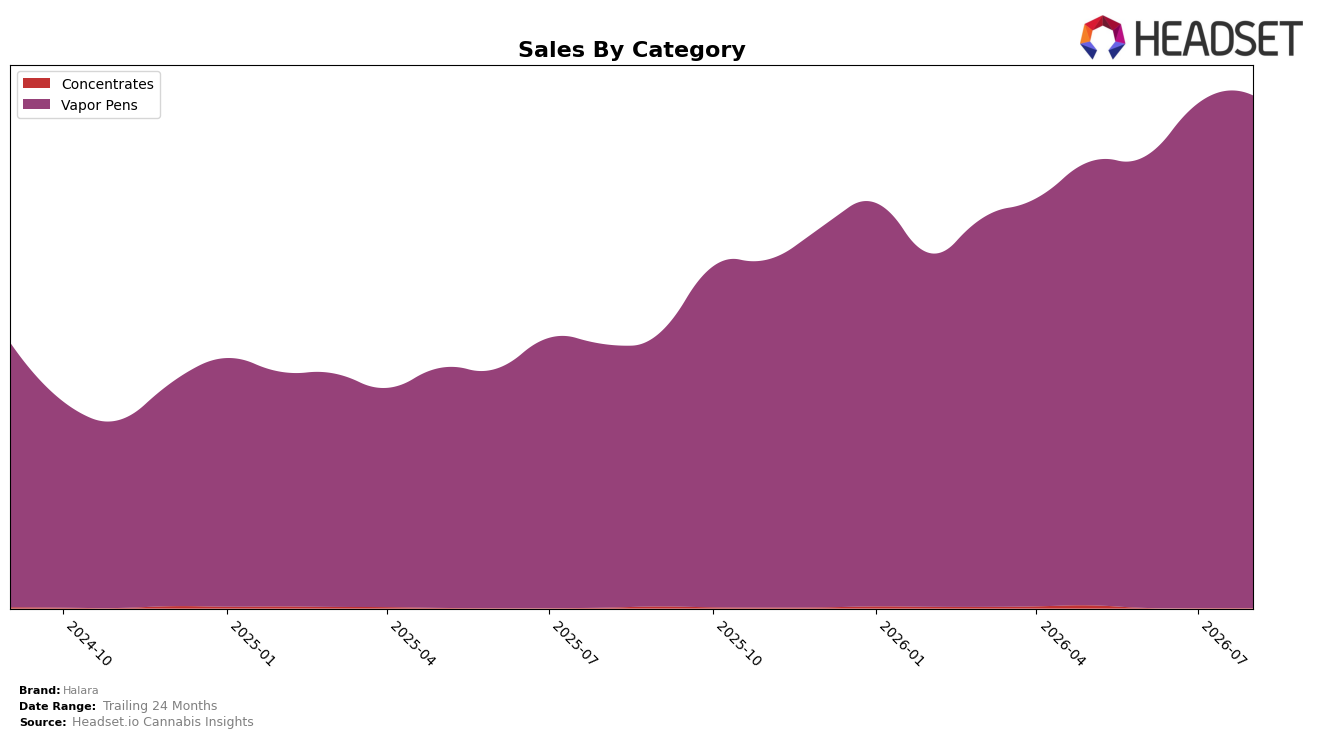
In August 2026, Halara was 100.0% concentrated in Vapor Pens, with category sales up 94.66% year over year and 1.48% month over month, while brand-wide sales rose 94.32% YoY and averaged a 74.65% increase over 24 months. The average price fell 9.29% YoY to $23.91 alongside a category share fixed at 100.0%, and the brand held rank 26 in Vapor Pens in California. The pattern implies growth is being driven almost entirely by a single-category bet where unit velocity is likely carrying gains as prices compress.
The 100.0% category dependency paired with a 1.48% MoM uptick and a 94.66% YoY surge indicates Halara is leaning into price-elastic demand rather than mix diversification, with rank 26 in California suggesting mid-pack visibility rather than top-decile penetration. The 9.29% YoY price decline alongside a 94.32% brand-level sales increase points to volume-led expansion, so positioning is skewing toward value within Vapor Pens rather than premium segmentation. The implication is that sustaining share will rely on maintaining lower price points or introducing sub-tiered offerings within Vapor Pens, because the absence of cross-category ballast raises exposure to any category-specific slowdown.
Competitive Landscape
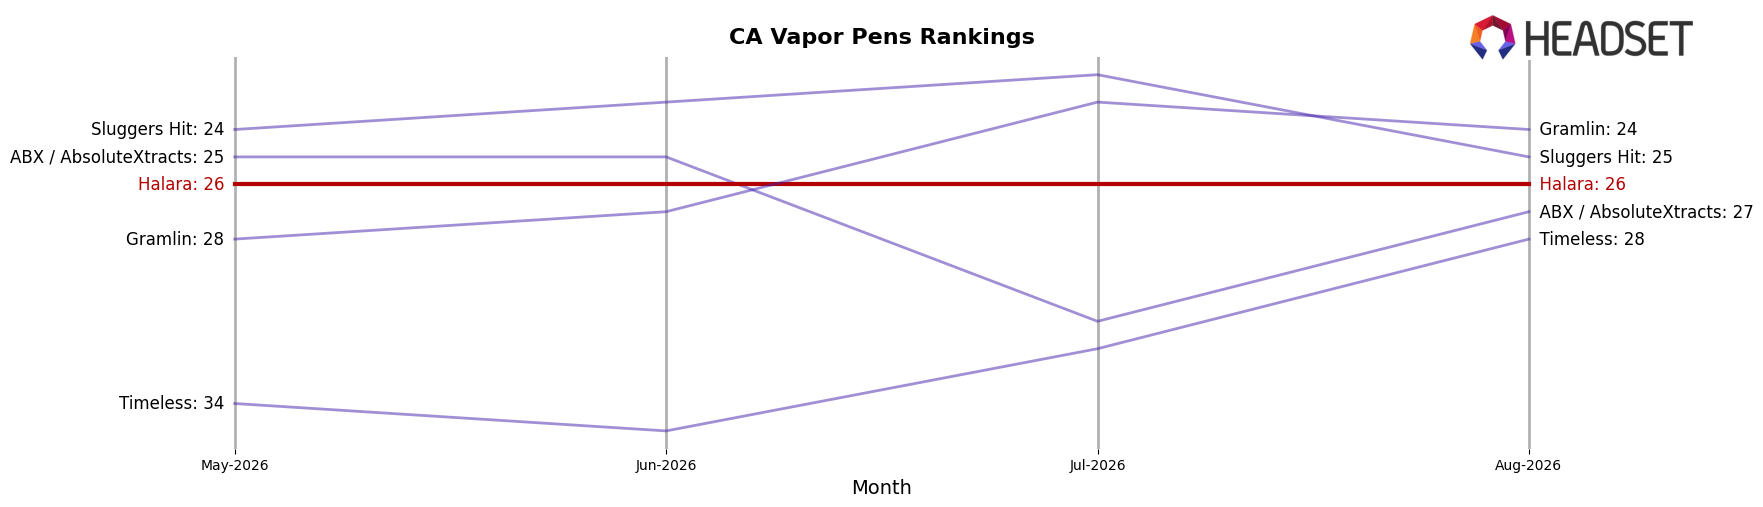
Halara sits at rank #26 in California Vapor Pens in August 2026, improving 10 positions year over year from #36, while holding flat versus May 2026 to August 2026 at #26; meanwhile, category leaders moved unevenly as STIIIZY held #1 with a -10.6% YoY sales change and Jetty Extracts climbed from #4 to #3 with +40.6% YoY sales growth. Compared with Plug Play, which slipped from #3 to #4 and declined -14.1% YoY, and Raw Garden steady at #2 with -0.2% YoY, Halara’s 10-rank YoY gain to a new peak rank in August 2026 implies share capture from mid-tier incumbents but limited near-term momentum beyond the mid-20s without a catalyst to break past the #25 barrier.
Notable Products
Apricot Octane Distillate Disposable (1g) posted the steepest movement in August 2026 with a -21.2% month-over-month decline while sitting at rank 10, contrasting with Grand Daddy Purple Live Resin Disposable (1g) at rank 1 with a +23.3% increase. Grand Daddy Purple Live Resin Disposable (1g) extended its lead over rank-2 Maui Wowie High THC Distillate Cartridge (1g) by 14.5 percentage points of MoM growth (23.3% vs 8.7%) while maintaining a dollar gap of $7,0xx. With eight of the top ten SKUs in Vapor Pens occupied by disposables and cartridges from the same family lines, mid-pack volatility includes Pineapple Express Distillate Disposable (1g) at rank 4 with +19.3% against Blue Dream Live Diamond Sauce Cartridge (1g) at rank 7 with -10.0%. The pattern implies mix is tilting toward live resin-led hero SKUs and away from weaker distillate extensions, concentrating share in a few fast-advancing flagships.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

