


Where to Buy
High Noon Cultivation is stocked at 84 licensed dispensaries across Oregon and New Mexico, 74 of them in Oregon, with the deepest coverage in Portland, Eugene, Salem, Bend, and Ontario. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
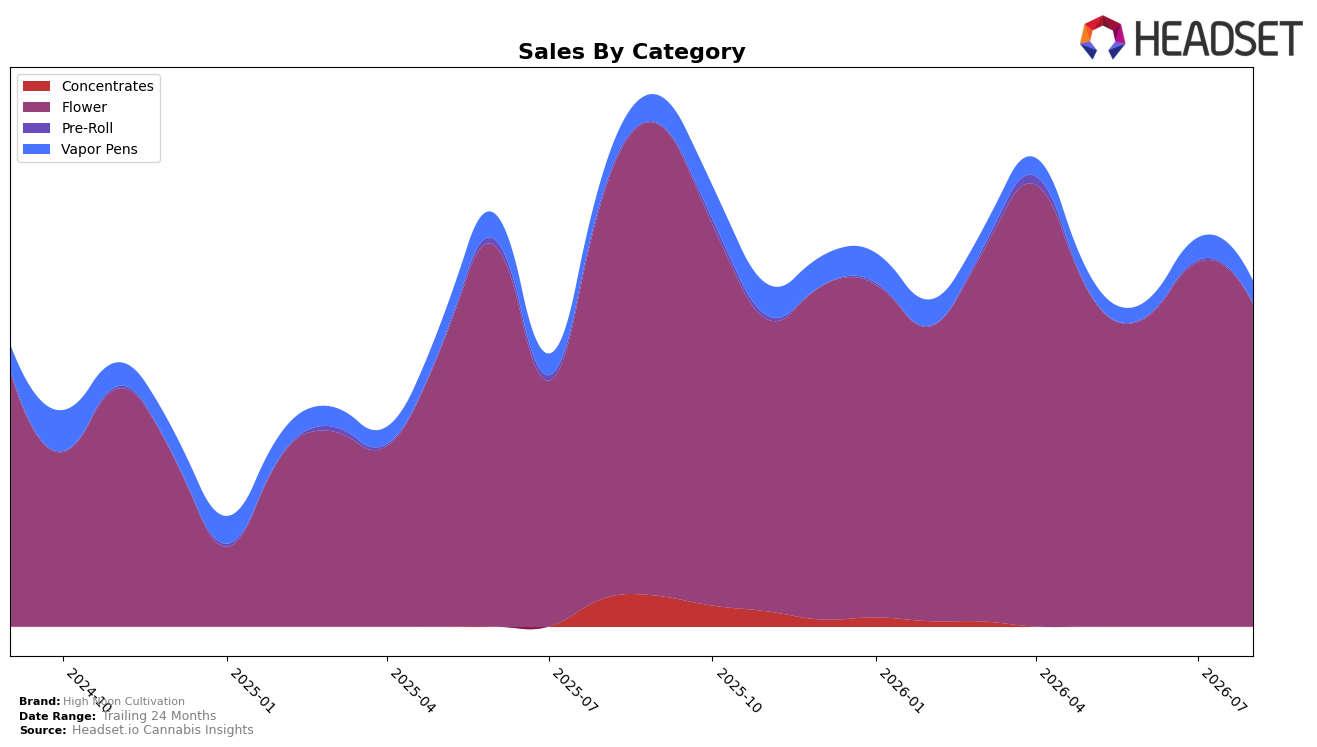
High Noon Cultivation’s mix in Oregon remains dominated by Flower at 93.45% share, but Flower sales fell 20.41% year over year and 11.57% month over month in August 2026, while average brand pricing declined 6.22% YoY. Vapor Pens, at 6.34% share, grew 11.33% YoY despite a 1.34% MoM dip, and Pre-Roll contracted to 0.21% share with a 78.43% YoY and 55.37% MoM drop. With Flower ranked 41st in the state category rankings and total brand sales down 24.39% YoY, the pattern implies an overexposure to a weakening core segment that is dragging overall performance despite a small, growing Vapor Pens foothold.
The shift—shrinking Flower (−20.41% YoY; −11.57% MoM) alongside expanding Vapor Pens (+11.33% YoY; −1.34% MoM)—implies a need to rebalance toward faster-moving inhalables where price elasticity can be used more effectively than in commoditizing Flower. Given the 41 rank position in Oregon Flower and the 28.16% 24‑month sales decline, prioritizing differentiated formats and pack-price architectures in Vapor Pens while stabilizing Flower price ladders could lift share efficiency; otherwise the current 93.45% Flower dependency is likely to keep depressing aggregate momentum as Pre-Roll remains subscale (0.21% share with sharp double‑digit MoM decline).
Competitive Landscape
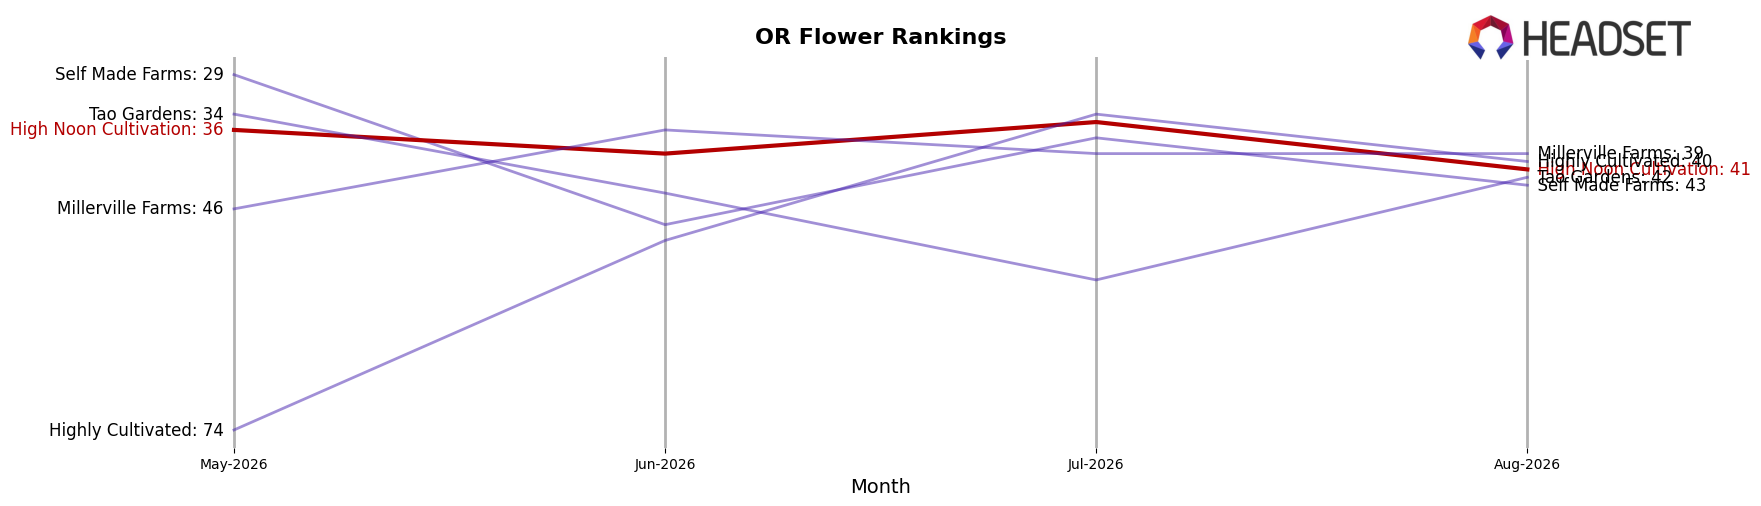
High Noon Cultivation ranks #41 in OR Flower in August 2026, falling 14 positions year over year from #27 and slipping 5 ranks from May 2026’s #36, while still trailing its peak at #23 from September 2025; meanwhile, Grown Rogue sits at #1 after rising from #3 with 49.1% year-over-year sales growth, and Oregrown climbed from #23 to #3 with 182.4% growth, indicating that High Noon Cultivation’s relative decline is more about competitor acceleration than category contraction. Compared with PRUF Cultivar / PRŪF Cultivar sliding from #1 to #2 alongside a 17.2% sales decrease and Panda Farms jumping 99 ranks to #4 with 1,059.6% growth, the brand’s move from #27 to #41 suggests lost share of velocity as faster-moving peers gain distribution and basket share; the trajectory implies that without a rank recovery toward the September 2025 peak, High Noon Cultivation risks entrenchment in the mid-40s as momentum clusters in the top five.
Notable Products
Tropical Infusion (1g) posted the largest month-over-month surge in August 2026 at +123.4% and climbed into a tie at rank 4, while Blueberry Motor Oil (3.5g) also advanced with +56.6% at rank 4. In contrast, Fresh Powder (Bulk) fell -73.2% to rank 2 and Wabi Sabi Burger (Bulk) declined -51.0% at rank 3, and Hush Money (Bulk) slipped -1.1% but still held rank 1 with roughly $36,398. With at least four of the top ten coming from the Tropical Infusion family across 1g, 3.5g, and Bulk, mix is consolidating around a single strain line even as bulk formats retrench, implying a pivot toward smaller-pack Flower velocity where price points and trial are driving the leaderboard.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

