

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
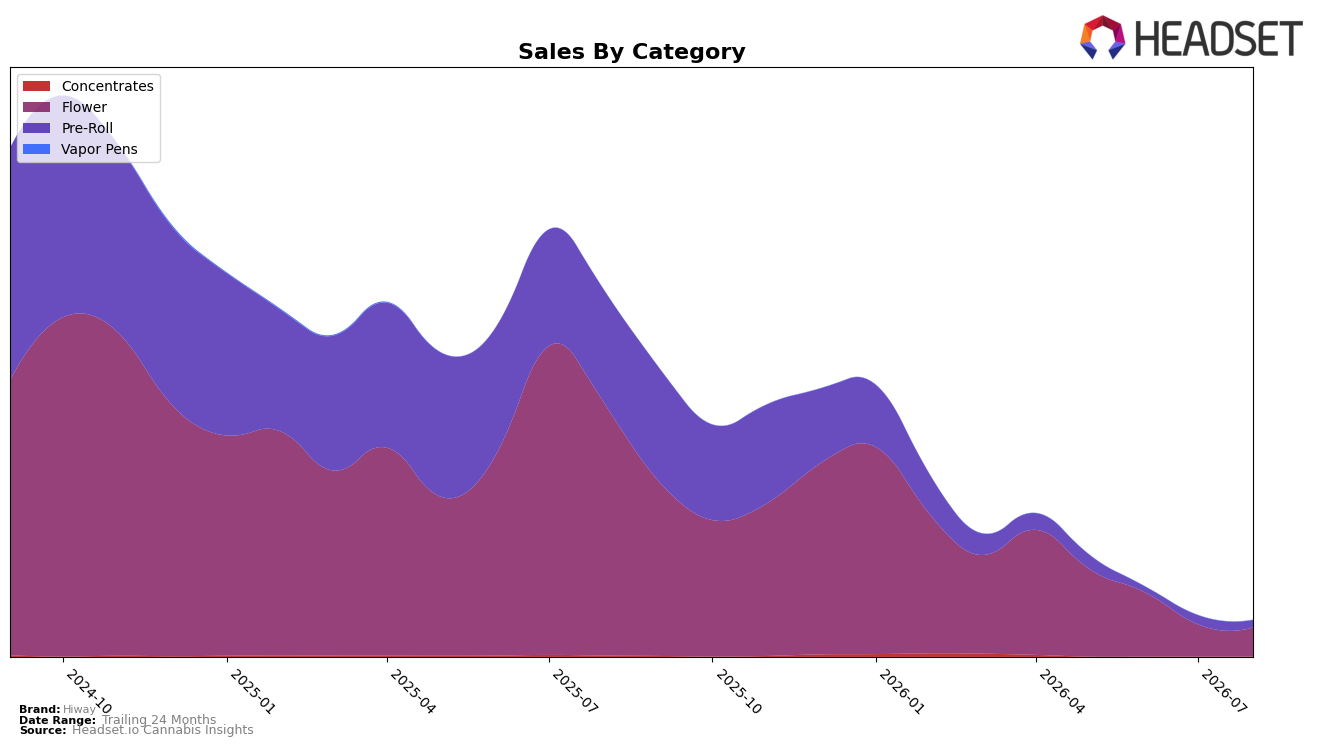
Hiway concentrated 79.88% share in Flower and 20.12% in Pre-Roll in August 2026, with Flower down 88.58% year over year and 9.71% month over month, while Pre-Roll fell 93.55% year over year and 18.71% month over month. Average price rose 26.73% year over year to $30.94, alongside a category-level average of $64.02 in Flower and $10.14 in Pre-Roll, indicating mix and pricing shifts that did not offset the overall 90.14% brand sales decline year over year. The combined pattern — Flower holding a near-80% mix amid steeper Pre-Roll contraction and double-digit month-over-month declines in both categories — implies Hiway is anchored to a shrinking core where price escalation and reduced Pre-Roll velocity limit recovery potential.
Hiway’s Flower weight aligns with a provincial footprint led by AB, yet the brand’s Flower rank at 45 in Saskatchewan and a 9.71% month-over-month decline in Flower versus an 18.71% decline in Pre-Roll suggest positioning that is defensive rather than acquisitive within core inhalables. With category mix stability (79.88% vs. 20.12%) but outsized year-over-year contractions of 88.58% in Flower and 93.55% in Pre-Roll, the brand is positioned as a value-sensitive Flower player whose price increases and limited Pre-Roll breadth constrain trade-up and cross-category capture.
Competitive Landscape
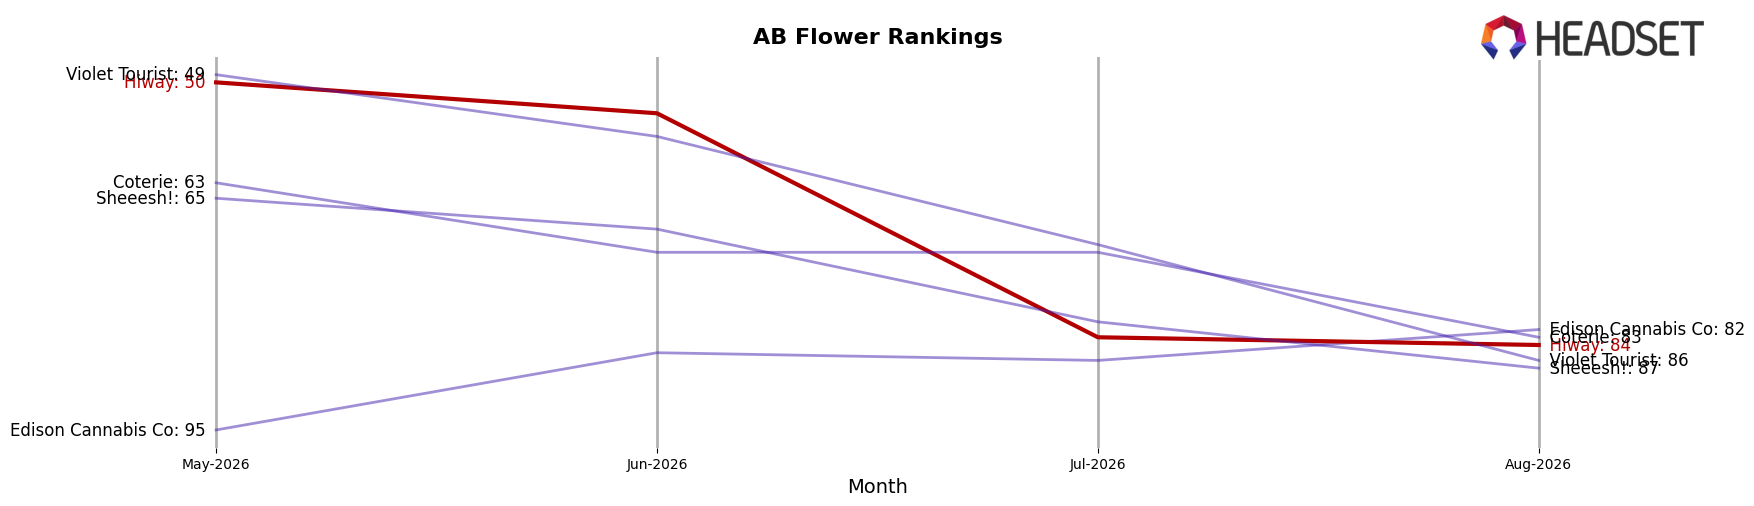
Hiway sits at rank #84 in AB Flower in August 2026, sliding 30 positions year over year from #54 while also dropping 34 spots from its three-month reference at #50; the brand’s peak of #17 in January 2026 underscores a 67-place fall from peak to current. In contrast, FIGR climbed from #10 to #1 with 182.39% YoY sales growth, and Spinach moved from #5 to #2 alongside 17.55% YoY growth, whereas Back Forty / Back 40 Cannabis rose from #6 to #3 despite a -8.31% YoY sales change—together indicating that Hiway’s relative decline is driven more by share reallocation and rank compression at the top than by category contraction. The rank trajectory implies that Hiway must counter accelerating leader gains and mid-tier ascents to avoid further down-tier migration in the next two quarters.
Notable Products
Indica Ice Water Hash Infused Pre-Roll 3-Pack (1.5g) posted the steepest decline at -74.24% and slid to rank 9, while Sativa Pre-Roll 2-Pack (2g) held rank 1 despite a -6.71% dip; this contrast implies infused pre-rolls lost traction even as value pre-rolls maintained the lead. Slow Lane Indica (3.5g) fell -47.41% to rank 4 and Fast Lane Sativa (28g) dropped -11.89% to rank 5, and six of the top ten SKUs are Flower formats, indicating the lineup remains concentrated in larger Flower sizes despite mixed momentum.
Sativa Pre-Roll 2-Pack (2g) at rank 1 alongside Indica Pre-Roll 2-Pack (2g) at rank 3 with a -32.18% decline signals bifurcation within the Pre-Roll family, while Fast Lane Sativa (3.5g) in rank 8 eked out +5.58% month over month against broader Flower pullbacks; the combined pattern points to a pivot toward price-accessible core SKUs and away from premium or specialty variants in August 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

