

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Lift Tickets is stocked at 100 licensed dispensaries across California, Vermont, and 2 other states, 94 of them in California, with the deepest coverage in Los Angeles, Sacramento, San Diego, La Mesa, and Lompoc. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
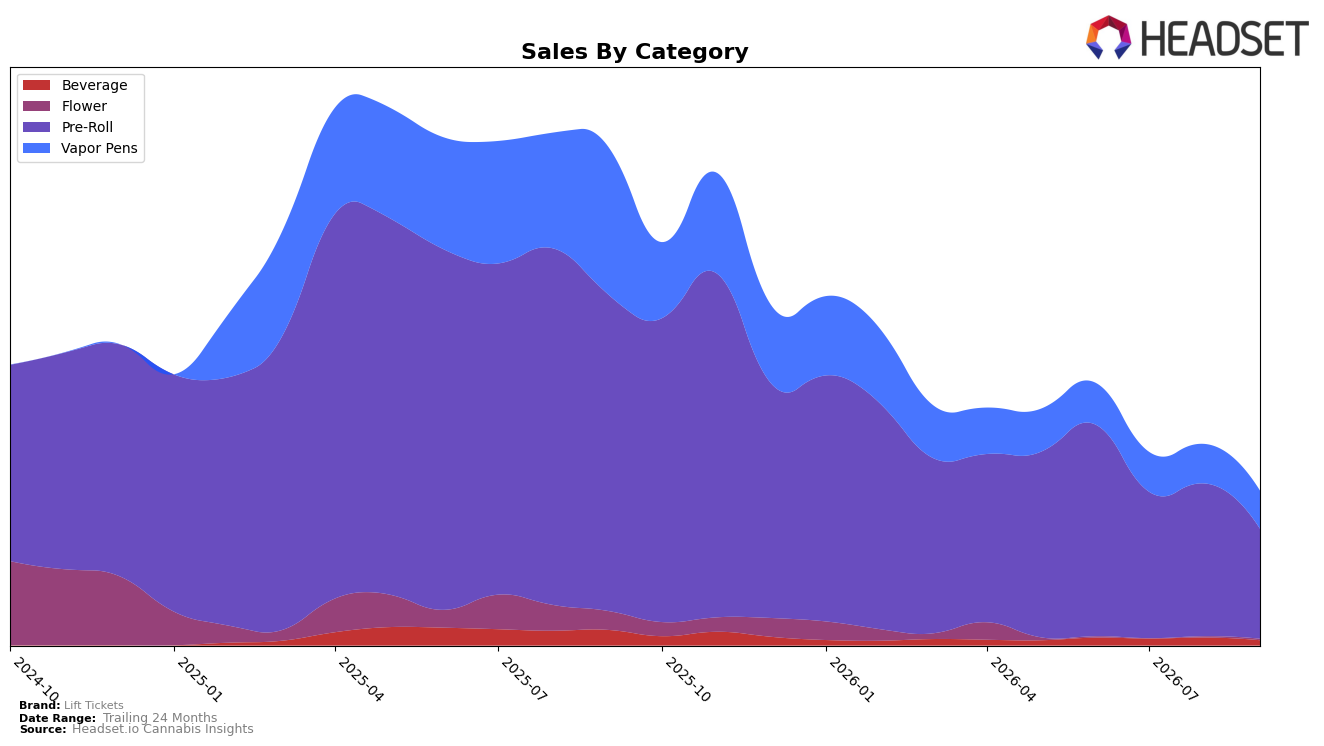
In September 2026, Lift Tickets concentrated 71.36% of sales in Pre-Roll with a year-over-year decline of 65.35% and a month-over-month drop of 28.09%, while Vapor Pens held 24.62% share with a 74.35% YoY decrease and a 3.51% MoM decrease. Beverage accounted for 3.27% share with a 67.25% YoY decline and a 35.28% MoM decline, and Flower sat at 0.75% share despite a 27.39% MoM uptick after a 93.80% YoY contraction. With average prices down 3.82% YoY to $23.96 and Pre-Roll average price at $26.66 versus Vapor Pens at $25.70, the mix signals reliance on a shrinking Pre-Roll base and limited offset from Vapor Pens, implying category concentration risk intensifying as MoM softness deepens in September 2026.
The widening gap between Pre-Roll’s steep MoM decline of 28.09% and Vapor Pens’ milder 3.51% MoM decline suggests substitution risk away from the core rather than broad demand stability, while Beverage’s 35.28% MoM fall removes a potential cushion and Flower’s 27.39% MoM rebound is too small at 0.75% share to shift outcomes. Given total brand sales fell 69.14% YoY with a 44.50% decline over 24 months, the September 2026 mix points to erosion of flagship positioning in Pre-Roll and limited diversification traction, implying Lift Tickets must either stabilize Pre-Roll unit velocity at a 71.36% mix or accelerate category rebalancing where month-over-month declines are less severe.
Competitive Landscape
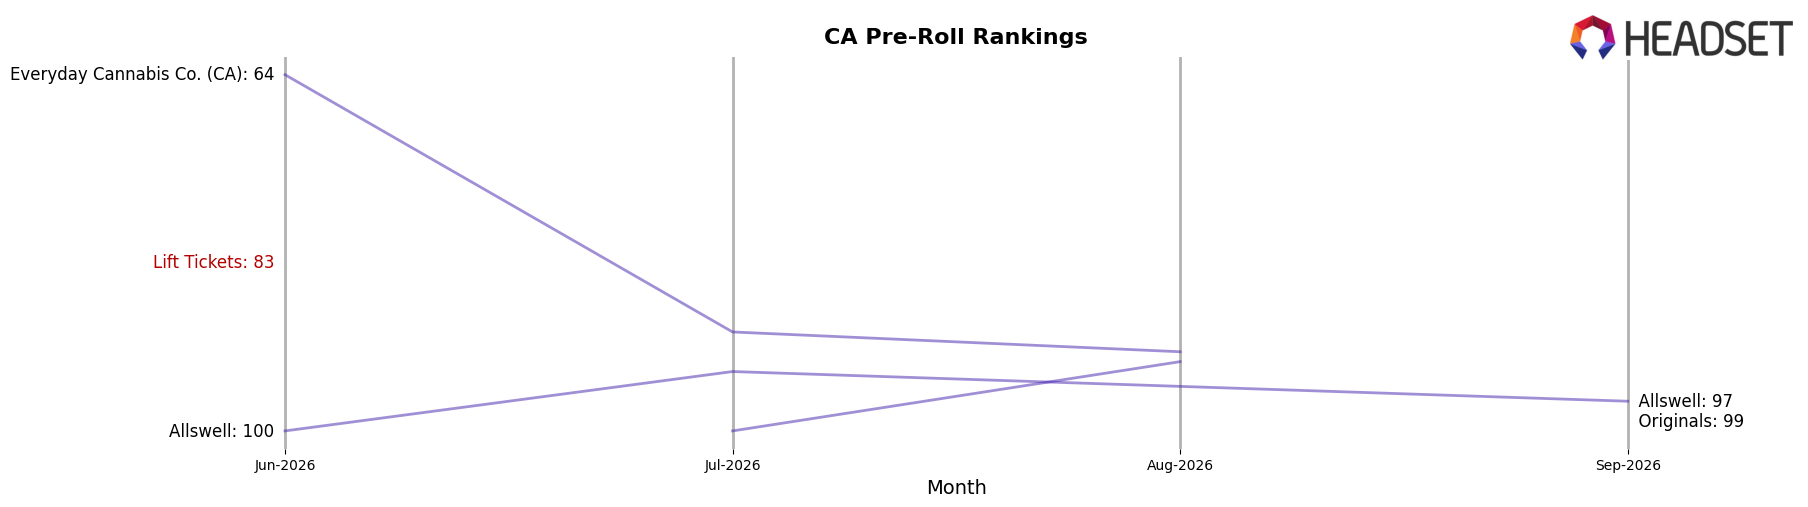
Lift Tickets sits at rank #107 in CA Pre-Roll in September 2026, down 49 places year over year from #58, and 24 places below its June 2026 position of #83; this drop contrasts with Jeeter holding #1 both year over year and currently while growing sales 16.0%, and Claybourne Co. advancing from #6 to #4 with a 19.3% sales increase. The brand is also 59 ranks below its April 2025 peak at #48 and now trails category leaders by over 100 rank positions, while Kingpen remains at #3 despite a 21.7% sales decline; the combination of a multi-quarter slide from #83 to #107 and a long gap from the April 2025 peak implies Lift Tickets is ceding shelf visibility to higher-momentum incumbents and would need double-digit rank recovery to reenter the top 50.
Notable Products
Lights On - THCV/THC 1:2 Kiwi Melon Energy Drink (5mg THCV, 10mg THC, 12oz, 355ml) led the downside with a -52.7% month-over-month drop while holding rank 1, outpacing the -37.6% decline at rank 3 for Jackapulco Infused Pre-Roll 5-Pack (2.5g) in severity. The companion Lights On - THCV/THC 1:2 Kiwi Apple Energy Drink (5mg THCV, 10mg THC, 12oz, 355ml) slipped -9.3% at rank 2, and four of the top ten are Pre-Roll SKUs concentrated between ranks 3 and 7 with additional declines of -28.1% and -24.1% in that block. This pattern indicates Lift Tickets is over-indexed in Pre-Rolls and a nascent Beverage play, and the synchronized drops suggest a need to rebalance assortment and pricing to stabilize rank while protecting the higher-velocity Pre-Roll core despite September 2026 volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

