

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Loosies is stocked at 186 licensed dispensaries across Michigan, New Jersey, and 3 other states, 170 of them in Michigan, with the deepest coverage in New Buffalo, Detroit, Monroe, Flint, and Battle Creek. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
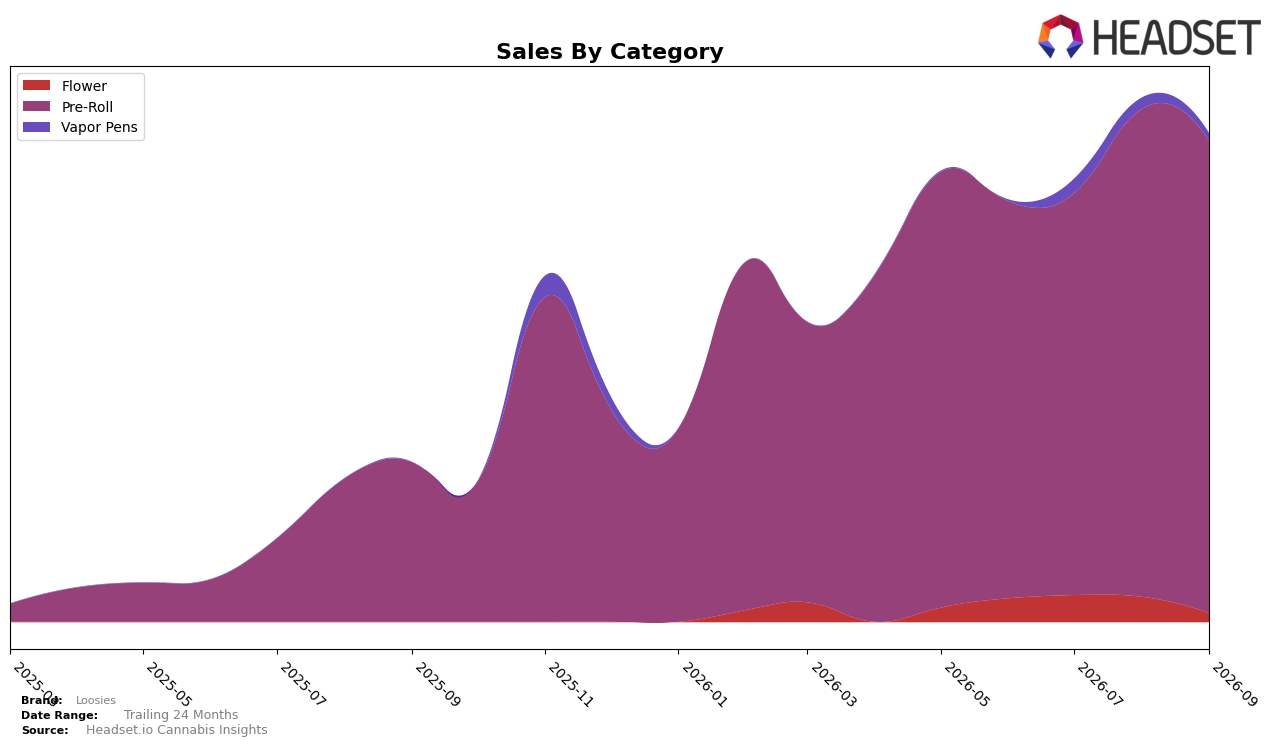
Loosies concentrated 96.66% of September 2026 sales in Pre-Roll while Flower and Vapor Pens held 1.78% and 1.56% respectively, indicating a narrow mix anchored to one format. Within Pre-Roll, year-over-year growth of 196.00% paired with a month-over-month decline of 3.29% points to rapid annual scale tempered by a recent pullback, while Flower fell 65.33% MoM and Vapor Pens dropped 31.37% MoM from small bases. The brand’s overall sales grew 206.24% year over year alongside an 81.48% YoY drop in average price, implying that volume expansion, not pricing, drove the gains; the combination of triple-digit YoY growth and a mid-20s rank position in Michigan Pre-Roll at rank 22 suggests headroom exists but is contingent on stabilizing mix breadth and recent MoM softness.
The mix tilt and pricing shift imply Loosies is competing as a value-forward Pre-Roll specialist rather than a multi-category player, given 96.66% share in Pre-Roll and an 81.48% YoY average price compression. With Pre-Roll down 3.29% MoM and the minor categories contracting 65.33% and 31.37% MoM respectively, the current setup prioritizes scale and throughput over margin diversity; holding rank 22 in Michigan Pre-Roll suggests that incremental share gains will most likely come from sustained volume at low price points or selective premiumization within Pre-Roll, not from immediate expansion in Flower or Vapor Pens.
Competitive Landscape
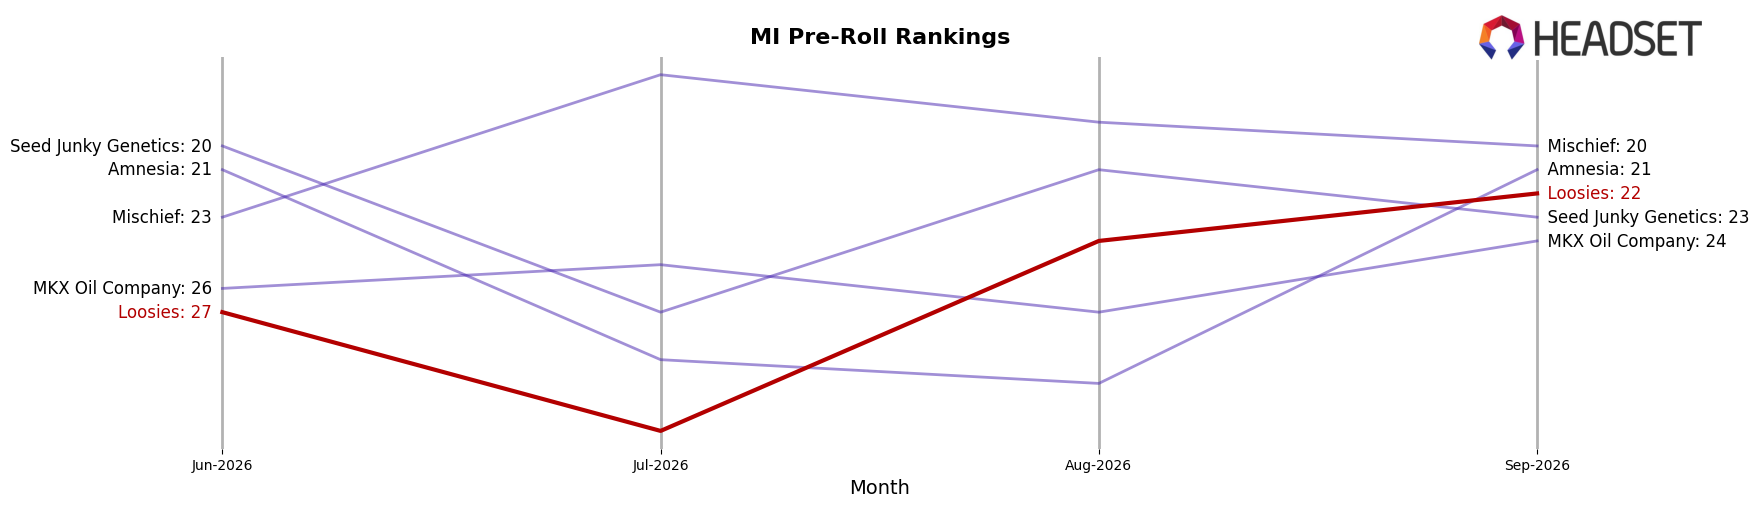
Loosies sits at rank #22 in Michigan Pre-Roll for September 2026 after a year-over-year climb of 199 positions from #221, and it improved 5 spots from #27 in June 2026 to #22 in September 2026, marking a new peak rank. Against category leaders, Jeeter held #1 with a 149.9% YoY sales increase while Cali-Blaze stayed at #2 despite a 36.1% YoY decline, indicating that Loosies’ ascent is coming from share capture in the mid-tier rather than displacement at the very top. With a rapid rank rise of 199 places YoY and a 5-place gain over the last three months, the trajectory implies Loosies is transitioning from fringe presence to stable mid-tier consideration, with headroom constrained by entrenched top-3 incumbents.
Notable Products
City Kush Pre-Roll (1g) posted the steepest movement in September 2026 with a -11.6% month-over-month drop while sliding to rank 10, contrasting with White Gummy Pre-Roll (1g) up 13.4% at rank 1 and Pablo's Revenge Pre-Roll (1g) up 14.0% at rank 3. Across the top ten, all listed SKUs are Pre-Roll products, indicating 10 of 10 concentration in a single category, and Lemon Cherry Gelato Pre-Roll (1g) added a 14.5% lift at rank 6 as Skywalker OG Pre-Roll (1g) inched up 1.3% at rank 9. With the top two ranks both growing (13.4% and 6.7%) while the only double-digit decline sits at the bottom, the mix points to Loosies doubling down on leading Pre-Roll flavors and pruning or repositioning underperformers within the same format.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

