

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
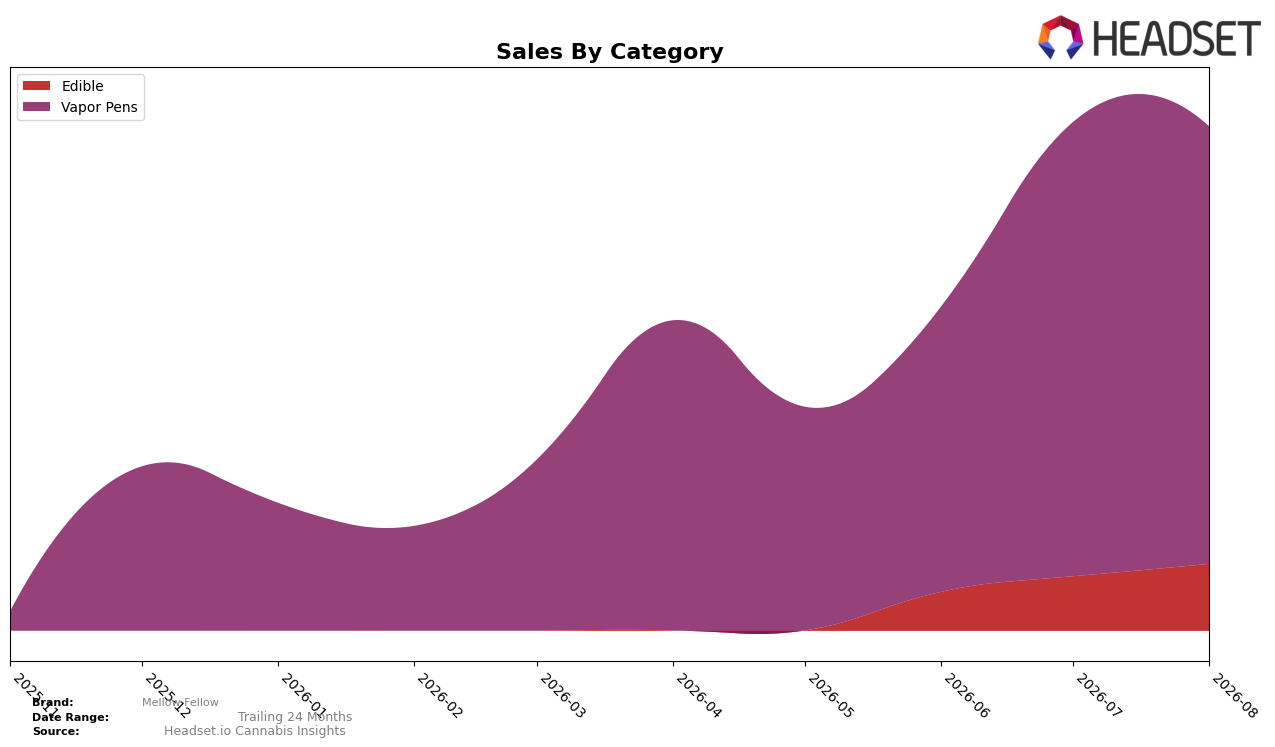
In August 2026, Mellow Fellow concentrated 86.79% of sales in Vapor Pens while Edible accounted for 13.21%, and within-month movements diverged with Vapor Pens down 3.65% MoM and Edible up 22.73% MoM; with an average brand price of $28.57 versus $31.01 in Vapor Pens and $18.84 in Edible, mix is skewed toward the higher-price category despite a month-on-month contraction. Anchored in Maryland and ranked 20 in Vapor Pens, the brand’s category exposure pairs a top-heavy 86.79% share with a rising 13.21% secondary foothold, implying incremental resilience if Edible momentum offsets Vapor Pen softness.
The 3.65% month-on-month dip in Vapor Pens against a 22.73% month-on-month lift in Edible suggests a tactical opening to rebalance without eroding the Vapor Pen base where the brand sits at rank 20, and the 86.79% versus 13.21% split outlines headroom to reallocate promotion and innovation toward the faster-moving Edible line. Given Vapor Pens’ average price at $31.01 compared to $18.84 in Edible, maintaining margin while shifting a portion of volume toward the expanding Edible segment will require mix-aware pricing and pack architecture, implying a positioning pivot where Edible becomes the growth engine while Vapor Pens anchor distribution and visibility.
Competitive Landscape
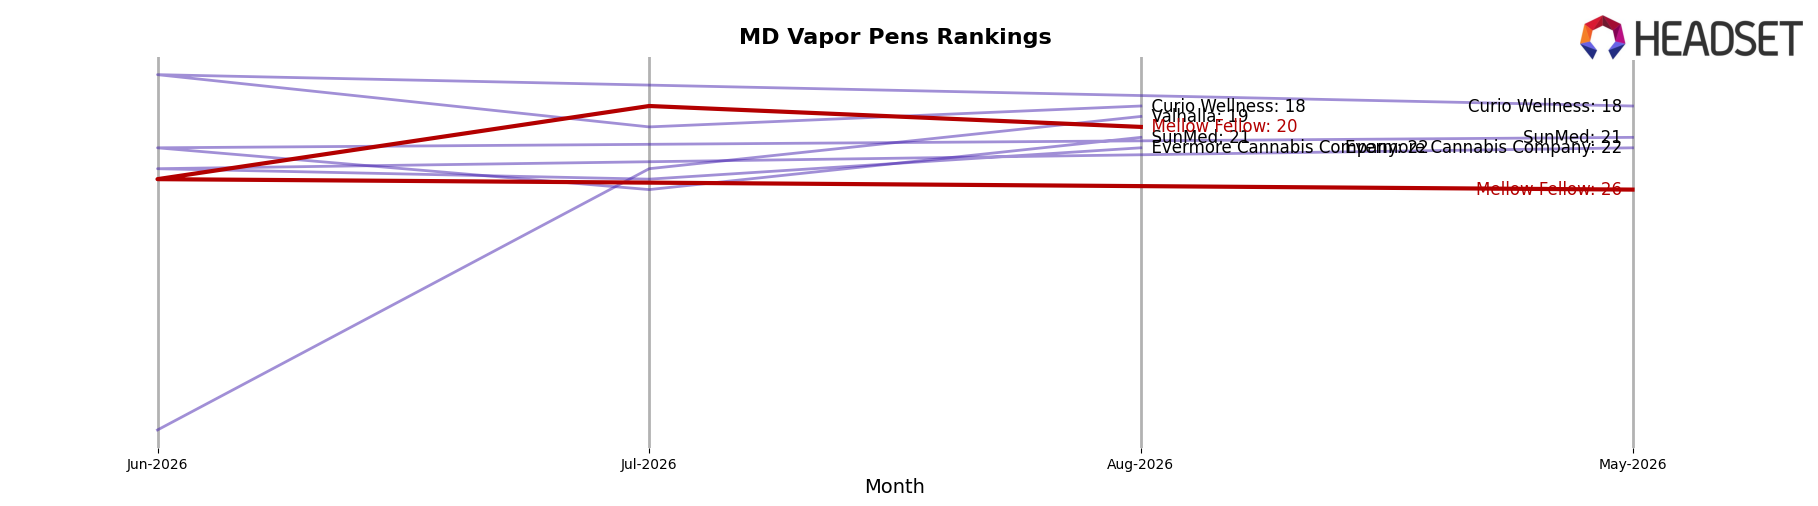
Mellow Fellow ranks #20 in MD Vapor Pens for August 2026, improving 6 positions from #26 in May 2026 and sitting 2 places below its peak at #18 in July 2026; this follows a three-month climb of 23.1% in rank position terms (from 26 to 20) while the peak-to-current slip is 11.1% (from 18 to 20). In contrast, Rove advanced year over year from #11 to #5 with 125.3% sales growth and RYTHM moved from #4 to #3 despite a 7.0% sales decline, indicating that upward mobility at the top is mixing both share capture and attrition effects; the pattern implies Mellow Fellow’s recent upward drift is real but not yet durable, as holding a top-20 foothold after a brief peak requires translating rank gains into sustained share against faster-rising competitors.
Notable Products
Durban Poison Distillate Cartridge (1g) posted the standout move in August 2026 with a +64.6% month-over-month surge to rank 1, while Green Crack Distillate Disposable (1g) fell -41.3% to rank 4, signaling a clear shift toward cartridges over disposables. Northern Lights Distillate Cartridge (1g) added +6.6% at rank 2, and Blue Dream Distillate Cartridge (1g) grew +7.8% at rank 3, whereas White Widow Distillate Disposable (1g) and Blue Razz Slushie Distillate Disposable (1g) declined -31.3% and -32.4% at ranks 8 and 10, respectively. Seven of the top ten are Vapor Pens with cartridges occupying ranks 1–3 while three disposables sit at ranks 4, 8, and 10, which implies the mix is tilting toward refillable-style cartridge preference and away from disposables despite one-time volume spikes like $41,552 on the leading SKU.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

