


Where to Buy
Mini Mart is stocked at 198 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, The Bronx, and Buffalo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
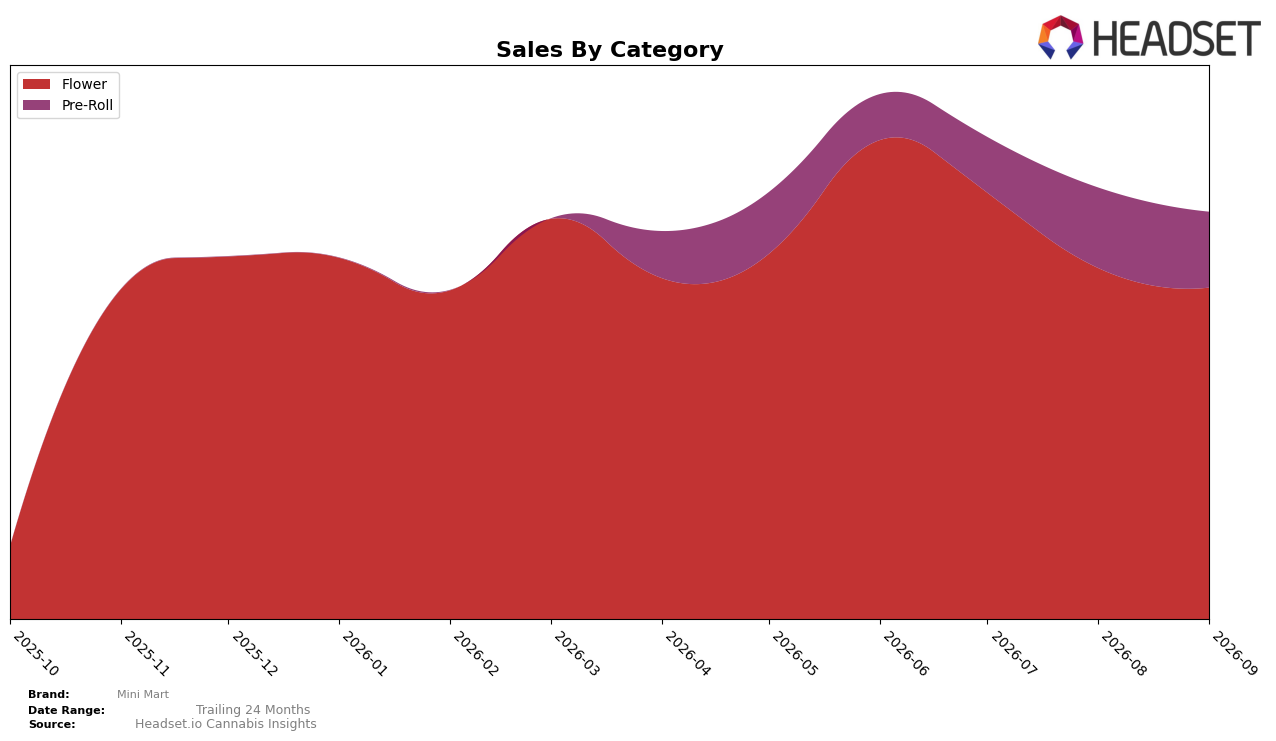
In September 2026, Mini Mart concentrated 81.45% of sales in Flower and 18.55% in Pre-Roll, with Flower down 5.55% month over month and Pre-Roll down 5.87% month over month, while the brand’s average price sat at $21.45. Within Flower specifically, the average price of $23.14 coincided with a 5.55% month-over-month volume or mix contraction, and Pre-Roll’s $16.25 average price paired with a 5.87% month-over-month contraction, indicating similar pressure across both categories. The mix stability at an 81/19 split alongside parallel month-over-month declines implies category-level demand softness rather than a product-line-specific issue.
Mini Mart ranked 18 in Flower in New York, a position that, paired with an 81.45% reliance on Flower and a 5.55% month-over-month decline there versus a 5.87% decline in Pre-Roll, implies overexposure to a category where middle-tier rank limits upside. The near-parallel month-over-month drops across both categories and an 18.55% Pre-Roll share suggest limited diversification levers, so maintaining or improving rank likely requires pricing or assortment tactics that shift 2–4 share points toward formats less sensitive to the same demand cycle. The takeaway is that Mini Mart’s current mix locks performance to Flower’s mid-pack dynamics in New York, so modest rebalancing could reduce volatility without sacrificing the core 81% sales base.
Competitive Landscape
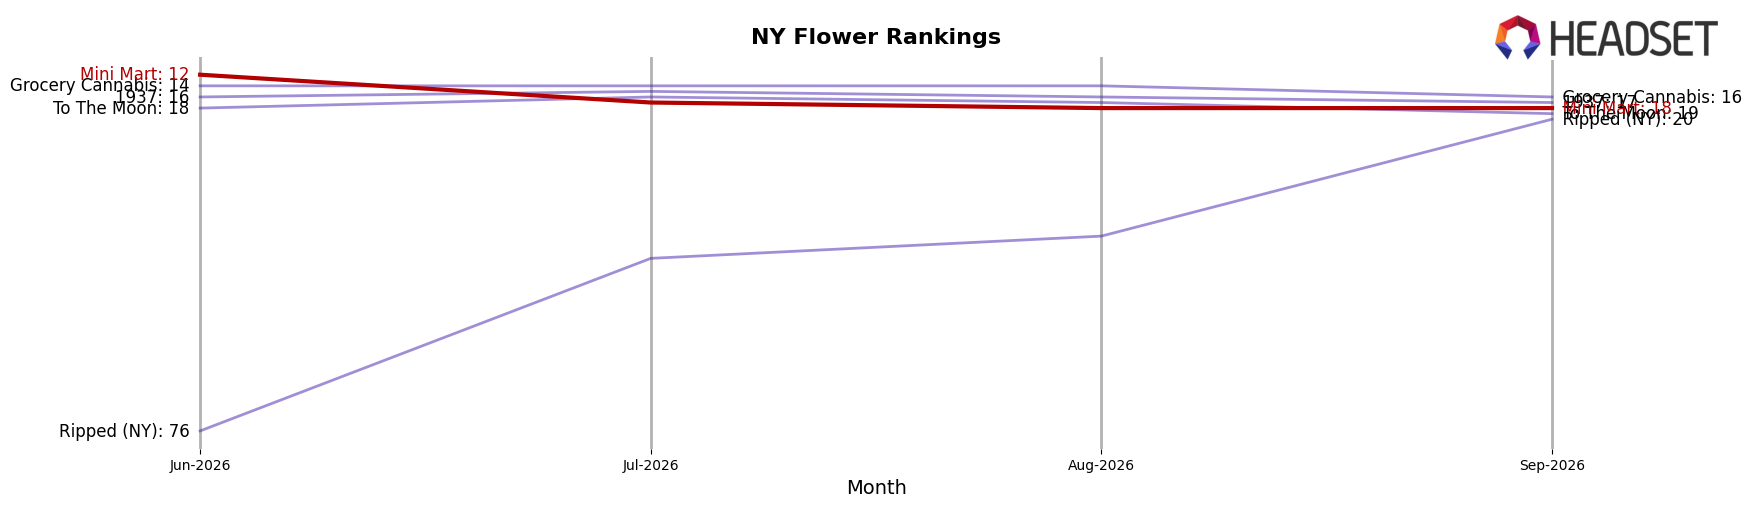
Mini Mart sits at #18 in NY Flower in September 2026, down 6 positions from #12 in June 2026, with a 3-month slide of 6 ranks from #12 to #18; without a year-over-year rank for September 2025, the immediate signal is intra-year erosion rather than an annual reset. Meanwhile, Find. advanced to #1 with a +5 YoY rank change and 16.2% sales growth, and Grassroots moved to #2 with a +15 YoY rank change alongside 150.3% sales growth, while RYTHM holds #5 with an +8 YoY rank change and 20.3% sales growth; in contrast, Mini Mart’s fall from #12 to #18 over three months compresses shelf visibility and suggests recent share is being reallocated toward faster-climbing leaders. The pattern implies Mini Mart’s rank trajectory is a near-term decline driven by competitive outpacing from top movers, requiring either regained velocity to re-approach its #12 peak or acceptance of a mid-pack position as leadership consolidates above it.
Notable Products
Jack Herer (3.5g) posted the steepest movement in September 2026 with a -49.9% month-over-month drop while sitting at rank 3, contrasting with Clementine (3.5g) at rank 1 and Stardawg (3.5g) at rank 2. Flower dominates concentration with eight of the top ten SKUs, placing ranks 1, 2, 3, 4, 5, 7, 8, and 10, while Pre-Roll appears only at ranks 6 and 9; the split implies Mini Mart is still levered to a single category despite a -49.9% shock inside its top tier. The Pre-Roll presence at ranks 6 and 9 alongside a top-heavy Flower stack at ranks 1 and 2 suggests format diversification is limited and any volatility in core Flower strains could move total category dollars, with Clementine (3.5g) alone contributing $54,948.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

