

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
RIPPED (Canada) is stocked at 103 licensed dispensaries across New York and Washington, 99 of them in New York, with the deepest coverage in New York, Queens, Brooklyn, Depew, and Farmingdale. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
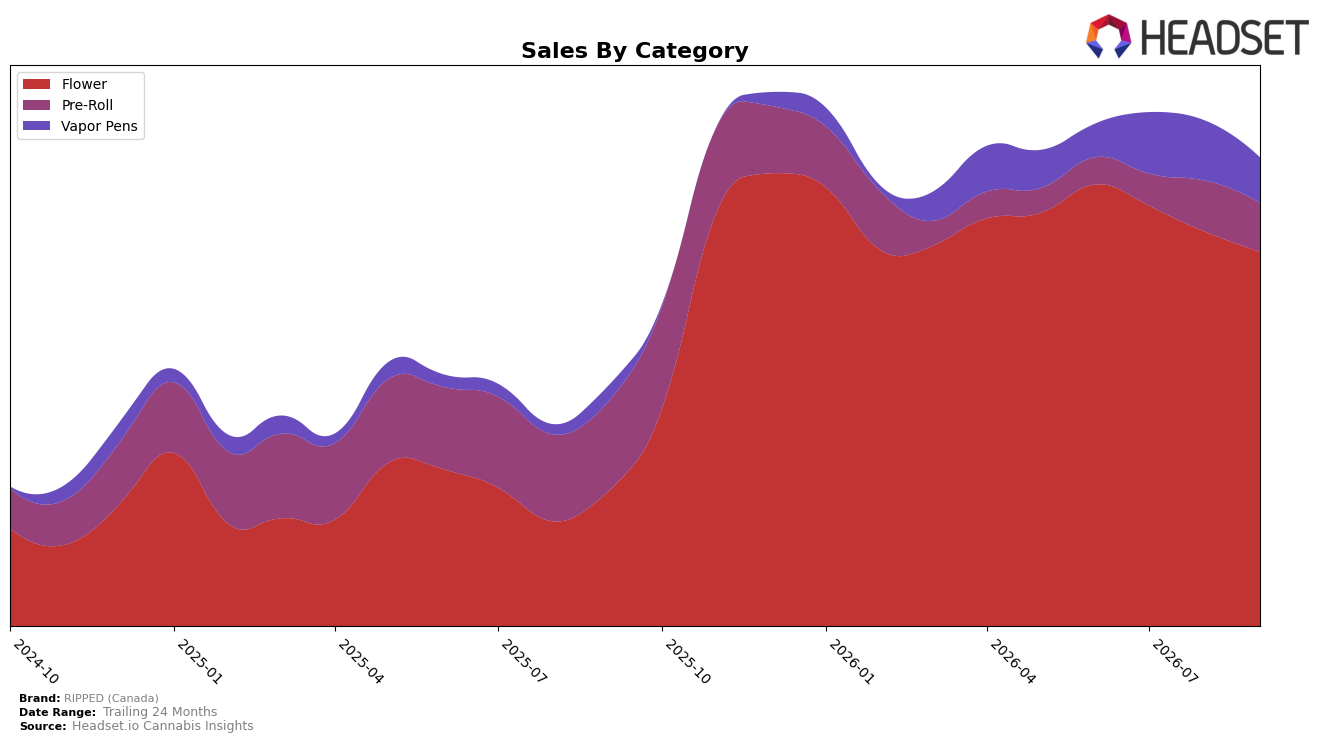
In September 2026, RIPPED (Canada) concentrated 76.04% share in Flower, up 161.47% year over year but down 4.91% month over month, while Vapor Pens held 11.68% share with 98.07% YoY growth and a 19.60% MoM decline; Pre-Roll sat at 12.27% share with a 39.59% YoY contraction and a 3.65% MoM dip. The overall brand sales grew 80.83% YoY as average price climbed 77.43% YoY to $23.03, yet the brand’s Flower rank was 28 in Alberta, indicating scale in Flower alongside slippage in short-term velocity. The mix shift toward higher-priced Flower (avg price $42.47) alongside Vapor Pens’ double-digit share and sharp MoM pullback implies reliance on premiumized Flower to carry growth while near-term momentum softened in inhalables.
These shifts suggest RIPPED (Canada) is leaning into a premium Flower-led positioning (76.04% share; rank 28 in Alberta) while ceding transactional frequency from Pre-Roll (−39.59% YoY; 3.65% MoM decline) and episodic demand from Vapor Pens (−19.60% MoM; +98.07% YoY). The combination of 80.83% YoY brand growth and a 77.43% YoY price lift, alongside a 4.91% MoM dip in Flower and a 19.60% MoM drop in Vapor Pens, implies pricing power concentrated in Flower but vulnerability in repeatable, lower-ticket formats, so sustaining share likely depends on stabilizing inhalables without diluting the higher-margin Flower core.
Competitive Landscape
RIPPED (Canada) sits at rank #37 in September 2026, down 10 positions from #27 in June 2026 and 18 places below its peak at #19 in November 2025, while top rivals are moving up: Find. holds #1 with a 5-position YoY climb and 16.2% sales growth, and Grassroots advanced 15 ranks to #2 alongside 150.3% YoY sales growth; this divergence—RIPPED (Canada) sliding quarter-over-quarter as leaders gain rank—implies a loss of share-of-shelf momentum that will compound if the brand cannot reverse the rank decline.

Notable Products
Blue Imagination Milled (7g) set the tone in September 2026 with a -20.2% month-over-month slide while holding rank 4, and Strawberried Liquid Diamond Disposable (0.95g) dropped -26.6% at rank 10, indicating softness in Flower and Vapor Pens even as Rolls Pre-Roll 3-Pack (1.5g) stayed at rank 1 with a -3.4% dip. Hybrid Blend Pre-Roll (1g) surged +48.6% to rank 3 but did not clear the +50% threshold, and Indica Pre-Roll (1g) fell -14.1% at rank 2, so five of the top ten are Pre-Roll SKUs, concentrating demand in that format over Vapor Pens and larger Flower packs. Zooted (28g) entered the list at rank 8 with $103,236 and no prior month baseline, while Sativa Blend (3.5g) rose +31.5% to rank 7, pointing to polarized Flower dynamics between value ounces and smaller-size uplift. The mix implies RIPPED (Canada) is leaning into Pre-Rolls as the dependable volume engine while recalibrating Vapor Pens and select Flower SKUs to stabilize rank and margin.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

