

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Northern Harvest is stocked at 145 licensed dispensaries across California, with the deepest coverage in San Diego, Sacramento, Los Angeles, Vista, and West Hollywood. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
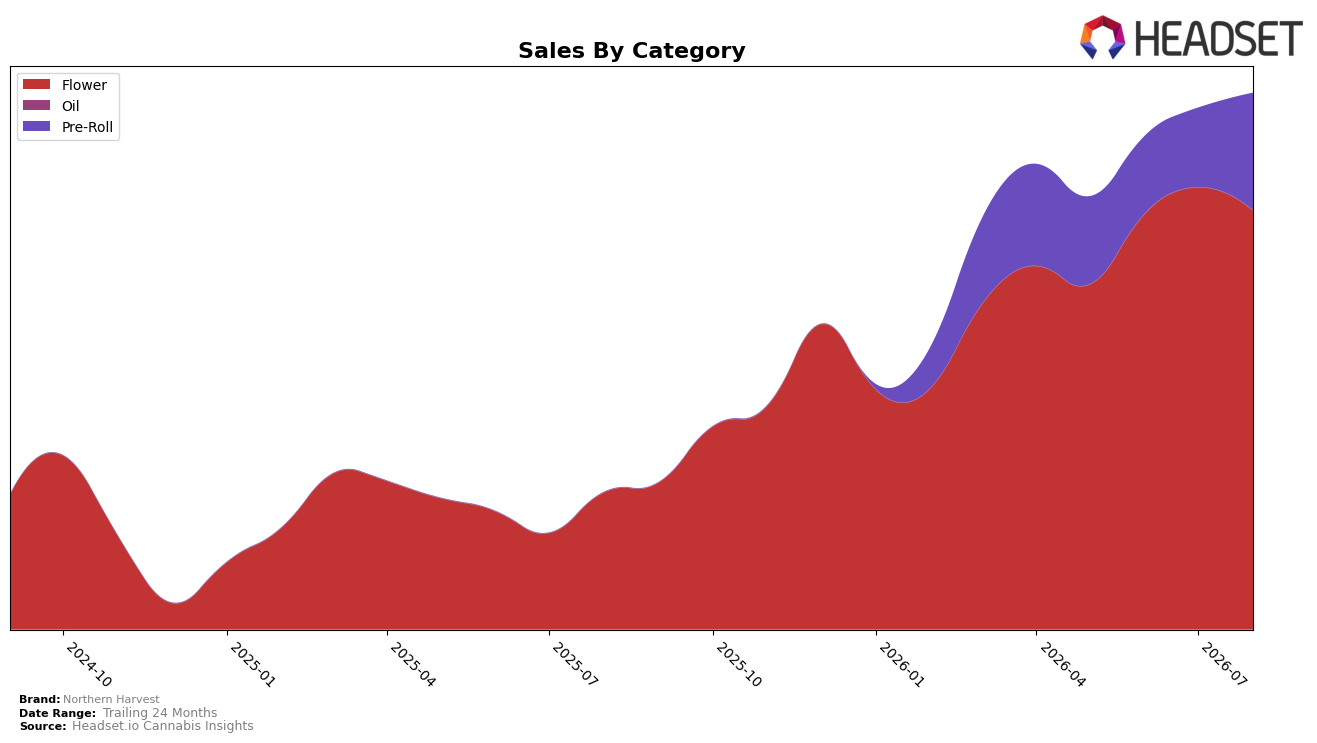
Northern Harvest concentrated 77.98% of August 2026 sales in Flower while Pre-Roll held 21.98%, a mix that shifted month over month as Flower declined 5.41% and Pre-Roll expanded 48.68%. Year over year, Flower sales rose 205.58% while average price fell 2.88%, implying unit growth exceeded revenue growth and that August 2026’s brand-level 291.89% YoY sales gain leaned on volume rather than pricing. With Oil at 0.05% share and no reported MoM or YoY movement, the portfolio is effectively a two-category play. The pattern implies Northern Harvest is trading down slightly on price to accelerate unit penetration in Flower while reallocating momentum toward Pre-Roll to offset single-category risk.
In category positioning terms, a 39 rank in Flower in California paired with 77.98% category dependence signals scale but exposure, and the 48.68% MoM surge in Pre-Roll provides a hedging vector if the 5.41% MoM Flower softness persists. Given 21.98% of sales now sit in Pre-Roll against a 205.58% YoY Flower rise, future share rebalancing could raise cross-category resilience without materially lifting average price from $36.59. The pattern implies Northern Harvest can convert recent Pre-Roll trial into a sustained second pillar while using lower Flower pricing to maintain rank velocity, reducing volatility from a single-category concentration.
Competitive Landscape
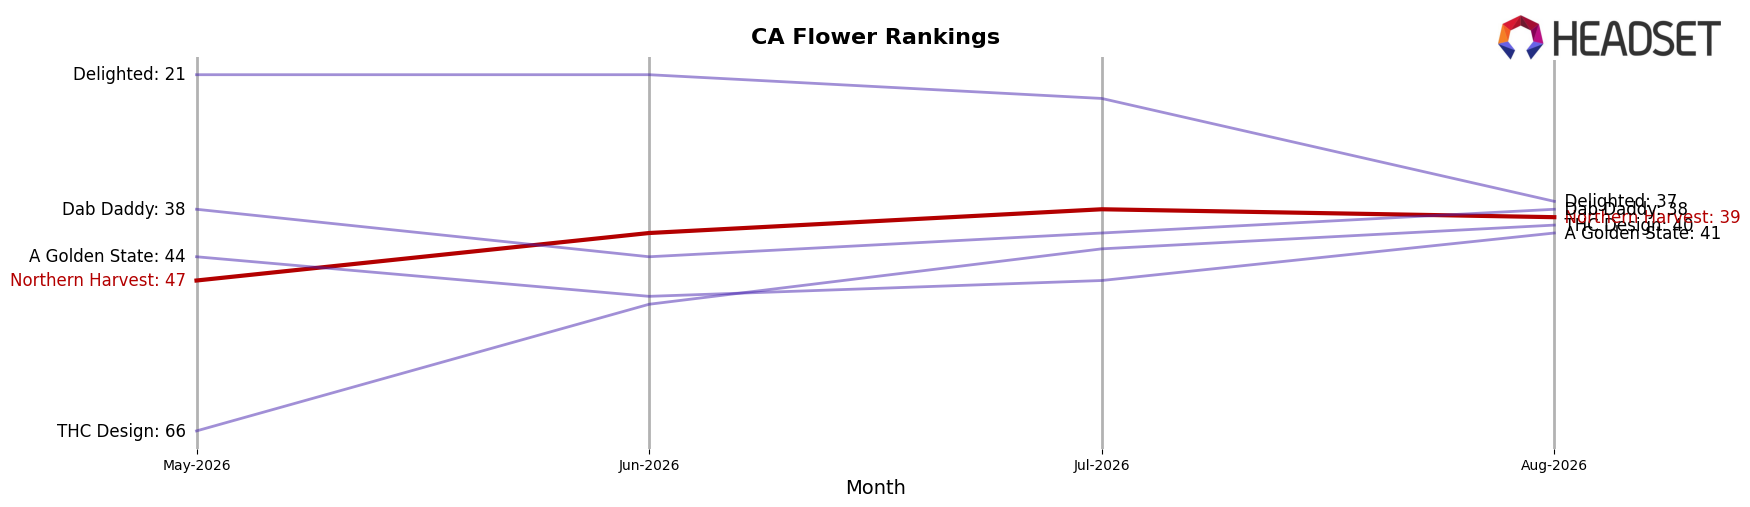
Northern Harvest sits at #39 in CA Flower in August 2026, improving 62 positions from #101 year over year, and edging up 8 ranks from #47 three months ago while staying just one spot off its peak at #38 in July 2026; meanwhile, STIIIZY climbed from #2 to #1 with a 50.4% YoY sales increase and CAM moved from #3 to #2 with 46.6% YoY growth, whereas CannaBiotix (CBX) slipped from #1 to #3 alongside a 16.0% YoY sales decline; this pattern implies Northern Harvest’s upward rank trajectory is occurring amid intensified top-tier churn, signaling room to consolidate mid-pack gains if the brand converts recent rank momentum into sustained share capture against leaders advancing and incumbents retreating.
Notable Products
The steepest decline came from GMO x OZ Kush (3.5g), which fell 44.2% month over month to rank 7, while Key Lime Jack (3.5g) also dropped 43.1% to rank 8, indicating a sharp pivot away from certain specialty Flower SKUs. Jack Herer (3.5g) posted a 37.9% MoM gain to rank 1 with $114,311, and Bubblegum Diesel (3.5g) rose 45.3% to rank 3, suggesting momentum is consolidating in a few flagship strains. Five of the top six ranked items are Flower SKUs, and within that set two posted double-digit declines of 16.9% and 11.9% while two rose more than 35%, pointing to heightened volatility within a concentrated category. The mix implies Northern Harvest is shifting shelf power toward a smaller set of high-velocity Flower leaders while allowing underperforming niche genetics to cycle down in August 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

