

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Onyx Label is stocked at 20 licensed dispensaries across Colorado, with the deepest coverage in Denver, Boulder, Colorado Springs, Aspen, and Edgewater. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
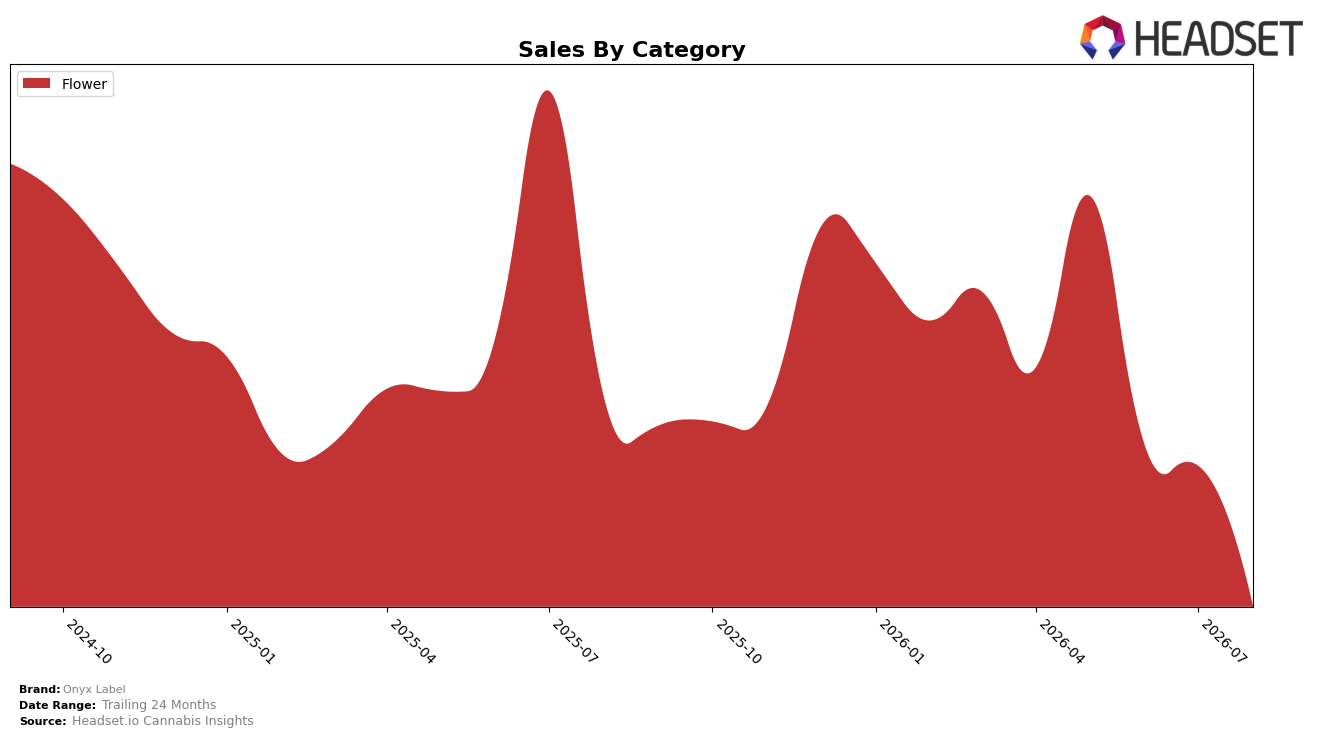
Onyx Label operated as a single-category brand in Flower during August 2026, with category share at 100.0% and a rank of 35 in Colorado Flower, while year-over-year sales declined 58.9% and month-over-month sales fell 49.1%. Average price decreased 5.2% year over year to $19.54, and the lack of category diversification meant zero buffer from other segments as Flower volume contracted; the pattern implies the brand’s concentrated mix amplified exposure to a downshift in the core category and pressured rank stability.
The combination of a 49.1% month-over-month sales drop alongside a 5.2% year-over-year price decline signals volume compression rather than a price-led shift, and a 100.0% Flower mix limits repositioning levers within August 2026. Holding the 35 rank in Colorado Flower while sales fell 58.9% year over year suggests share erosion against mid-pack peers and indicates that maintaining price near $19.54 did not preserve throughput; the pattern implies Onyx Label needs either mix expansion beyond Flower or targeted SKU rationalization within Flower to defend rank and mitigate further share loss.
Competitive Landscape
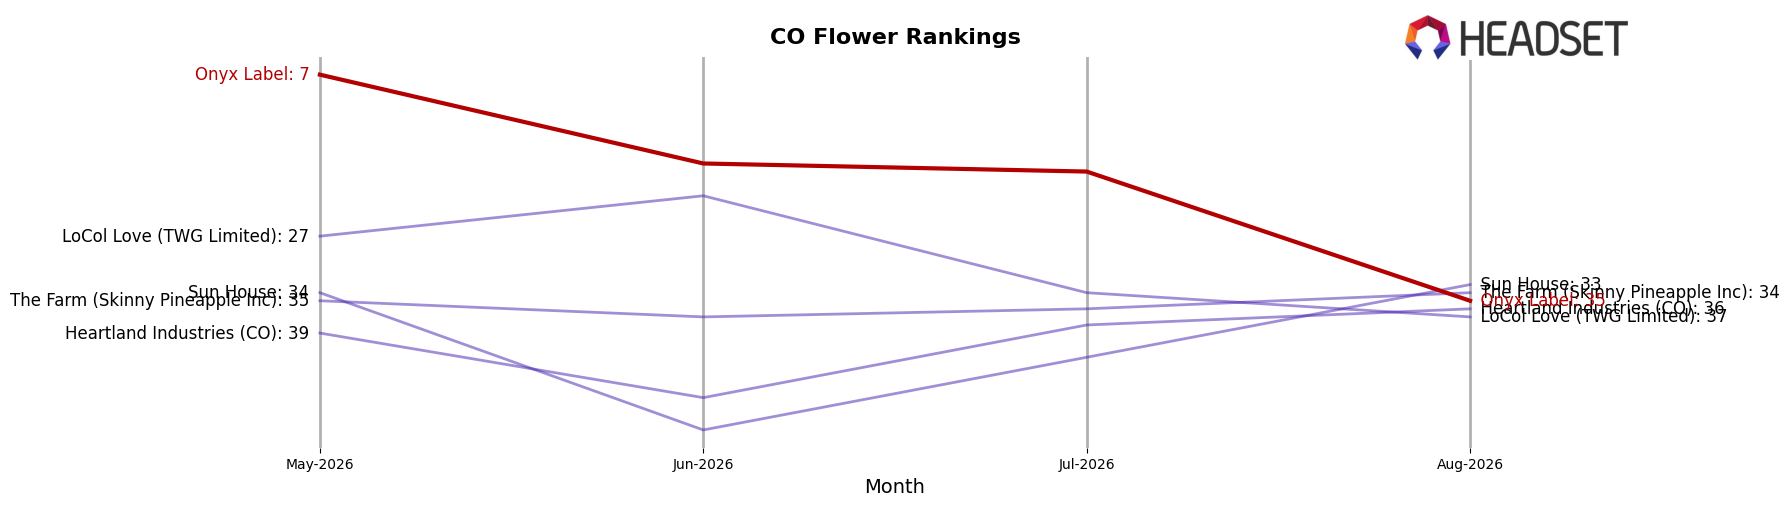
Onyx Label sits at rank #35 in Colorado Flower in August 2026, down 27 positions year over year from #8, and 28 spots below its May 2026 three-month reference point at #7; the brand’s peak of #6 in February 2026 underscores a steep descent versus a top-five threshold. Competitively, Seed & Strain Cannabis Co. climbed from #2 to #1 while Green Dot Labs moved from #5 to #3, indicating upward mobility among leaders as Onyx Label moved from a top-10 (#8) to outside the top-30 (#35). The pattern implies share consolidation at the top and a need for Onyx Label to arrest multi-month rank slippage to avoid further distribution and shelf visibility erosion.
Notable Products
Lemon Cookies (3.5g) posted the sharpest movement in August 2026 with a -53.9% month-over-month drop while sliding to rank 3, and Orange Cookie Chem (3.5g) fell even harder at -66.3% yet held rank 9; together these declines frame a month defined by contraction rather than breakout gains. Too Much Papaya (3.5g) declined -42.5% at rank 2, whereas Race Fuel OG (3.5g) led at rank 1 with $34,646 despite no reported month-over-month rate, indicating leadership concentration. With all top-10 entries in Flower and multiple SKUs dropping between -44.2% and -48.1% in the mid ranks, the portfolio skews toward a single category under pressure while relying on one flagship to carry rank share. The pattern implies Onyx Label is consolidating volume in a top-ranked hero SKU while the broader Flower bench contracts, pointing to a near-term need for mix diversification or pricing resets within Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

