

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Clear is stocked at 364 licensed dispensaries across Colorado, Montana, and 6 other states, 130 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Pueblo, Aurora, and Boulder. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
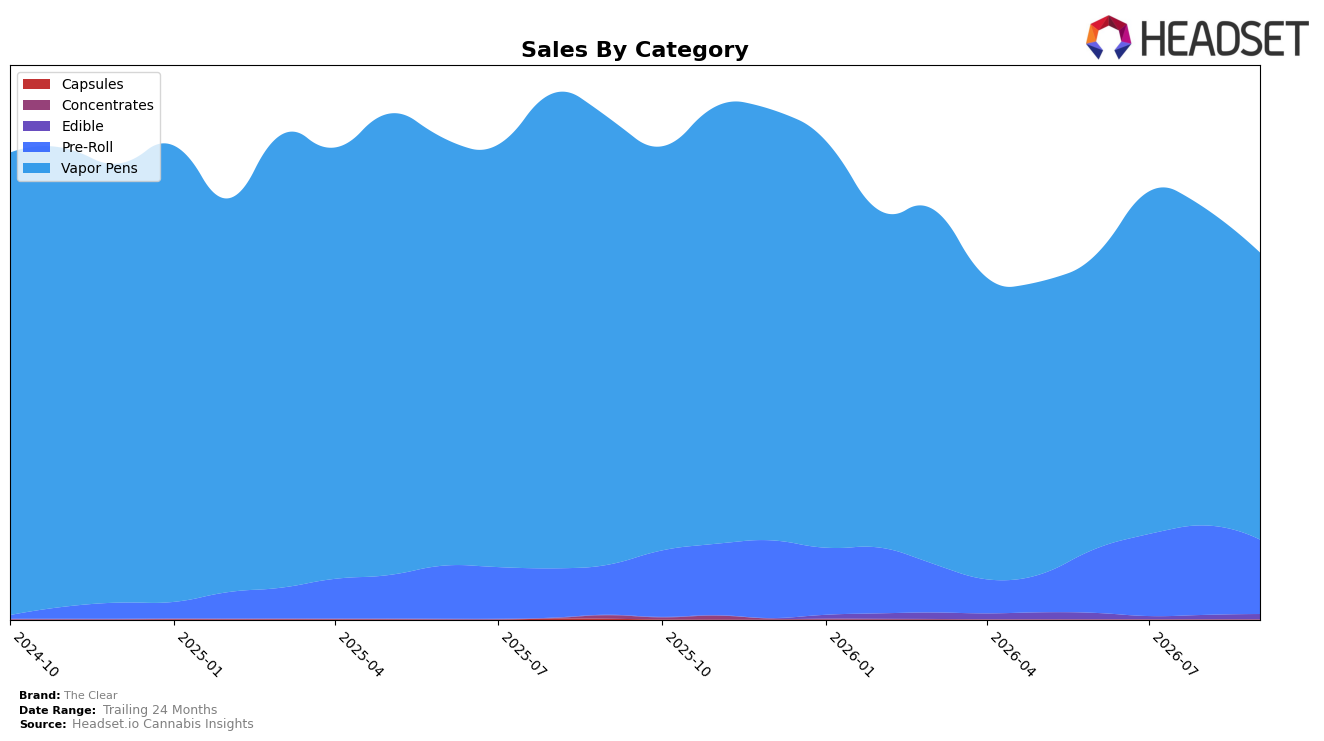
The Clear concentrated 78.45% of September 2026 sales in Vapor Pens with a year-over-year decline of 35.84% and a month-over-month decline of 9.59%, while Pre-Roll rose 49.08% year over year to 20.25% share but fell 16.88% month over month. Edible held 1.30% share with a 22.52% month-over-month increase and no year-over-year baseline, and the brand’s overall average price fell 23.67% year over year alongside a total sales decline of 26.98% year over year; taken together, the mix shows overexposure to a shrinking core category even as smaller lines add incremental balance.
Within Colorado Vapor Pens, The Clear ranked 19th in September 2026, and its 78.45% mix in that category suggests positioning anchored to a segment where rank pressure coincides with a 35.84% year-over-year decline. The 49.08% year-over-year lift in Pre-Roll and a 22.52% month-over-month uptick in Edible imply an emerging hedge against Vapor Pen contraction, yet the simultaneous 16.88% month-over-month drop in Pre-Roll and 9.59% month-over-month drop in Vapor Pens indicate short-term volatility; this pattern implies the brand is trading depth for breadth and should manage pricing—down 23.67% year over year—so that diversification contributes to rank stability rather than margin dilution.
Competitive Landscape
In September 2026, The Clear sits at rank 19 in CO Vapor Pens, down 2 positions year over year from rank 17 and up 7 spots versus June 2026 when it was rank 26; that mix of a 2-rank YoY decline and a 7-rank quarter-on-quarter climb contrasts with Spherex holding rank 1 with a 1.93% YoY sales gain and PAX rising from rank 3 to rank 2 alongside a 34.66% YoY sales increase, while The Clear’s historical ceiling at rank 9 in September 2024 frames today’s position as a retreat from peak but a rebound from early-summer lows; the implication is that The Clear’s near-term rank momentum is positive within-quarter, yet the two-position YoY slippage against competitors that are climbing or consolidating at ranks 1–2 signals a need to convert recent share recovery into sustained placement improvements to avoid further erosion.

Notable Products
Twax - Lime Sorbet Distillate Infused Pre-Roll (1g) posted the steepest decline at -34.3% month over month while falling behind category peers that held ranks 1 and 3, and Twax - Pure Pear Infused Pre-Roll (1g) also contracted by -28.7% despite sitting at rank 1. Within Pre-Roll, XJ-13 Infused Pre-Roll (1g) bucked the slide at +21.5% and secured rank 3, yet Pre-Roll concentration remained high with five of the top ten SKUs, indicating volume reliance even as two leaders posted declines larger than -25%. This pattern implies The Clear is leaning on breadth in Pre-Rolls while volatility in flagship Twax variants raises execution risk on flavor-led rotations and calls for mix recalibration toward steadier SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

