
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
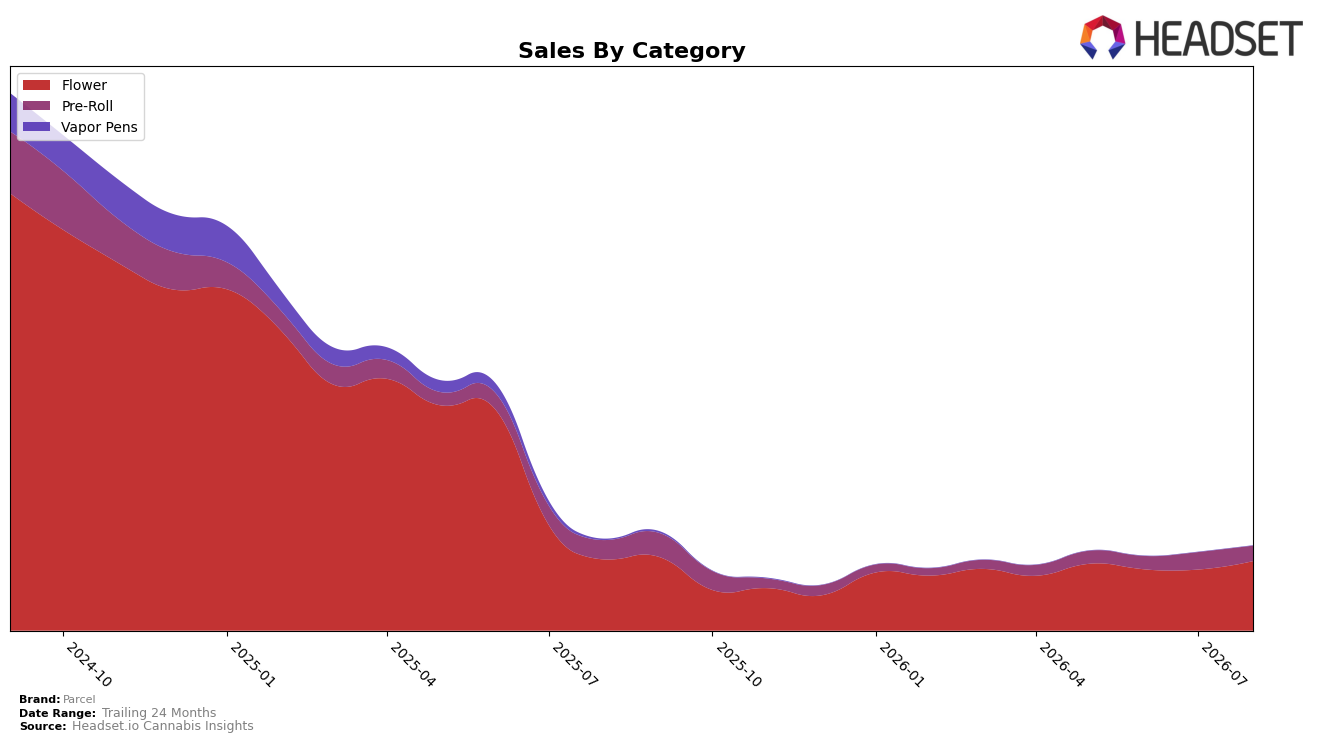
In August 2026, Parcel concentrated 82.14% of sales in Flower while Pre-Roll accounted for 17.86%, a mix that paired a 13.95% month-over-month gain in Flower with an 11.74% month-over-month decline in Pre-Roll. Year over year, Flower dipped 2.39% versus a 20.44% decline in Pre-Roll, and overall brand sales fell 7.26% YoY alongside a 16.67% YoY increase in average price. With Flower ranked 32 in Saskatchewan and the brand’s top market in ON, the pattern implies Parcel is leaning into higher-priced Flower to stabilize revenue while de-emphasizing lower-priced Pre-Rolls.
The mix shift and pricing indicate a positioning pivot toward premiumized Flower: Flower’s month-over-month growth of 13.95% against Pre-Roll’s 11.74% decline, combined with an 82.14% category share and a 16.67% increase in average price, signal a deliberate trade-up strategy. Given the 2.39% YoY contraction in Flower versus a 20.44% YoY pullback in Pre-Roll and a 24-month sales decline of 86.80%, the implication is that Parcel is consolidating around a narrower, higher-price-point Flower core to improve rank from 32 in Saskatchewan and protect margins in ON.
Competitive Landscape
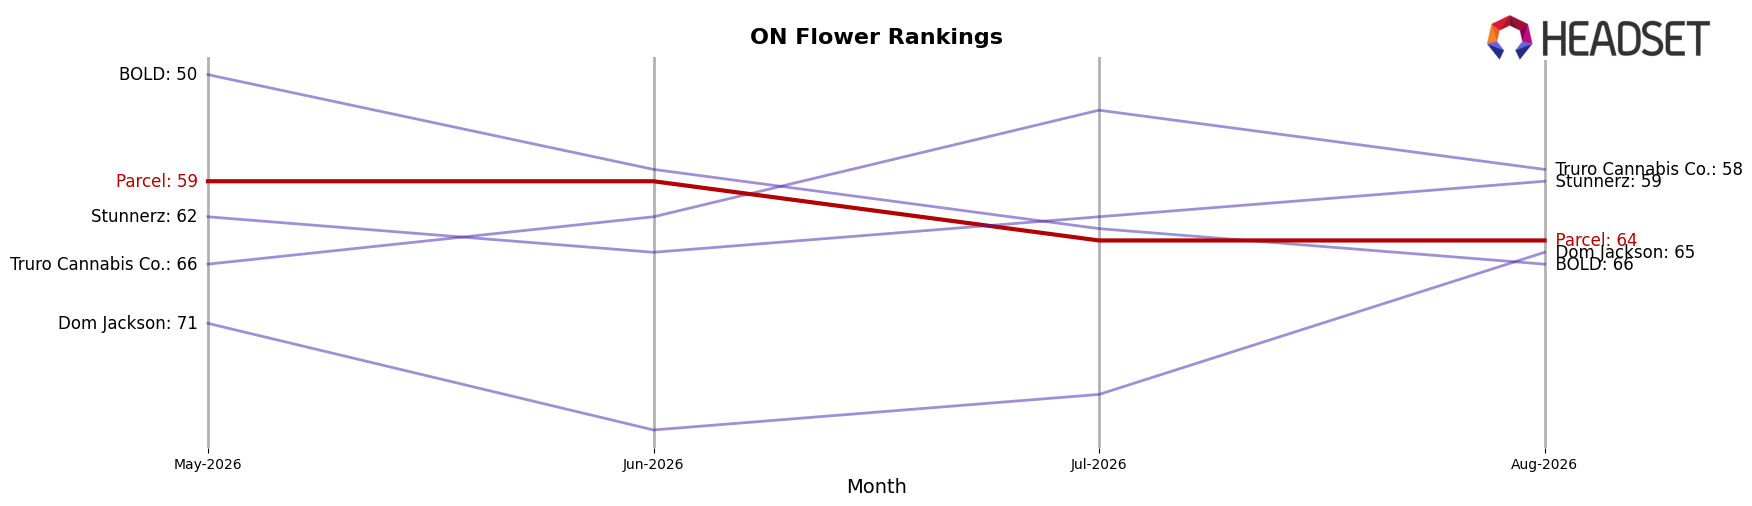
Parcel sits at rank #64 in ON Flower in August 2026, improving 11 positions from #75 year over year, but slipping 5 spots from #59 over the last three months; against the broader field, Shred moved from #2 to #1 with 18.96% YoY sales growth while Spinach rose from #4 to #2 with 27.45% YoY growth, indicating category leaders are accelerating faster than mid-tier brands. Despite a historical peak at #24 in August 2024 and a competitor like The Original Fraser Valley Weed Co. sliding from #6 to #5 with a -17.49% YoY sales change, Parcel’s mixed trajectory—up year over year yet down quarter-on-quarter—implies stabilization at a lower tier unless recent momentum converts into sustained share capture.
Notable Products
Citrus Notes (28g) posted the largest movement with a 5,358% month-over-month surge, vaulting into rank 3, while Sweet Notes (28g) also jumped 3,433% to rank 3, indicating a sudden tilt toward large-format Flower. Indica Sweet Notes Pre-Roll 2-Pack (1g) fell 11.7% yet held rank 1, contrasting with the Flower gains and signaling a trade-up from pre-rolls to bulk Flower. Four of the top ten are Flower SKUs, anchored by the two 28g entries and Sweet Notes (14g) declining 16.2% at rank 2, which together suggest consumers consolidating spend into higher-quantity packs even as smaller formats cool. The pattern implies Parcel is pivoting toward value-driven, large-format Flower where outsized gains can offset softness in pre-rolls and smaller bags.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

