
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
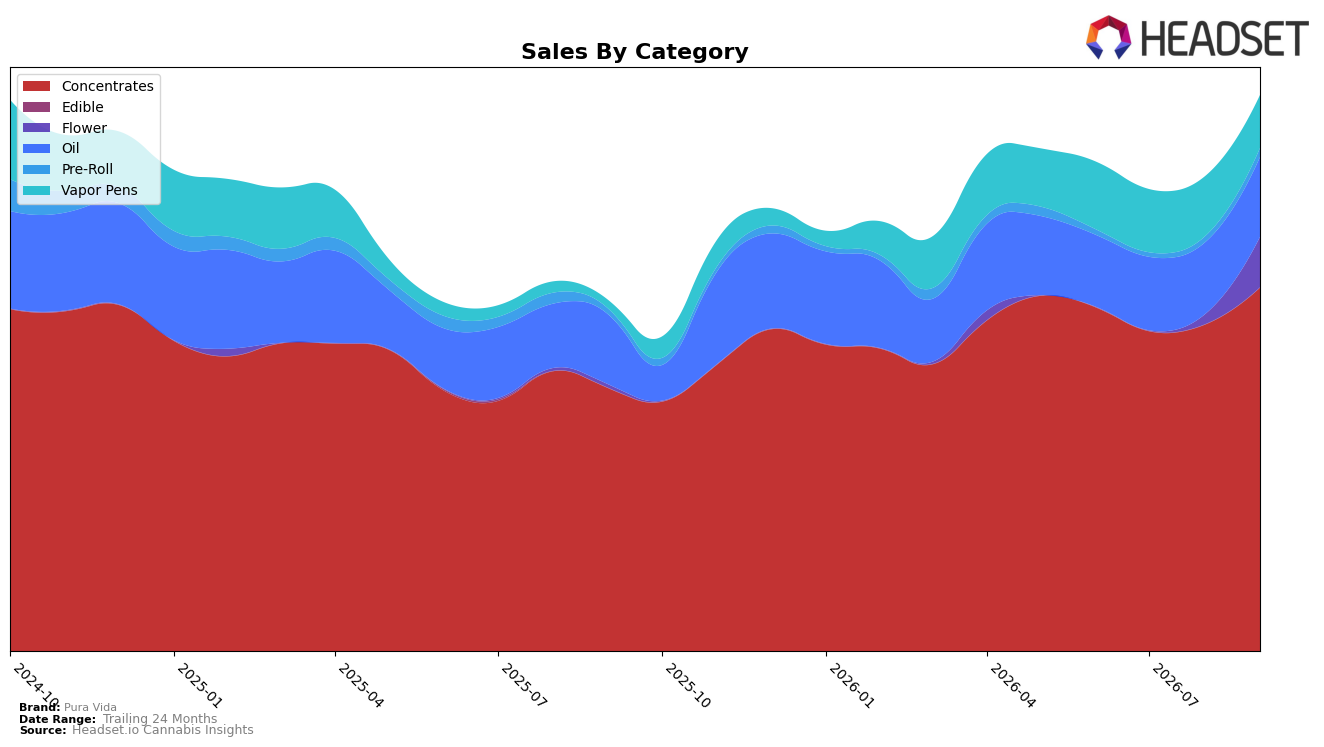
In September 2026, Pura Vida’s mix was concentrated in Concentrates at 65.55% share with 38.23% YoY growth and 11.37% MoM, while Oil held 14.33% share with 14.40% YoY and 11.17% MoM, signaling steady core categories alongside a sharper pivot. Vapor Pens reached 9.50% share with 534.55% YoY despite a -11.88% MoM drop, and Flower climbed to 9.04% share with 1472.60% YoY and 422.58% MoM, indicating a rapid re-entry that shifts the portfolio’s growth drivers. Pre-Roll remained a small 1.57% share but expanded 59.23% YoY and 52.82% MoM, suggesting incremental trial at low average price points. With average price up 1.83% YoY to $35.42 and the brand ranking 2 in Concentrates in Ontario, the combined surge in Flower and stability in Concentrates implies a broadening from a single-category anchor to a two-engine mix capable of sustaining the 58.70% brand-level YoY growth.
The category shifts imply Pura Vida is using Concentrates (rank 2) as a credibility base while reallocating demand toward higher-velocity re-entry bets: Flower’s 422.58% MoM spike and 1472.60% YoY suggest rapid distribution fill and price-led trial, contrasted with Vapor Pens’ -11.88% MoM after 534.55% YoY indicating early saturation or SKU rationalization. Oil’s 11.17% MoM alongside a 14.40% YoY provides stability to smooth volatility from Flower, while Pre-Roll’s 52.82% MoM on a 1.57% share points to basket-building rather than headline revenue. The net effect of a modest 1.83% YoY average price increase, combined with expanding Flower and steady Oil, positions Pura Vida to convert rank exposure in Concentrates into cross-category penetration, reducing reliance on a single category while protecting share through September 2026.
Competitive Landscape
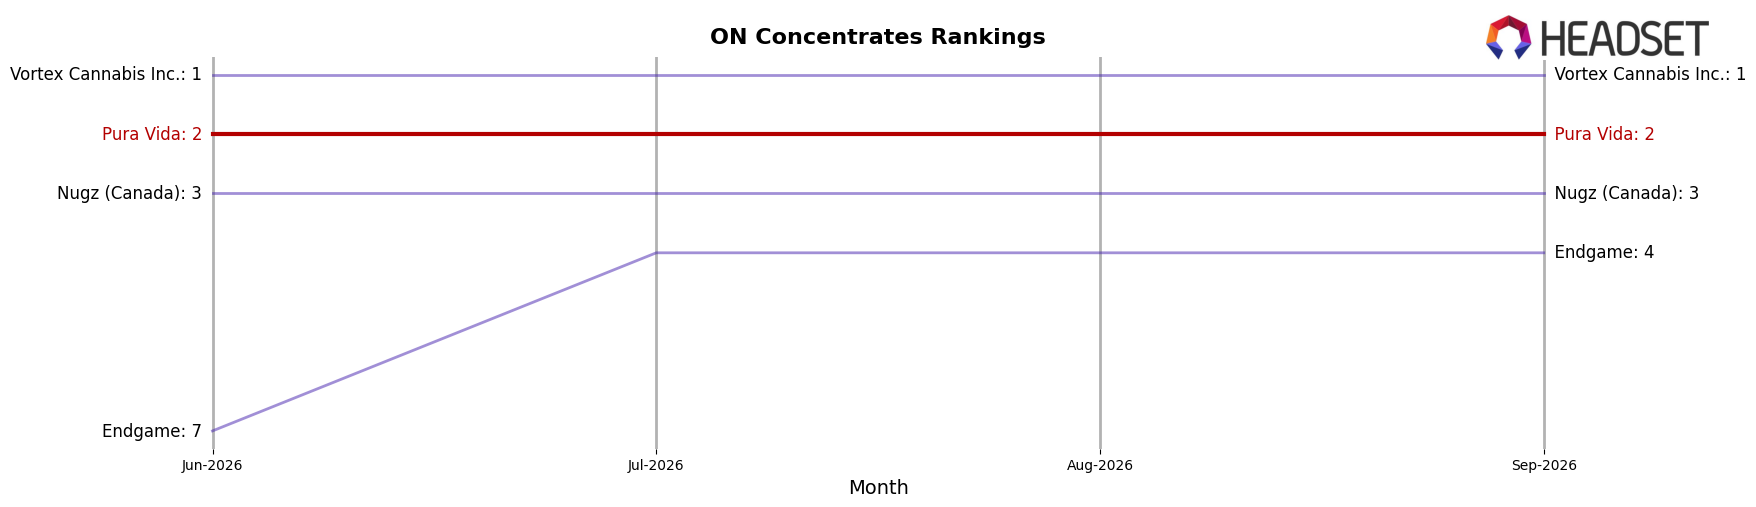
Pura Vida sits at rank #2 in ON Concentrates with a year-over-year climb from #4, while holding #2 over the past three months and matching its peak at #2 in September 2026; in contrast, Vortex Cannabis Inc. stayed at #1 year-over-year despite a -12.96% sales change, and BoxHot moved up from #9 to #5 alongside a 52.32% sales increase. Against mid-pack pressure, Nugz (Canada) slipped from #2 to #3 with a -30.80% sales decline and Endgame moved from #3 to #4 with a -37.87% sales drop, while Pura Vida’s ascent from #4 to #2 and maintenance of #2 for three months implies defensible share consolidation near the category lead rather than transient volatility.
Notable Products
Cherry Vanilla Honey Oil Dispenser (1g) posted the standout move in September 2026 with a +71.5% MoM surge while jumping into rank 7, contrasted by Pineapple Express Live Resin Cartridge (1g) slipping -11.0% to rank 3 and Venom OG Jumbo Slab Shatter (1.2g) dropping -16.8% at rank 8. Concentrates account for six of the top ten SKUs, led by Sativa Honey Oil Dispenser (1g) at rank 1 with +17.0% MoM and Indica Honey Oil Dispenser (1g) at rank 2 with +3.9% MoM, indicating the dispenser format is expanding share even as a key vapor pen retreats. The mixed movement—double-digit gains in two concentrate SKUs alongside a double-digit decline in a vapor pen—implies Pura Vida is tilting mix and merchandising toward value-forward oil formats where repeat velocity is accelerating.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

