

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
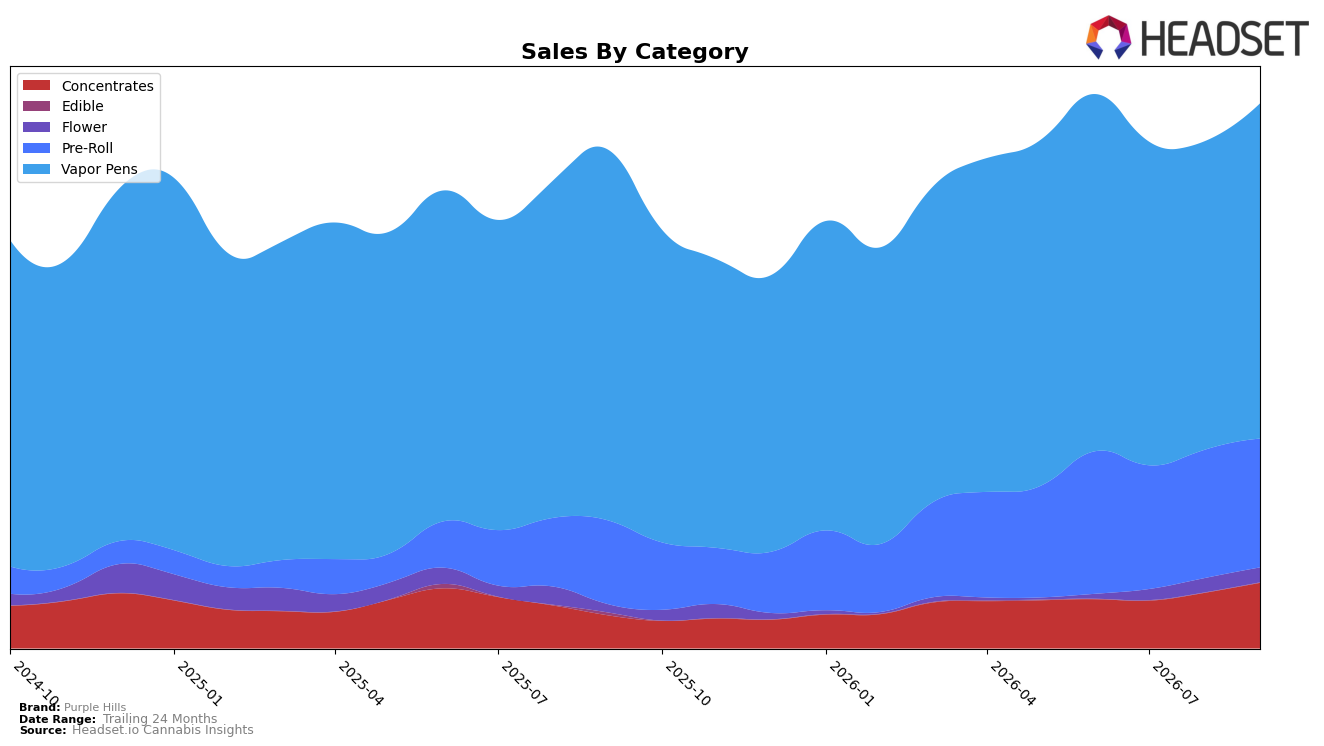
In September 2026, Purple Hills concentrated 61.63% of sales in Vapor Pens, where category sales fell 9.58% year over year but rose 8.64% month over month, while the brand held rank 11 in Vapor Pens in Ontario. Pre-Roll expanded to 23.64% share with 54.04% YoY growth and a modest 0.42% MoM uptick, and Concentrates reached 12.02% share with 99.08% YoY and 18.05% MoM growth; against this mix shift, the brand’s overall sales were up 9.33% YoY even as the average price fell 25.29% YoY, implying unit volume gains concentrated outside the softening Vapor Pens core.
The shift toward Pre-Roll and Concentrates—adding a combined 35.66% share with 54.04% and 99.08% YoY growth, respectively—suggests Purple Hills is leaning into faster-turn, lower-price-per-unit formats while keeping momentum with 8.64% MoM recovery in Vapor Pens. With Flower growing 82.93% YoY and 3.98% MoM off a 2.68% share base and Edible collapsing 93.74% YoY despite a 223.72% MoM rebound, the pattern points to a price-sensitive portfolio tilt that can support near-term share capture in value-leaning segments while the Vapor Pens position at rank 11 in Ontario limits premium-led mix lift, implying the path to higher margin depends on sustaining double-digit MoM in Concentrates or raising realized price in Vapor Pens without conceding the 61.63% anchor.
Competitive Landscape
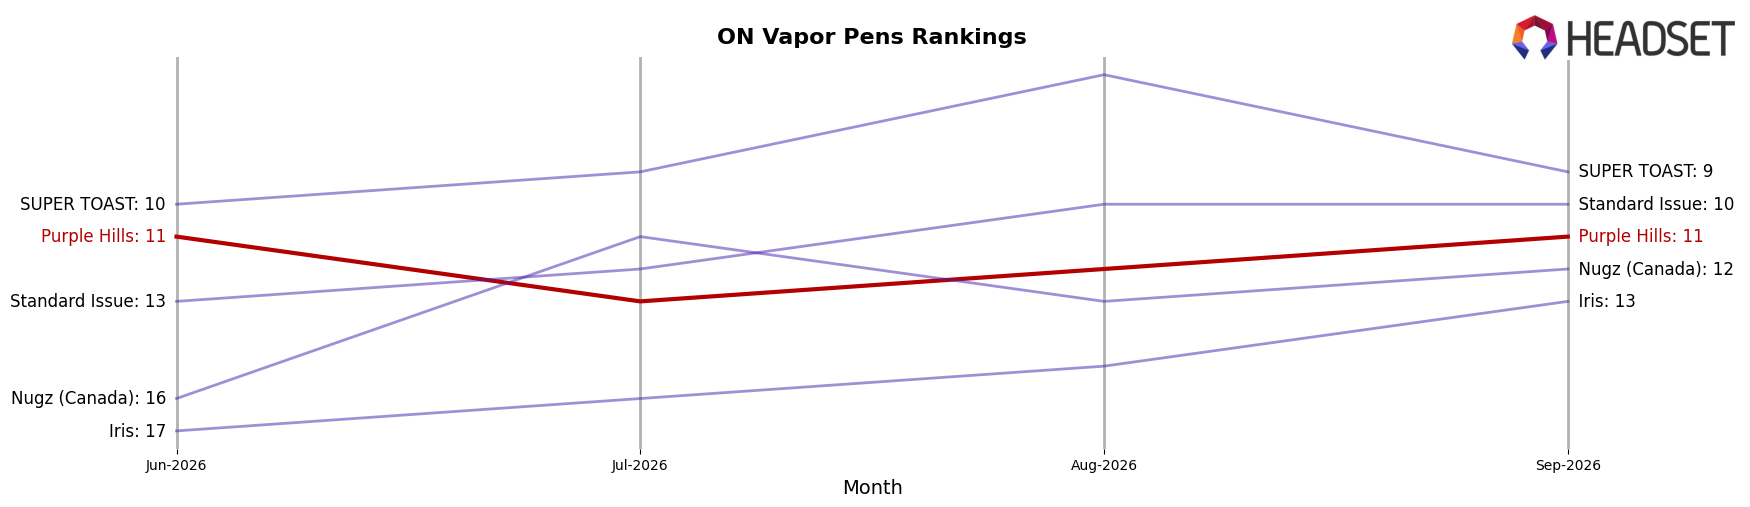
Purple Hills sits at rank #11 in ON Vapor Pens in September 2026, unchanged from #11 year over year, and also flat versus three months ago at #11; the lack of rank movement alongside competitors shifting positions indicates stable share rather than momentum. In contrast, Spinach climbed from #4 to #1 while growing sales by 172.5%, and Kolab jumped from #14 to #5 with 93.0% YoY growth; meanwhile, General Admission moved from #3 to #4 with an 12.0% YoY decline, suggesting churn within the top tier as Purple Hills holds steady. With a peak rank of #11 reached in September 2026 and no YoY change from #11, the trajectory implies Purple Hills is treading water while faster-moving rivals compress headroom for upward mobility.
Notable Products
Iced Sangria Pre-Roll (1g) set the tone with a -35.5% month-over-month drop while still holding rank 1, a juxtaposition that signals volume concentration at the top even as velocity cools. Indica Distillate Cartridge (1g) at rank 2 grew 11.3% MoM and Sativa Distillate Cartridge (1g) at rank 4 rose 13.7%, indicating Vapor Pens gained share against Pre-Rolls where 95+ Island Drip Distillate Cartridge (0.95g) slipped -7.8% at rank 5. Four of the top ten are Pre-Roll SKUs yet three of the top five spots include Vapor Pens, and Afghan Black Hash (2g) edged up 2.0% at rank 10, pointing to a portfolio that is tilting toward carts while legacy Pre-Rolls absorb volatility. The pattern implies Purple Hills is migrating demand toward higher-consistency Vapor Pens even as flagship Pre-Rolls anchor rank positions but with heavier month-to-month swings.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

