

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Regulator is stocked at 134 licensed dispensaries across Washington, with the deepest coverage in Spokane, Seattle, Everett, Bellingham, and Mount Vernon. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
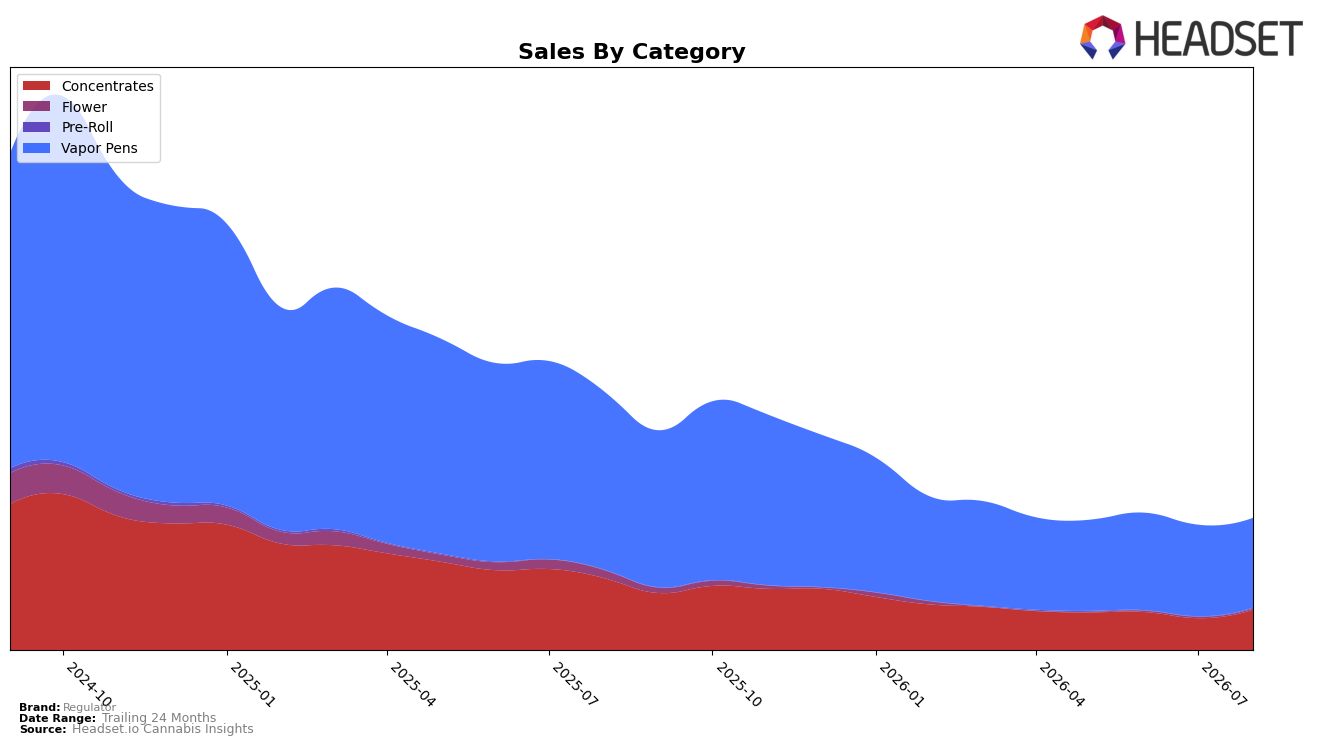
In August 2026, Regulator’s mix concentrated in Vapor Pens at 68.43% share with year-over-year decline of 49.74% and month-over-month dip of 1.89%, while Concentrates rose to 30.50% share with a 44.22% YoY decline but a 26.76% MoM gain; meanwhile, Flower contracted to 0.69% share with an 88.29% YoY drop and a 21.99% MoM decline, and Pre-Roll, though only 0.38% share, jumped 292.60% YoY and 566.87% MoM. With brand-wide sales down 49.19% YoY and average price down 14.40% YoY to $10.37, the pattern implies a pivot away from legacy Flower toward a two-pillar mix of Vapor Pens and Concentrates, with tactical experimentation in Pre-Roll despite its sub-1% footprint.
Positioning-wise, a 31 rank in Vapor Pens in Washington combined with a 26.76% MoM lift in Concentrates suggests Vapor Pens remain the volume anchor while Concentrates provide the near-term growth lever; the 1.89% MoM decline in Vapor Pens and 21.99% MoM drop in Flower indicate share defense is needed in inhalables, not expansion in Flower. The surge in Pre-Roll alongside a 49.74% YoY fall in Vapor Pens implies that low-price trial formats could help offset price compression, but the 0.38% share signals this should be a targeted tactic rather than a core shift.
Competitive Landscape
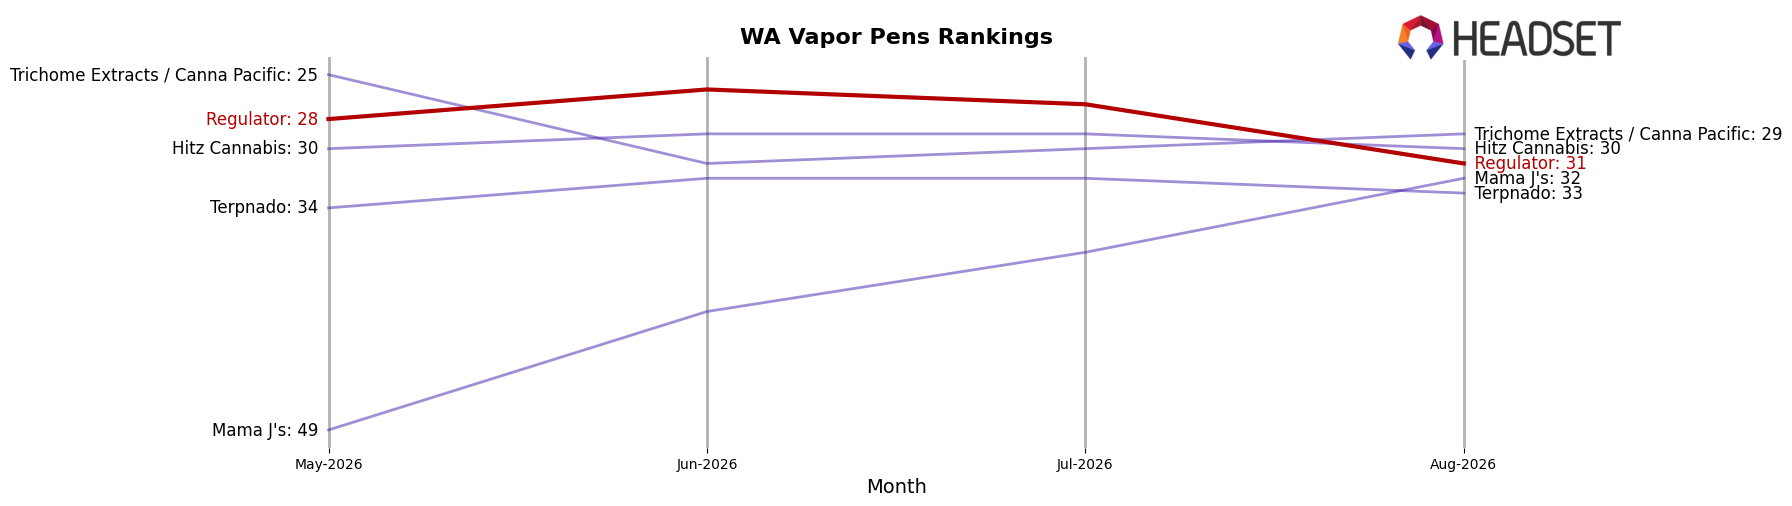
Regulator sits at rank #31 in Washington Vapor Pens in August 2026, down 16 places year over year from #15 and slipping 3 positions since May 2026 from #28, while still well below its peak of #9 last reached in August 2024; in contrast, Crystal Clear climbed from #3 to #1 and Mfused edged down from #1 to #2 with a 32.6% YoY sales decline, indicating that Regulator’s two-step slide since May 2026 and its 22-rank gap from its historical peak signal a transition from prior top-10 relevance toward lower-tier positioning unless share recapture accelerates.
Notable Products
The steepest movement worth leading with is the MoM surge for Pineapple Super Silver Haze Distillate Cartridge (1g), up 30.8% while holding rank 7, contrasted with Wedding Cake Distillate Cartridge (1g) up 16.6% at rank 5, indicating vapor pens are gaining traction versus flat-to-unknown trends in concentrates. At the same time, four of the top ten are Concentrates SKUs clustered at ranks 1–4, while Vapor Pens occupy ranks 5, 7, and 9, pointing to a split where cartridges grow faster in August 2026 as concentrates rely on rank stability over rate of change. The $12,519 in August 2026 sales for Wedding Cake Distillate Cartridge (1g) alongside rank gains in cartridges but not in wax implies assortment energy is tilting toward high-velocity vape formats. Taken together, the mix suggests Regulator is shifting commercial emphasis toward Vapor Pens for incremental growth while using Concentrates to anchor top ranks.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

