

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Simpler Daze is stocked at 111 licensed dispensaries across Michigan and Massachusetts, 73 of them in Michigan, with the deepest coverage in New Buffalo, Coldwater, Flint, Traverse City, and Ann Arbor. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
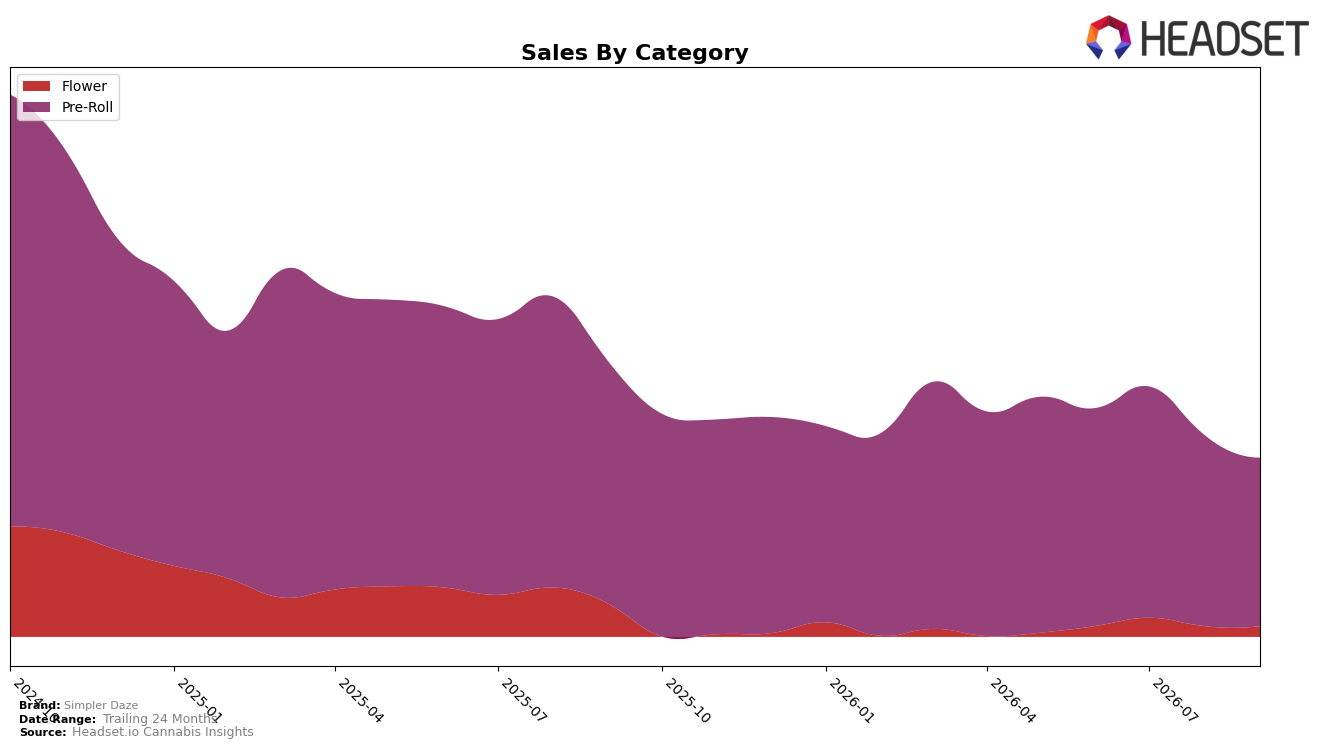
Simpler Daze’s mix in September 2026 is concentrated in Pre-Roll at 86.51% share while Flower holds 13.49%, with Pre-Roll down 28.33% YoY and 10.73% MoM and Flower down 43.45% YoY but nearly flat at 0.09% MoM decline. Average price fell 9.83% YoY to $6.43 alongside an overall brand sales decline of 30.82% YoY, and within Pre-Roll the category rank in Massachusetts sits at 14, indicating mid‑tier placement while share remains heavily skewed to one format. The pattern implies the brand is overly reliant on a shrinking Pre-Roll base for September 2026 and is not offsetting Pre-Roll’s double‑digit MoM contraction with stability in Flower, so the current mix concentration is amplifying downside volatility.
With Pre-Roll share above 80% and a 28.33% YoY decline paired with a 10.73% MoM slide, the category that defines Simpler Daze’s positioning is contracting faster than the brand can diversify, while Flower’s 43.45% YoY drop and negligible 0.09% MoM movement suggest limited headroom to rebalance. Holding rank 14 in Massachusetts while overall brand sales are down 30.82% YoY and average price is down 9.83% YoY signals that price cuts are not materially trading for volume, so maintaining a near‑monocategory focus keeps the brand anchored to mid‑pack placement rather than moving up the ranks; the implication is that mix breadth and price-pack architecture need recalibration to reduce sensitivity to Pre-Roll cycles.
Competitive Landscape
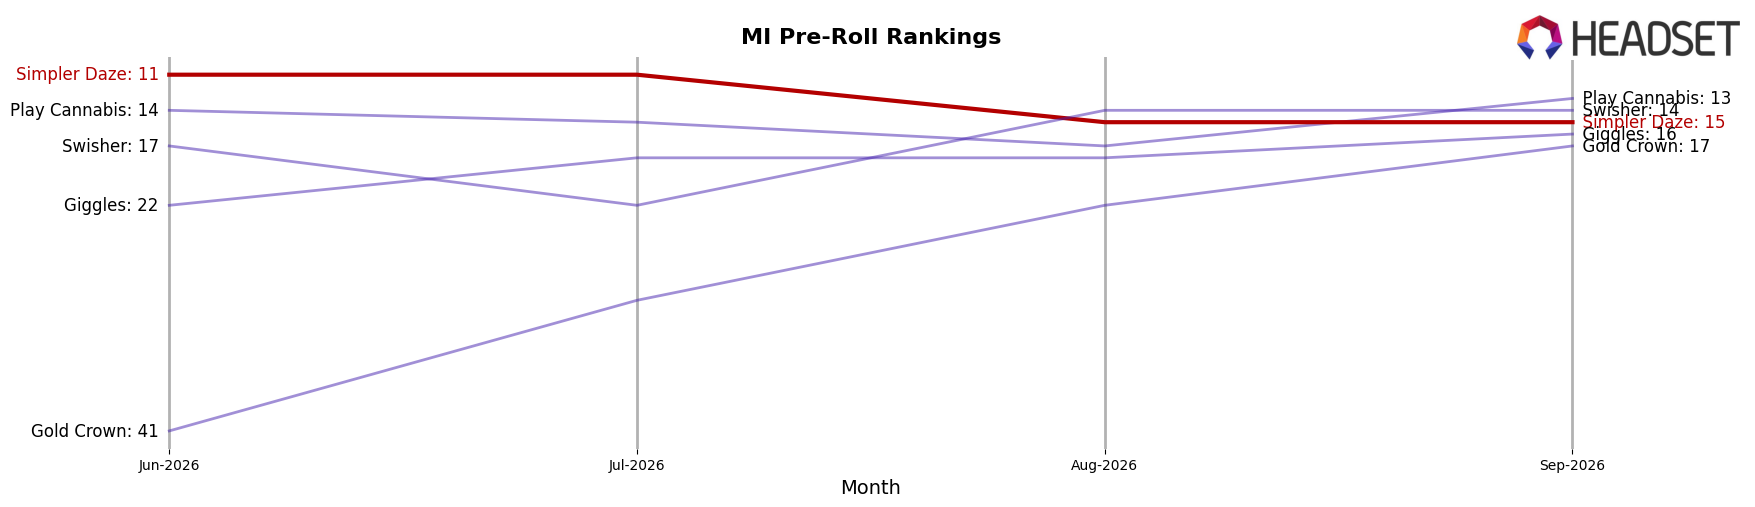
Simpler Daze sits at rank 15 in September 2026 in MI Pre-Roll, falling 7 positions year over year from rank 8 while slipping 4 spots from June 2026’s rank 11, a trajectory that contrasts with Jeeter holding rank 1 with a 149.9% YoY sales increase and Cali-Blaze steady at rank 2 despite a 36.1% YoY sales decline. The brand’s peak rank 6 in October 2024 is now 9 positions higher than its current standing, while Mitten Extracts edged up from rank 5 to rank 4 with a 1.9% YoY sales lift and Goodlyfe Farms slid from rank 4 to rank 5 alongside a 22.3% YoY sales drop. The pattern implies share is consolidating at the top: even as one top competitor posts a double-digit decline and another posts triple-digit growth, Simpler Daze’s downward rank drift suggests its mix is not capturing the velocity pockets driving September 2026’s leaderboard.
Notable Products
Fire Styxx - Blazing Star Infused Pre-Roll (1g) posted the steepest slide at -38.99% MoM while holding rank 10, alongside Fire Styxx - Grape Escape THCA Infused Pre-Roll (1g) at -32.99% MoM from rank 5. At the top, Fire Styxx - Unicorn Tears THCA Infused Pre-Roll (1g) fell -15.50% MoM yet remained rank 1, as Fire Styxx- Tigers Breath Infused Pre-Roll (1g) declined -21.13% at rank 4. This concentration of negative swings at both the top and tail implies the lineup is over-reliant on a few SKUs for volume and is exposed to volatility.
Offsetting the declines, Fire Styxx - Glitter Apples Infused Pre-Roll (1g) climbed +33.15% MoM to rank 6 and Fire Styxx - Midnight Berry THCA Infused Pre-Roll (1g) rose +9.34% MoM at rank 3, while Fire Styxx - Razzberry Diesel Infused Pre-Roll (1g) in rank 2 edged +2.31% MoM on $161,580 sales. Nine of the top ten are Pre-Roll SKUs, with two THCA-tagged leaders in ranks 1 and 3 anchoring mix share. The pattern points to a category-heavy strategy where incremental gains from mid-pack Pre-Rolls must counter sizable drops among leaders to stabilize September 2026 revenue.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

