

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
SKÖRD is stocked at 133 licensed dispensaries across Washington, with the deepest coverage in Seattle, Tacoma, Everett, Olympia, and Spokane. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
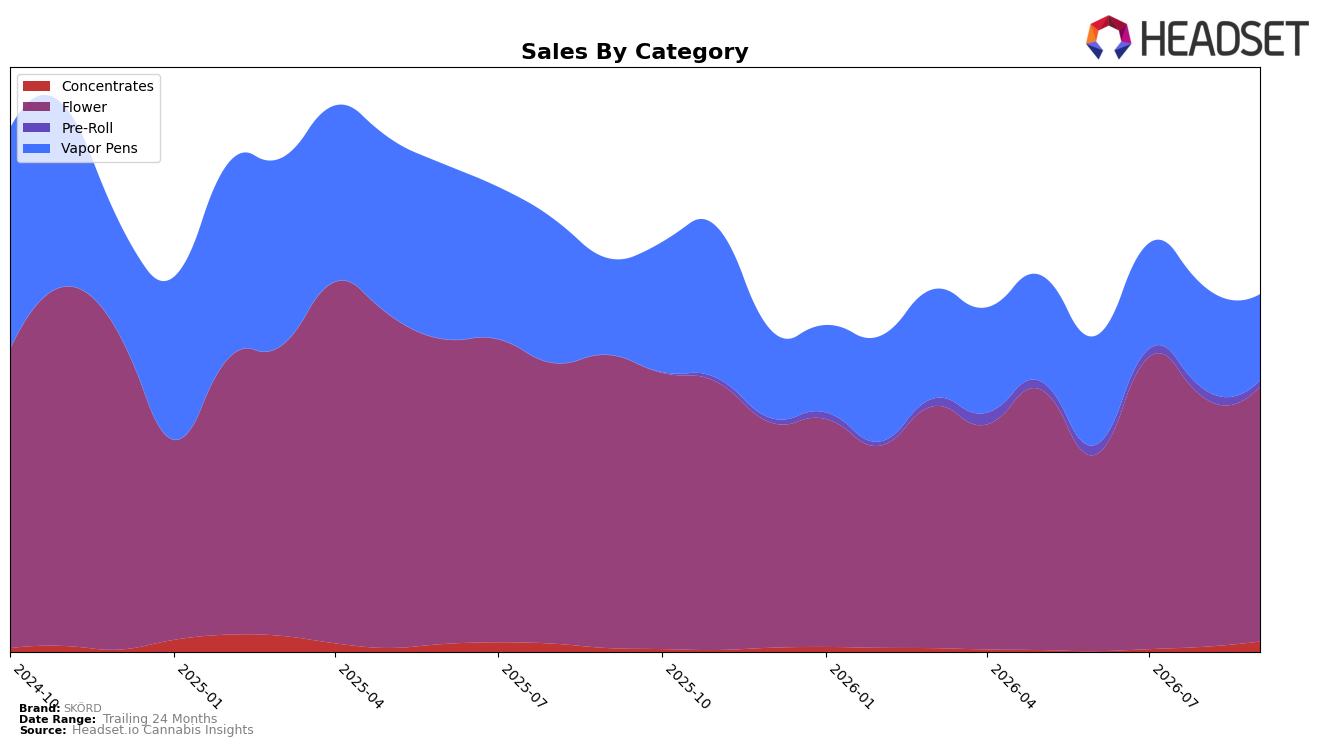
In September 2026, SKÖRD concentrated 71.42% of sales in Flower with a month-over-month gain of 2.65% but a year-over-year decline of 13.01%, while Vapor Pens held 24.10% share with a 16.15% MoM drop and a 10.70% YoY decline. Concentrates expanded to 2.83% share on 106.06% MoM and 184.94% YoY growth, and Pre-Roll slipped to 1.64% share with a 30.20% MoM decrease and no year-ago comp reported. Despite an average price up 2.35% YoY to $28.32, total brand sales fell 9.16% YoY and 30.57% versus 24 months, and within Washington Flower the brand ranked 24, implying reliance on a large but contracting anchor category while niche gains in Concentrates are too small in share to offset core headwinds.
The mix shift—stability-to-slight growth in Flower share alongside steep Vapor Pens contraction and outsized but low-base Concentrates gains—suggests SKÖRD is leaning into price-maintained core Flower positioning rather than chasing pen volumes, which may constrain velocity. With rank 24 in Washington Flower and Vapor Pens losing 16.15% MoM as Concentrates grow triple digits from a 2.83% base, the path to regain share likely depends on either elevating Flower rank by a few positions or reallocating toward faster-growing, higher-trajectory niches; the current pattern implies that without a 5–10% share reweight from Vapor Pens into Concentrates or Pre-Roll, overall momentum will mirror the -9.16% YoY brand trend.
Competitive Landscape
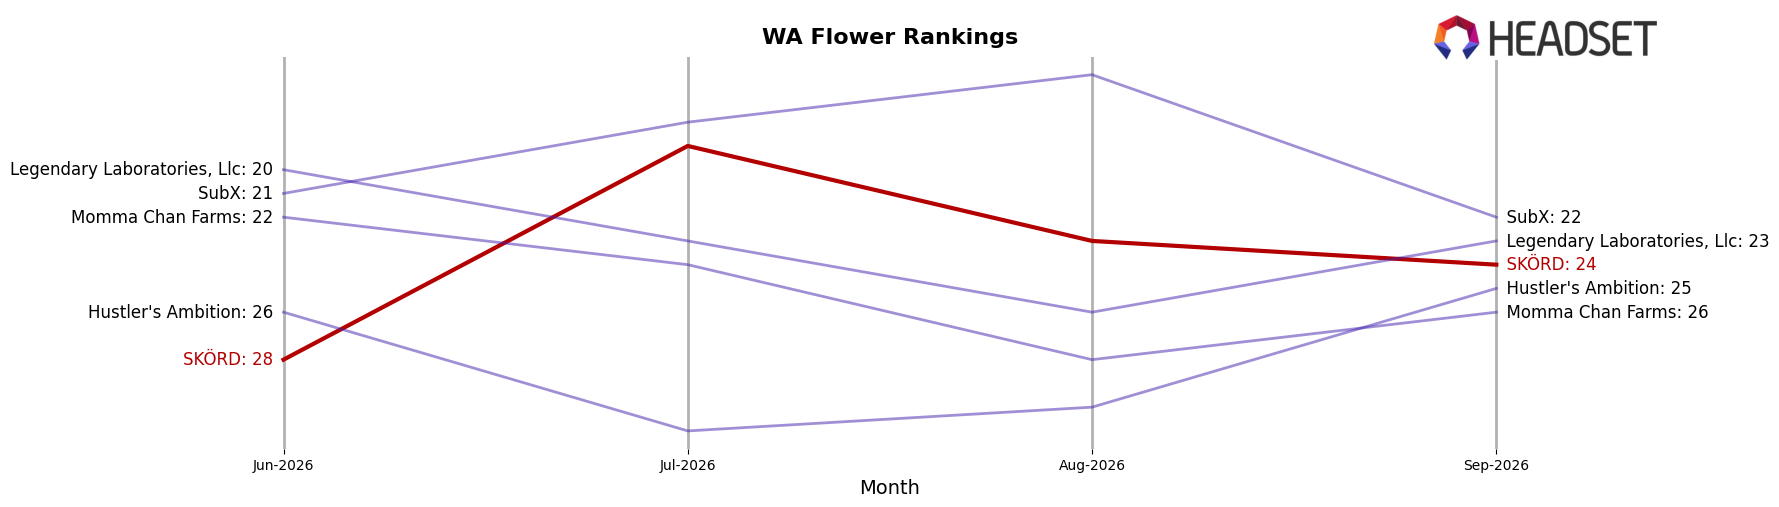
SKÖRD sits at rank #24 in WA Flower for September 2026, down 7 positions year over year from #17, yet up 4 places versus June 2026 when it was #28; compared with its peak of #14 in April 2025, the current slot is 10 ranks lower, while category leaders illustrate divergent momentum as Phat Panda holds #1 with +19.0% YoY sales and Legends holds #2 with −16.9% YoY sales, and challenger Hemp Kings surged from #24 to #5 with +105.1% YoY sales; the pattern of mid-year recovery (+4 ranks since June 2026) but a 7-rank YoY slide implies SKÖRD is stabilizing quarter-over-quarter while ceding longer-term share to faster-rising rivals.
Notable Products
Chocolate River (3.5g) delivered the standout movement with a +122% month-over-month surge to $21,020 and climbed to rank 1, while Lemon Shortbread (3.5g) fell -41% and settled at rank 6. Reserve - Modern Muse (3.5g) added +29% and reached rank 5, and three Vapor Pens in the top ten posted declines of -18% at rank 8 and -37% at rank 9, alongside a -4% at rank 10. With six of the top ten as Flower SKUs and the only triple-digit gainer coming from Flower, the mix points to SKÖRD tilting assortment and demand toward Flower over Vapor Pens in September 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

