

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Society C is stocked at 393 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Grand Rapids, Monroe, and Flint. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
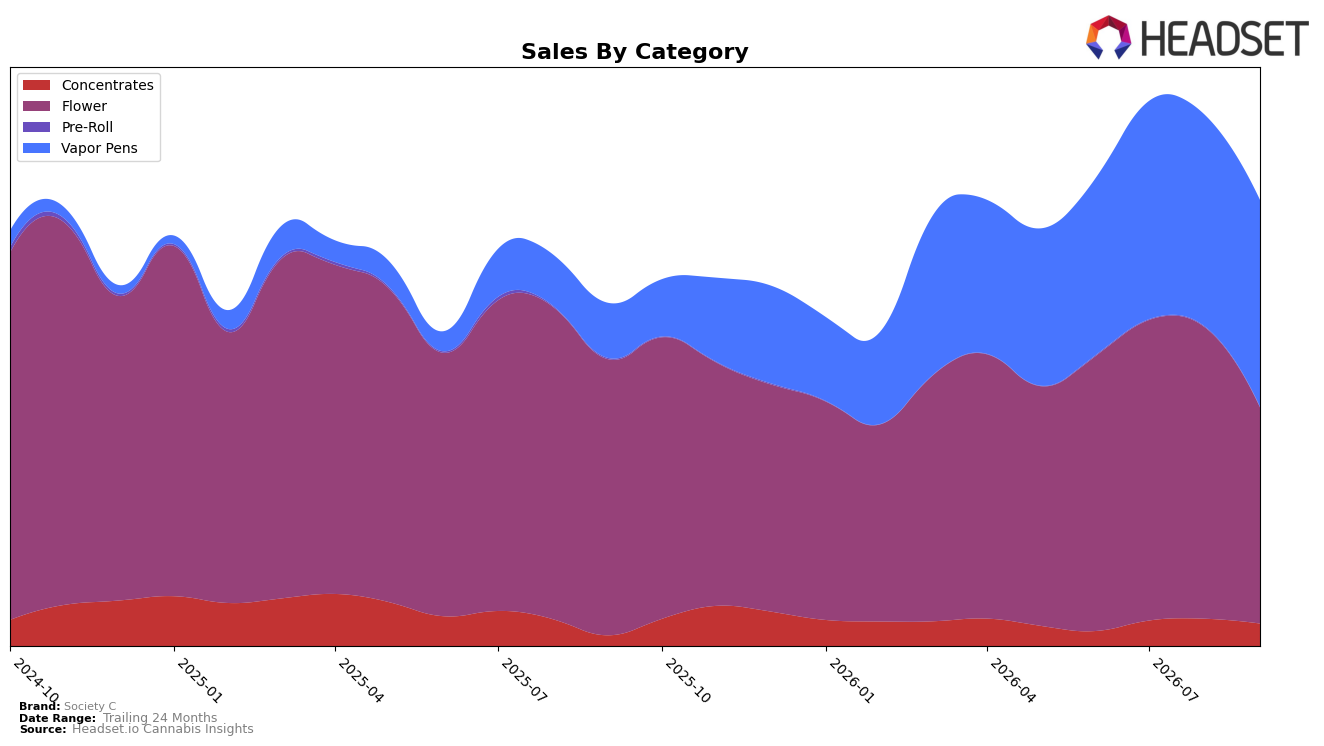
In September 2026, Society C’s mix pivoted toward Vapor Pens at 46.36% share while Flower held 48.45% share, with Flower down 21.74% year over year and 25.89% month over month and Vapor Pens up 276.17% year over year but down 2.29% month over month; the net effect was a brand-level year-over-year sales increase of 30.05% alongside a 4.57% rise in average price. Concentrates carried 5.08% share with 108.10% year-over-year growth but a 17.59% month-over-month decline, and Pre-Roll fell to 0.11% share with a 51.28% year-over-year drop and a 24.56% month-over-month decline; combined with a rank of 6 in Flower in Michigan, this pattern implies Society C is trading immediate Flower volume for higher-growth inhalables while absorbing near-term month-over-month pullbacks.
The shift toward Vapor Pens (+276.17% year over year) and Concentrates (+108.10% year over year), despite month-over-month softness of 2.29% and 17.59% respectively, implies a deliberate move into higher-priced, faster-scaling formats that support the 4.57% average price lift while Flower’s 21.74% year-over-year decline and 25.89% month-over-month drop lower mix risk in commoditized segments. With Flower still at 48.45% share and a category rank of 6 in Michigan, maintaining relevance in Flower while reallocating momentum to Vapor Pens at 46.36% share sets up a positioning where Society C can leverage pen-led velocity to buffer seasonal volatility and use Flower for distribution breadth rather than growth leadership.
Competitive Landscape
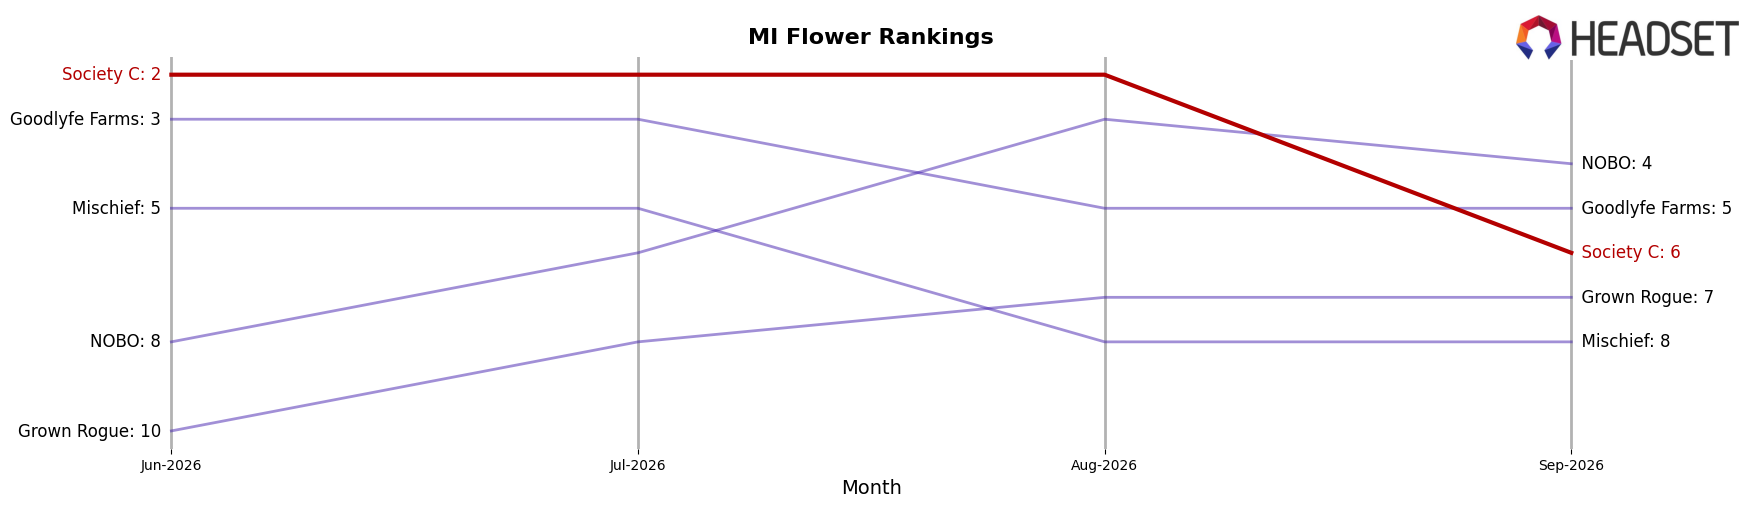
Society C sits at rank #6 in Michigan Flower for September 2026 after sliding 4 positions year over year from #2, and falling 4 spots since June 2026 when it also held #2; this contrasts with Play Cannabis rising from #9 to #2 year over year and NOBO jumping 19 places to #4 alongside a 188.3% YoY sales increase, while High Minded remains #1 despite a 3.3% YoY sales contraction and Goodlyfe Farms inching up 4 ranks to #5 with a 3.5% YoY sales decline; given Society C’s peak at #1 in January 2025 and the current #6 position amid competitors gaining share (e.g., Play Cannabis +7 ranks and Pro Gro +6 ranks), the trajectory implies market share is consolidating above Society C unless it reaccelerates velocity or assortment to counter upward movers.
Notable Products
Snow Cone Live Resin Disposable (2g) posted the steepest movement in September 2026 with a -23.6% month-over-month decline and slid to rank 10, while Blue Nerdz (3.5g) delivered the largest gain at +54.9% and climbed to rank 2. Gastro Pop (3.5g) retained rank 1 with +42.0% MoM and Omega Runtz (3.5g) advanced with +43.1% to rank 4, indicating concentrated momentum at the top. Eight of the top ten are Flower SKUs, and Vapor Pens account for two entries with one declining sharply and one lacking a reported MoM, suggesting portfolio strength is consolidating in Flower rather than in disposables. The mix implies Society C is leaning into high-velocity Flower formats to anchor share while Vapor Pens require selective SKU pruning rather than broad expansion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

