

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Spiked Flamingo is stocked at 20 licensed dispensaries across Nevada, with the deepest coverage in Las Vegas, Henderson, North Las Vegas, Elko, and Ely. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
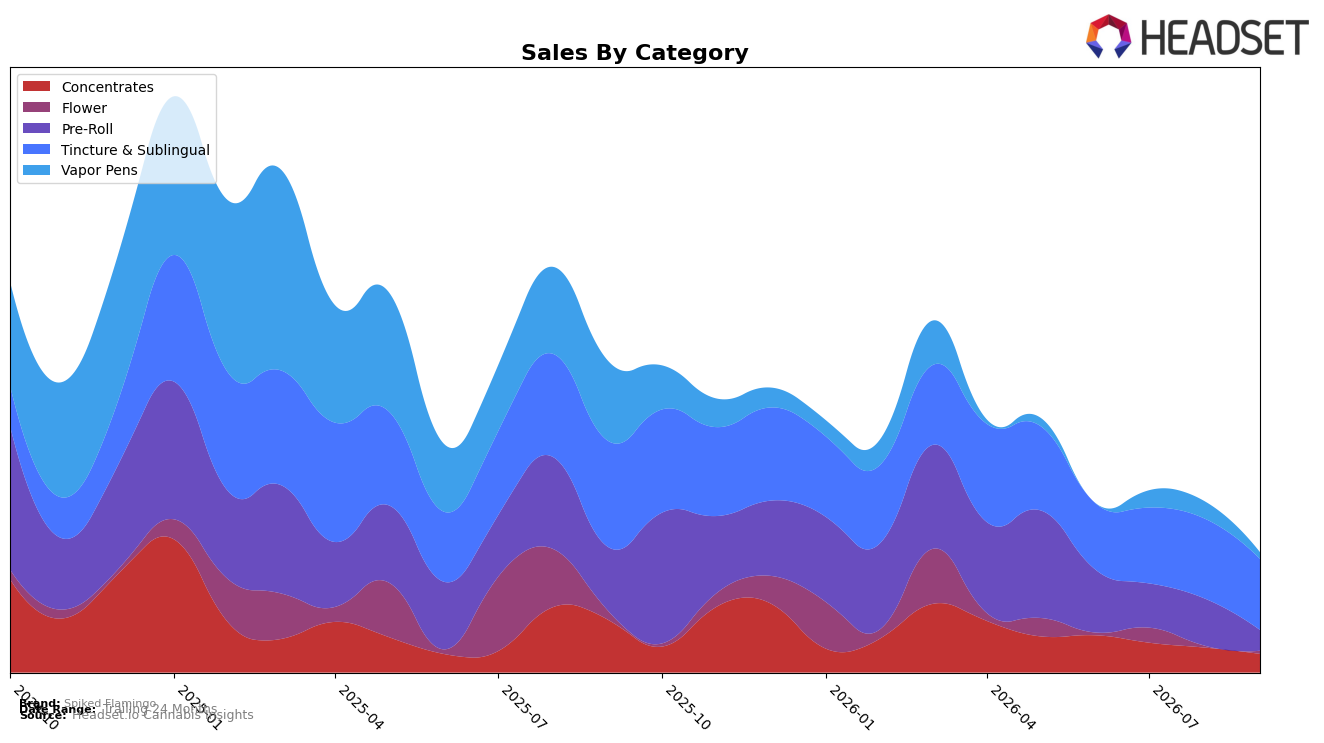
In September 2026, Spiked Flamingo concentrated 59.33% of sales in Tincture & Sublingual, where year-over-year declined 33.07% and month-over-month fell 11.07%, while Pre-Roll at 17.21% share contracted 67.72% YoY and 56.23% MoM. Concentrates held 15.51% share with a 64.71% YoY drop and 25.45% MoM decline, as Vapor Pens at 5.46% share deteriorated 91.83% YoY and 62.06% MoM; the outlier was Flower at 2.49% share, up 75.63% MoM despite a 65.88% YoY decrease. Average price dipped 0.18% YoY to $24.62 as category price points diverged (e.g., $53.15 in Vapor Pens vs. $14.42 in Pre-Roll), implying mix pressure is amplifying volume losses more than pricing. Ranking second in Tincture & Sublingual in Nevada alongside a 33.07% YoY decline suggests leadership is anchored in a shrinking core, concentrating risk if adjacent categories continue double-digit MoM declines.
The shift toward a heavier Tincture & Sublingual reliance, paired with steep MoM drawdowns in Pre-Roll (-56.23%) and Vapor Pens (-62.06%), implies September 2026 positioning skewed to a niche format rather than a balanced multi-format portfolio; the 75.63% MoM rebound in Flower from a 2.49% base is too small to offset that skew. With overall brand sales down 61.54% YoY and the 24-month trend down 58.25%, the mix suggests a need to defend the No. 2 rank in Tincture & Sublingual while re-evaluating underperforming inhalables where share is thin (5.46% in Vapor Pens and 17.21% in Pre-Roll). The combined pattern of mild pricing deflation (-0.18% YoY) and broad double-digit volume declines indicates demand leakage rather than price-driven elasticity, implying the brand’s near-term upside depends more on reactivating units in secondary categories than on further price moves in the core.
Competitive Landscape
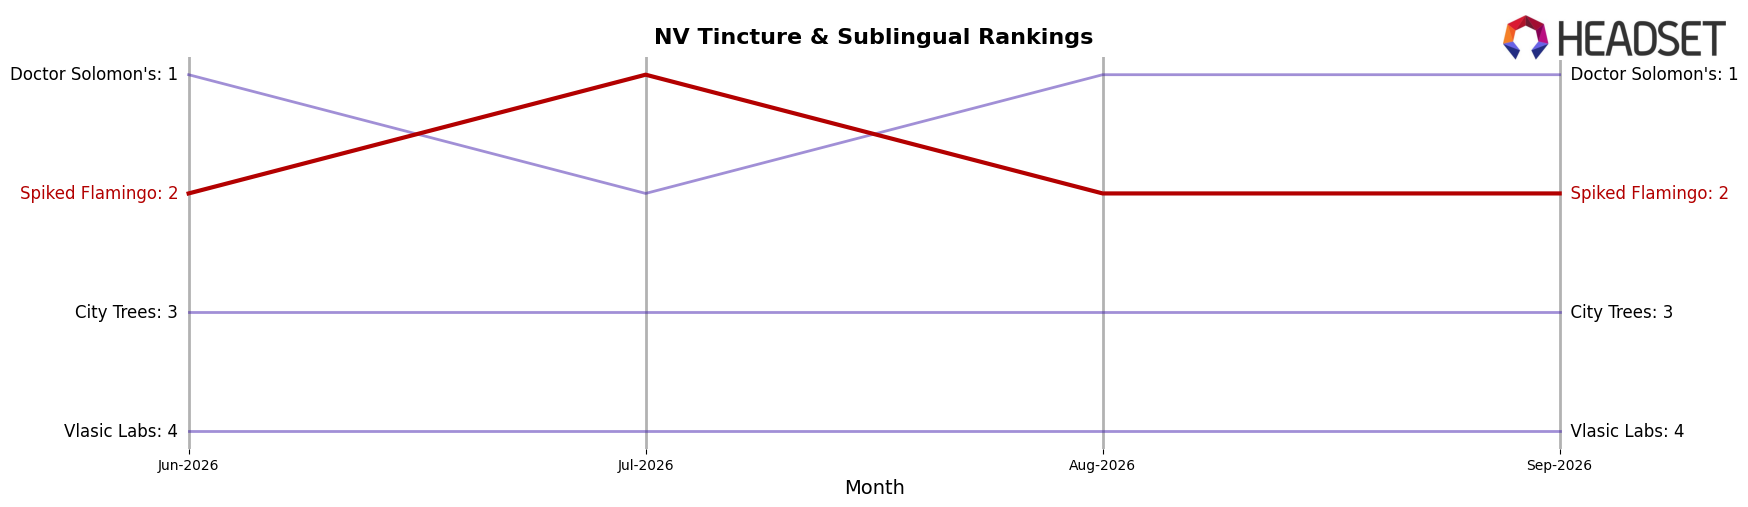
Spiked Flamingo is ranked #2 in NV Tincture & Sublingual for September 2026, down 1 position year over year but unchanged from June 2026 at #2, and it previously peaked at #1 in July 2026; meanwhile, Doctor Solomon's moved from #2 to #1 with a 73.99% year-over-year sales increase while City Trees held at #3 with a 4.57% lift, indicating that Spiked Flamingo’s slip from #1 to #2 alongside a competitor’s upward shift implies a stable near‑lead that now depends on recapturing momentum against a faster-rising leader.
Notable Products
Green Apple Tincture (800mg) posted the steepest movement in September 2026 with a -48.41% MoM slide and a tie at rank 9, while Bubblegum Tincture (800mg) followed with a -39.26% MoM drop at rank 9, signaling flavor-forward 800mg tinctures are losing pull against functional or value cues. Unflavored Tincture (800mg) climbed 8.22% MoM to rank 2 and NYC Diesel Infused Pre-Roll (1g) rose 6.98% MoM to hold rank 1, and five of the top ten are Tincture & Sublingual SKUs, pointing to concentration but with diverging trajectories inside the segment. With Watermelon Tincture (800mg) down 30.13% MoM at rank 8 and CBD:THC 1:1 Anytime Blue Agave Tincture (500mg CBD, 500mg THC) up 24.12% MoM at rank 5, the mix indicates a pivot from flavored 800mg tinctures toward unflavored and ratioed formulations. The pattern implies Spiked Flamingo is tilting toward efficacy-led tinctures and stable infused pre-rolls, reallocating emphasis away from flavored 800mg variants as shoppers prioritize function and familiarity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

