

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
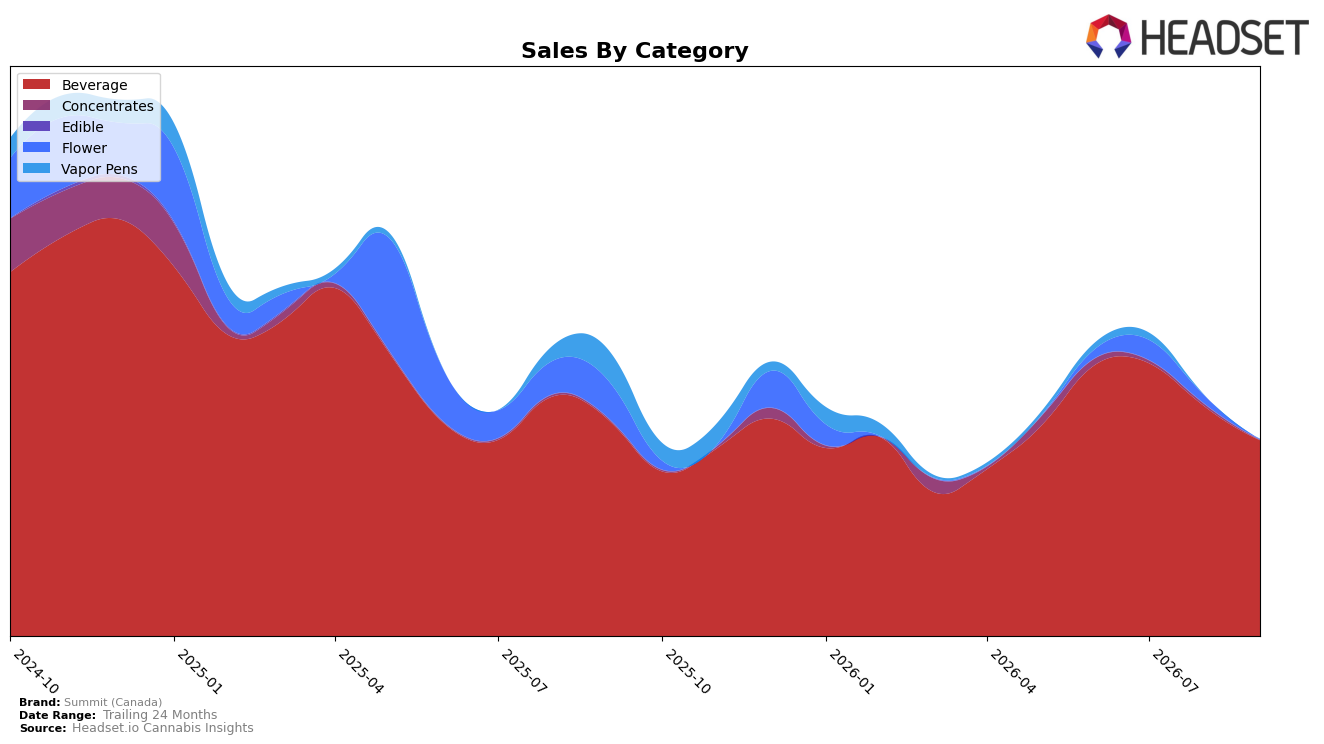
In September 2026, Summit (Canada) concentrated entirely in Beverage, with category share at 100.0% and a rank of 11 in Beverage within Alberta. Within this single-category footprint, Beverage sales fell 9.47% year over year and 14.69% month over month, while the brand’s overall sales declined 31.28% year over year and averaged price rose 8.12%. With average price at $7.11 against a 24‑month sales decline of 74.95%, the pattern implies a narrow, price-lifted mix that is not offsetting volume contraction, concentrating exposure to single-category volatility in Alberta.
The full reliance on Beverage at 100.0% share and a rank position of 11 indicates mid‑tier placement where month-over-month declines of 14.69% stack unfavorably against a 9.47% year-over-year dip, suggesting accelerating recent softness rather than a slow drift. Given overall brand sales down 31.28% year over year alongside an 8.12% average price increase, the mix skews toward price‑dependent revenue per unit rather than breadth or frequency, implying that Summit (Canada)’s positioning is tethered to Beverage price dynamics and rank mobility in Alberta rather than diversification or cross‑category insulation.
Competitive Landscape
Summit (Canada) sits at #11 in AB Beverage as of September 2026, slipping 1 position YoY from #10 and holding flat versus three months ago at #11, while its historical peak of #9 in May 2025 marks a 2-rank drop from that high; in contrast, XMG holds #1 but carries a -40.0% YoY sales decline and Mary Jones climbed from #4 to #2 with +97.6% YoY growth, indicating Summit is losing relative momentum despite top-tier volatility and a challenger accelerating upward, which implies the current rank trajectory risks cementing a mid-tier position unless mix or activation shifts reclaim at least 2 ranks back toward the prior #9 peak.

Notable Products
Clementine Crush Seltzer (10mg THC, 355ml) posted the largest move in September 2026 with +110.3% MoM, yet it held only rank 4 while Pink Lemonade (10mg THC, 12oz, 355ml) stayed at rank 1 despite a -8.6% MoM dip. Lemonade Iced Tea (10mg THC, 355ml) fell -25.9% MoM at rank 2, and Apple Pie Iced Tea (10mg THC, 355ml) collapsed -65.4% MoM at rank 6, indicating volatility concentrated in flavored extensions while the lead SKU softens. With four of the top five ranked items in September 2026 showing negative MoM changes between -6.4% and -65.4%, the category mix is tilting toward fewer, higher-velocity bets rather than broad seasonal variety. The pattern implies Summit (Canada) is consolidating around a flagship core while testing niche innovations that can spike but have not yet converted into top-tier ranks, pointing to a need for rotation discipline and sustained support for the highest-ranked beverage SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

