

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
SUNDAY is stocked at 124 licensed dispensaries across Michigan, New Jersey, and 4 other states, 75 of them in Michigan, with the deepest coverage in Grand Rapids, New Buffalo, Coldwater, Houghton, and Ironwood. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
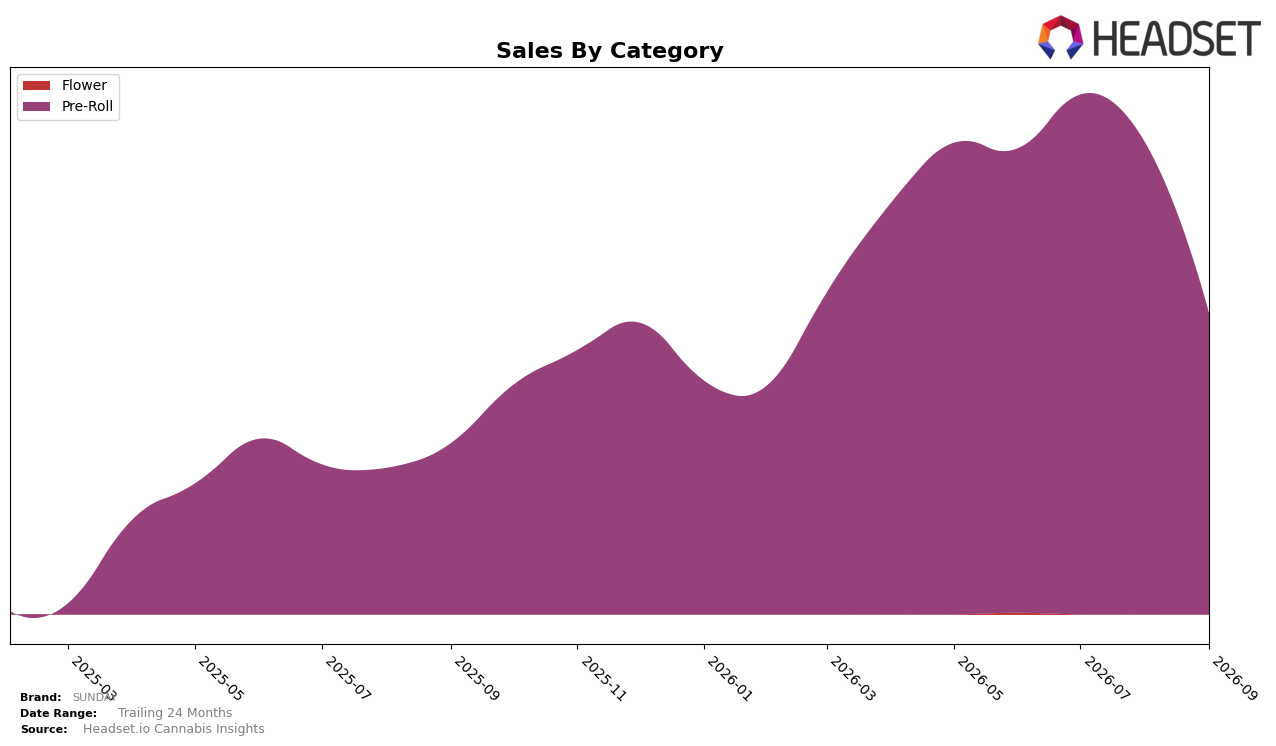
In September 2026, SUNDAY’s category mix was fully concentrated in Pre-Roll at 100.0% share, with Pre-Roll sales up 75.79% year over year while declining 36.39% month over month, and the brand’s average price fell 61.81% YoY alongside a placement at rank 18 in New Jersey. This pattern implies a deliberate volume-over-price strategy: the steep YoY price compression paired with a 75.79% YoY sales increase and a single-category focus at 100.0% suggests SUNDAY is trading margin for penetration, even as the 36.39% MoM pullback and rank 18 positioning point to sensitivity to monthly demand shifts within Pre-Roll.
The sustained 100.0% exposure to Pre-Roll and a 61.81% YoY price decline signal a positioning anchored in value-led, high-velocity offerings, which helps explain rank 18 despite a 75.79% YoY sales lift. With MoM sales down 36.39% against stable category concentration at 100.0%, SUNDAY’s near-term risk is over-reliance on price elasticity; the thesis is that maintaining volume at lower price points can defend share in New Jersey, but the current rank 18 and a single-category footprint indicate limited insulation against monthly volatility.
Competitive Landscape
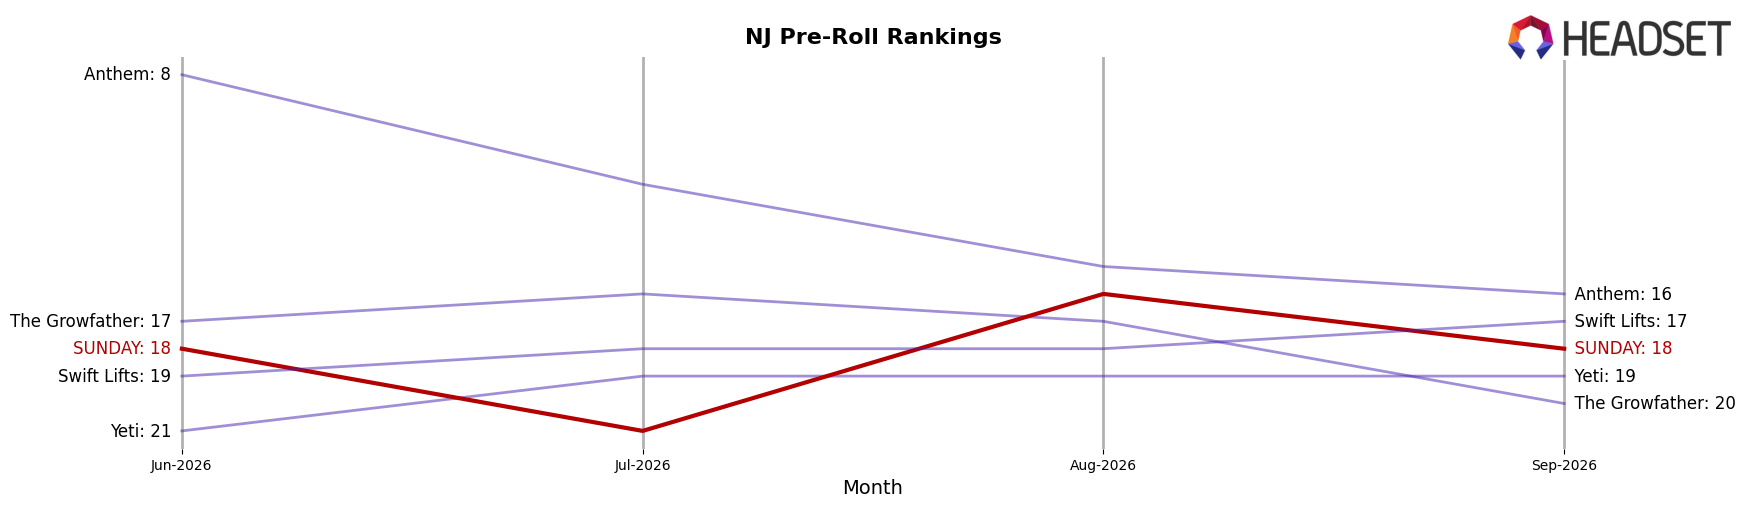
SUNDAY ranks #18 in NJ Pre-Roll as of September 2026, flat versus June 2026 at #18, with a peak of #16 in August 2026 suggesting a 2-position retreat month over month; meanwhile, RYTHM advanced to #1 with a 3-position YoY climb and 50.7% sales growth, and Ozone sits at #2 after a 6-position YoY rise and 81.1% sales growth, while Lowell Herb Co / Lowell Smokes holds #3 despite a 2-position YoY gain alongside a -34.4% sales decline; the combination of SUNDAY’s static three‑month rank and brief August peak implies a ceiling effect where incremental gains are being outpaced by faster-moving leaders, requiring either mix shifts or pricing moves to break out of the #16–#18 band.
Notable Products
Rose Pop Pre-Roll (1g) posted the steepest movement in September 2026 with a -60.1% month-over-month drop while holding rank 5, contrasting with Blue Dream Pre-Roll (1g) at rank 8 with a -30.1% decline and Josey Whales Pre-Roll 25-Pack (25g) at rank 7 growing +8.8%. Oreoz Pre-Roll (1g) led the lineup at rank 1 and Lemon Cherry Gelato Pre-Roll (1g) followed at rank 2, and eight of the top ten SKUs were Pre-Roll formats including two 25-pack bulk offerings, indicating concentration in a single category. Guava Tart Pre-Roll (1g) landed at rank 3 while Donny Burger Pre-Roll 25-Pack (25g) sat at rank 10 with $34,598 in sales, framing a spread where single-gram SKUs bookend with bulk packs in the top ten. The mix implies SUNDAY is leaning into Pre-Roll dominance with a barbell between lead single-gram flagships and value-driven 25-packs, prioritizing breadth within one format over diversification.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

