

Jul-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
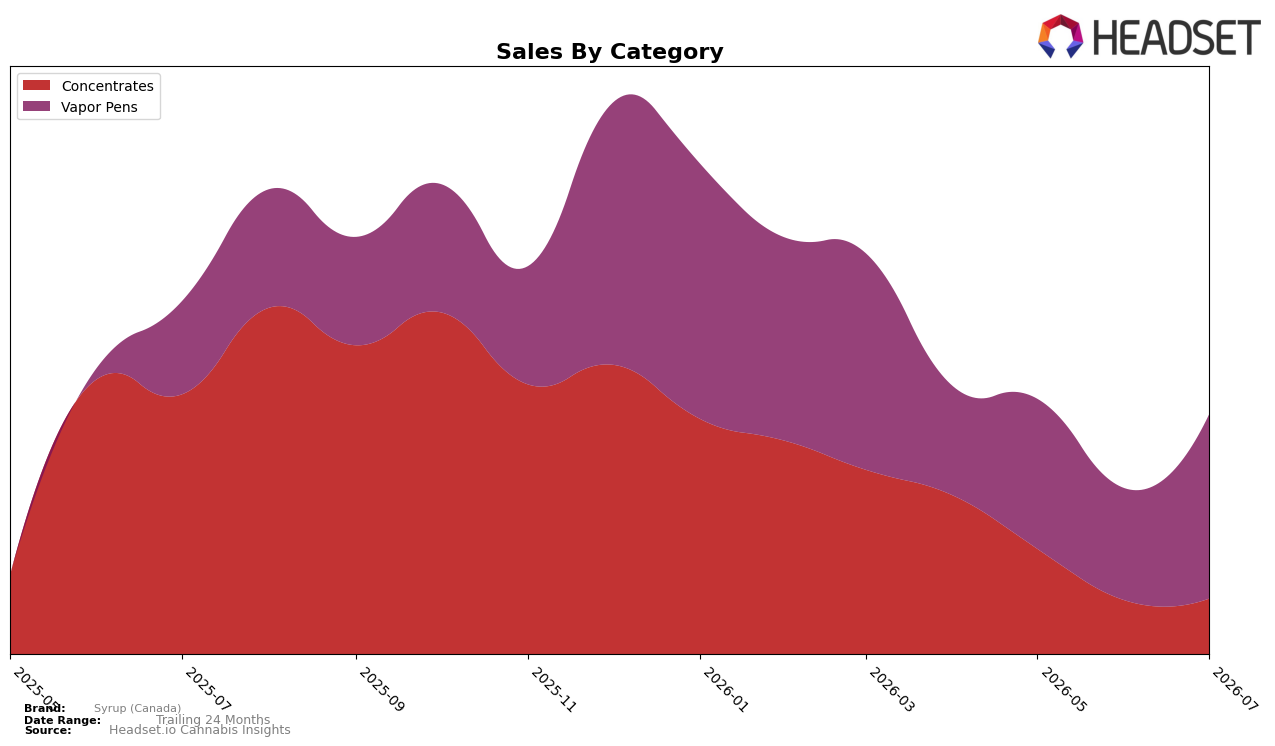
In July 2026, Syrup (Canada) concentrated 76.87% of sales in Vapor Pens, up with category sales rising 98.41% year over year and 64.58% month over month, while Concentrates fell to 23.13% share with sales down 78.68% year over year despite a 3.07% month-over-month uptick. The average price climbed 57.08% year over year to $36.96 as Vapor Pens priced at $42.81 outweighed Concentrates at $25.43, and the Vapor Pens focus coincided with a brand-level sales decline of 32.08% year over year, implying mix expansion did not offset absolute unit contraction. The pattern implies Syrup (Canada) is leaning into higher-priced Vapor Pens to stabilize revenue, but the magnitude of the Concentrates contraction and the gap between +98.41% category growth and -32.08% brand sales suggests a shrinking shopper base or tighter distribution that mix alone cannot counter.
The shift toward Vapor Pens at 76.87% share alongside a rank of 81 in Vapor Pens in Alberta indicates category dependence without category leadership, and the 64.58% month-over-month Vapor Pens growth versus only 3.07% in Concentrates suggests near-term allocation should prioritize pen assortment over extract breadth. With Concentrates down 78.68% year over year while Vapor Pens pricing sits 68.4% above Concentrates, the brand’s elevated price architecture increases revenue per unit but risks price elasticity if distribution widens; the implication is that sustained recovery will require converting Vapor Pen trial into repeat at the higher price point while treating Concentrates as a margin-light feeder or exit candidate depending on July 2026 retention signals.
Competitive Landscape
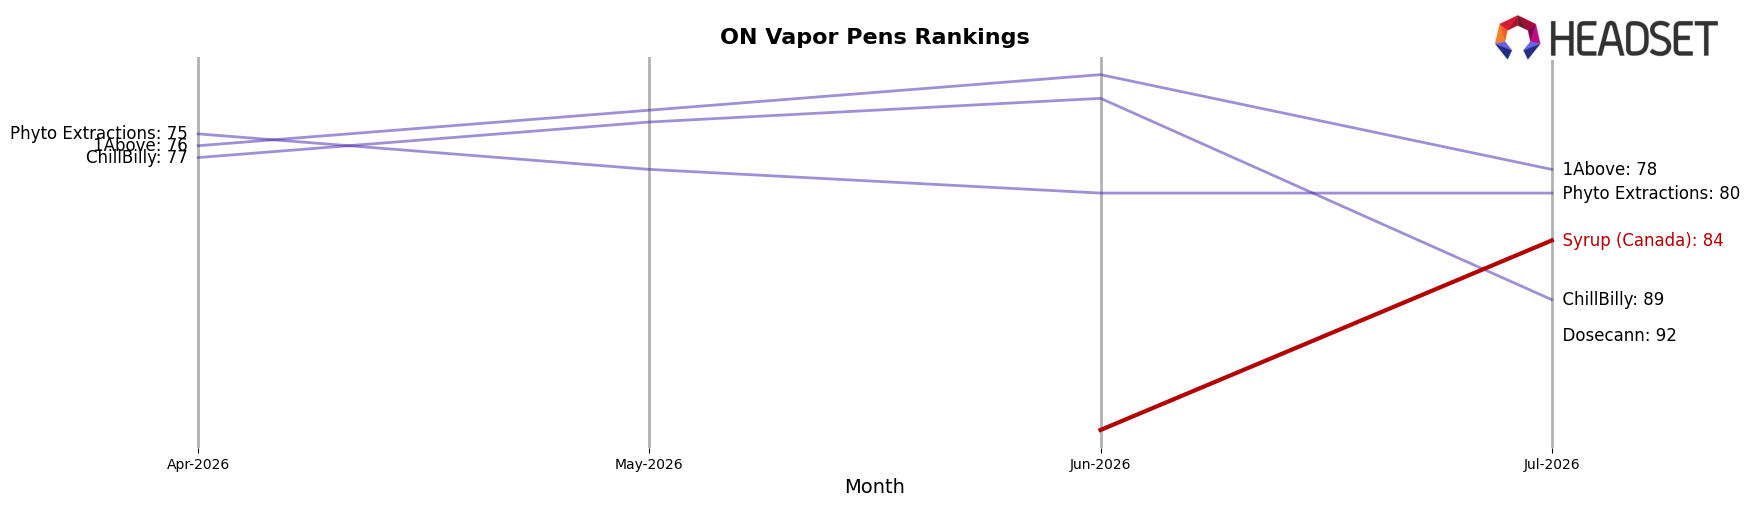
Syrup (Canada) sits at rank #84 in ON Vapor Pens in July 2026, improving 11 positions from #95 year over year and rising 34 spots from #118 in April 2026, while still one place off its December 2025 peak at #83; meanwhile, Spinach climbed from #4 to #1 with 144.7% YoY sales growth and General Admission slipped from #3 to #4 with a -19.0% sales change, indicating that Syrup (Canada)’s gradual rank recovery amid top-tier volatility points to a path of incremental share capture if momentum from April 2026 to July 2026 can be sustained.
Notable Products
Zuper Kush Live Terp Cartridge (2g) posted the largest month-over-month gain at +127% while debuting inside the top five at rank 5, whereas Chem Bomb Live Terp (1g) slipped -9.8% to rank 3, signaling a rotation away from legacy concentrate leaders. Little Tokyo Live Resin Terp Cartridge (2g) surged +94% to rank 1, and Little Tokyo Live Terp Dab (1g) jumped +68% to rank 4, concentrating momentum around the Little Tokyo strain across both Vapor Pens and Concentrates. With three Vapor Pens in the top five and Concentrates split between a rising Little Tokyo and a declining Chem Bomb, the mix tilts toward higher-velocity cartridges even as select dabbable formats catch up. The pattern implies Syrup (Canada) is consolidating demand into a few strain-led Vapor Pen SKUs while pruning or repositioning weaker Concentrates to capture faster-turn segments.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

