

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
TFC (The Flower Collective LTD) is stocked at 123 licensed dispensaries across Colorado, with the deepest coverage in Denver, Colorado Springs, Boulder, Durango, and Aurora. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
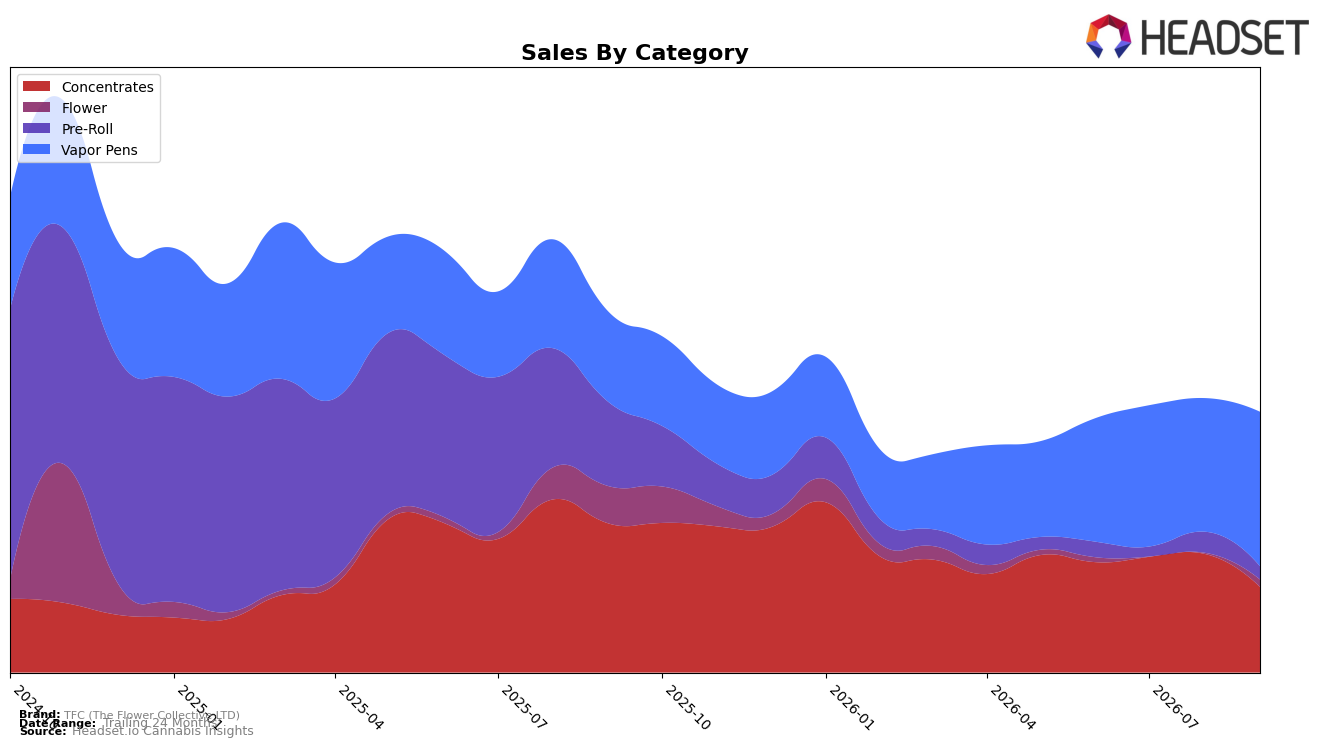
In September 2026, TFC (The Flower Collective LTD) concentrated sales into Vapor Pens at 59.17% share with year-over-year growth of 70.78% and month-over-month growth of 15.58%, while Concentrates slipped to 32.82% share with a year-over-year decline of 42.57% and a month-over-month decline of 27.81%. Pre-Roll contracted to 5.12% share with year-over-year decline of 84.14% and month-over-month decline of 36.76%, as Flower held 2.89% share but surged month-over-month by 502.40% despite a year-over-year decline of 79.83%. This shift implies a deliberate pivot toward Vapor Pens as the primary revenue engine, using a price-led strategy with the brand’s overall average price down 4.71% year-over-year alongside a category where the average price sits at $50.14.
The mix shift supports a positioning that trades breadth for depth: Vapor Pens growth of 70.78% year-over-year offsets steep declines of 42.57% in Concentrates and 84.14% in Pre-Roll, while the 502.40% month-over-month rebound in Flower likely reflects tactical assortment or distribution recovery rather than a structural share driver at 2.89%. With brand sales down 27.75% year-over-year despite Vapor Pens gains and an average price decrease of 4.71%, the implication is margin pressure in lower-priced segments (e.g., Concentrates at $28.10 average price) while leaning into a higher-priced anchor, positioning the brand to compete on value within premium-leaning form factors rather than chasing volume across shrinking categories.
Competitive Landscape
TFC (The Flower Collective LTD) sits at rank #43 in CO Vapor Pens in September 2026, improving 12 places from #55 year over year and gaining 4 spots from #47 since June 2026; this is also a peak rank of #43 for September 2026, indicating upward momentum while still outside the top 40. In contrast, Spherex held steady at #1 year over year, and PAX climbed from #3 to #2 alongside a 34.7% YoY sales increase, while Jetty Extracts jumped from #15 to #4 with 150.9% YoY sales growth; relative to these gains, TFC’s ascent is rank-driven rather than share-seizing, suggesting recent improvements may owe more to mid-tier churn than to outsized demand capture. The rank trajectory implies TFC is moving into contention but must convert rank gains into higher share to avoid flattening below the top 30.

Notable Products
Truffle Runtz (Bulk) surged 503% month over month to rank 1 in September 2026, while Bubblegum Marker Bubble Hash (1g) fell 61% to rank 10, signaling a sharp tilt from Concentrates into Flower at the very top of the chart. Vapor Pens occupied ranks 2, 4, 7, 8, and 9, with Goji OG Live Rosin Cartridge (1g) dropping 43% to rank 7 and Hot Mint Sunday Live Rosin Cartridge (1g) sliding 7% to rank 9, indicating mixed traction inside a concentrated pen lineup that still controls half of the top ten. Mitch's Wreck Bubble Hash (1g) rose 14% to rank 3 as Peach Pit Live Rosin Cartridge (1g) advanced 40% to rank 4, and one SKU crossed the $15,000 mark, pointing to momentum in premium formats even as volatility persists in select rosin SKUs. Together, the outsized Flower leap and uneven pen performance imply TFC (The Flower Collective LTD) is pivoting shelf space toward high-velocity Flower while refining a wide pen portfolio for steadier repeat demand.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

