

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
RVRS is stocked at 55 licensed dispensaries across Colorado and Arkansas, 54 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Boulder, Grand Junction, and Basalt. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
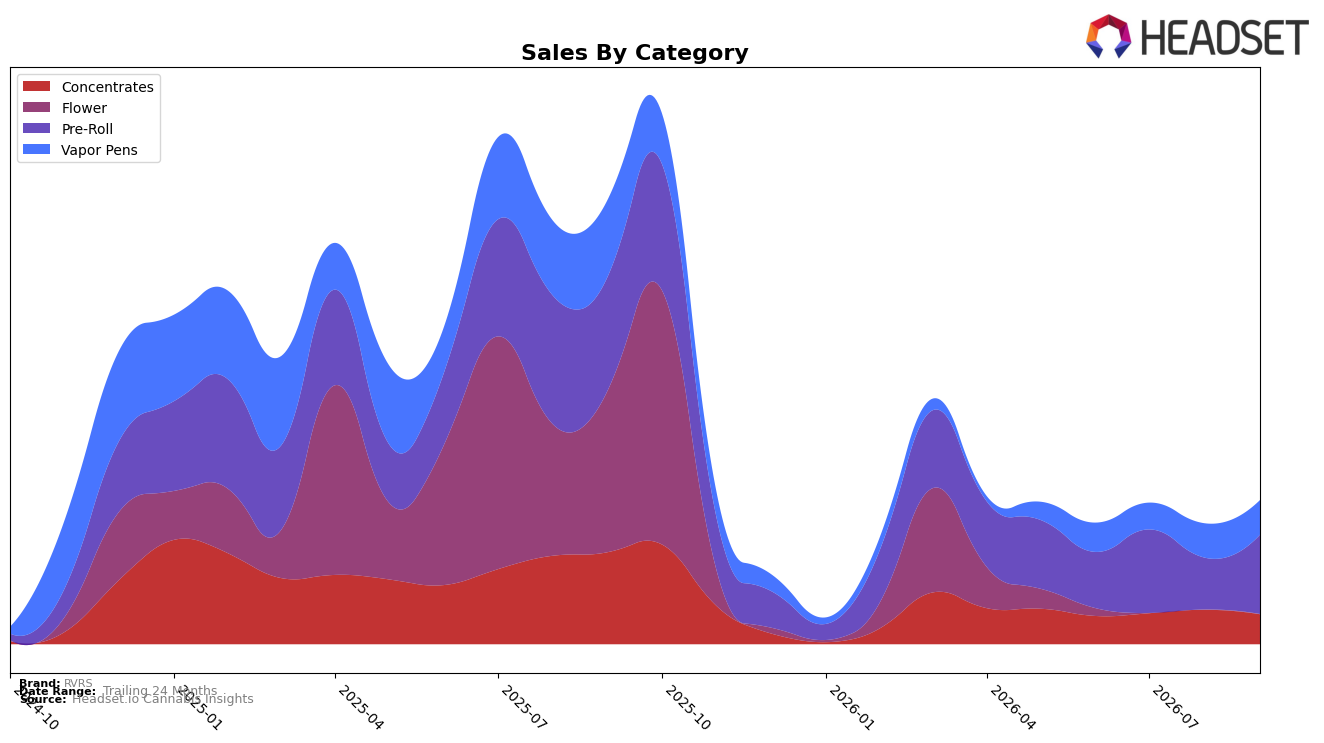
RVRS concentrated 55.19% of sales in Pre-Roll during September 2026, up 53.10% month over month but down 30.45% year over year, while Vapor Pens held 24.02% share with a 0.78% MoM uptick and a 55.12% YoY decline. Concentrates accounted for 20.79% share, contracting 13.05% MoM and 67.62% YoY, as the brand’s overall sales fell 67.80% YoY despite a 321.86% gain over 24 months. Average price rose 198.09% YoY to $28.05, with Pre-Roll pricing at $23.38 and Vapor Pens at $46.30, and RVRS sat at rank 43 in Pre-Roll in Colorado. The pattern indicates a tactical pivot toward Pre-Roll as the volume anchor, using category mix shifts and selective price elevation to stabilize near-term share while accepting contraction in Concentrates.
The mix realignment implies RVRS is prioritizing accessibility and basket-frequency via Pre-Roll, using a 53.10% MoM surge and 55.19% share to offset deeper declines of 67.62% YoY in Concentrates and 55.12% YoY in Vapor Pens. With average prices up 198.09% YoY yet Pre-Roll pricing sitting below the brand average at $23.38, RVRS is likely using tiered pricing to defend rank 43 in Pre-Roll in Colorado while de-emphasizing higher-ticket but contracting formats. This positioning suggests near-term share recovery will depend on sustaining Pre-Roll momentum and selectively reallocating assortment from underperforming Concentrates, rather than broad-based discounting across categories.
Competitive Landscape
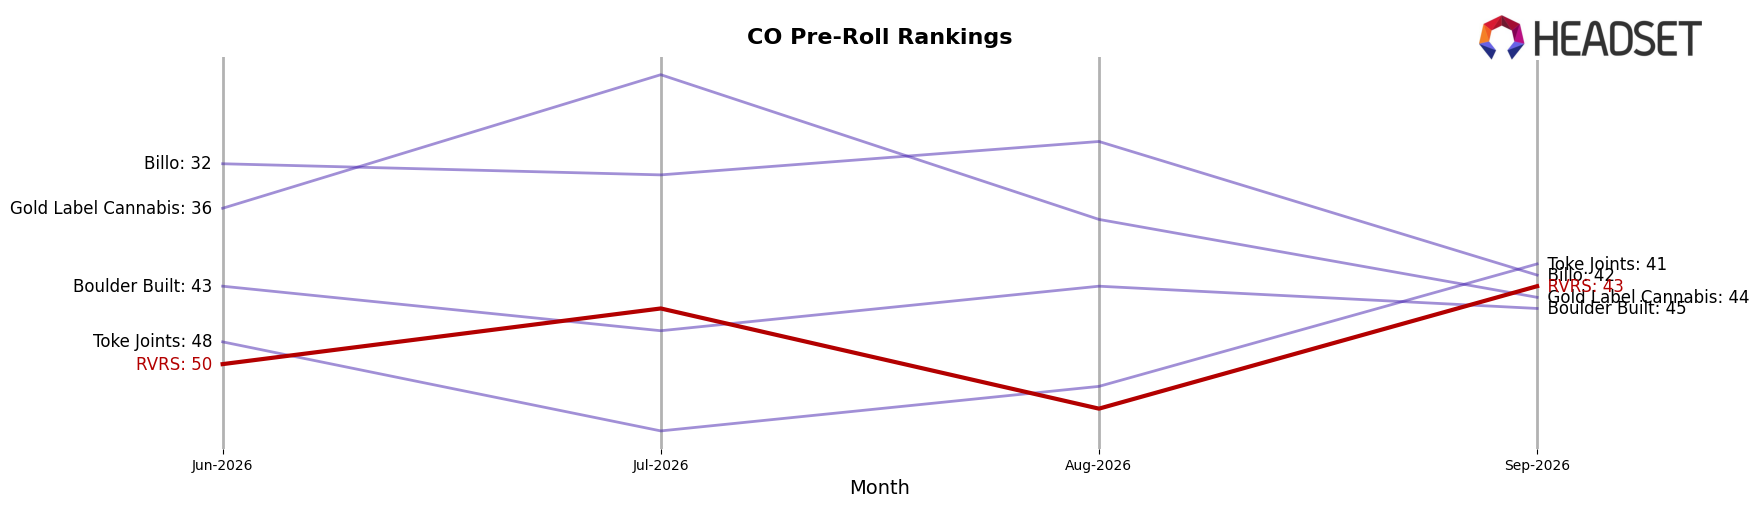
RVRS sits at rank #43 in Colorado Pre-Roll for September 2026, sliding 10 spots year over year from #33 and easing 7 places since June 2026 from #36 to #43, while its historical peak was #27 in February 2025. In directional contrast, Cali-Blaze climbed from #2 to #1 with sales up 67.2% year over year, and Be One Kind surged from #22 to #4 alongside a 463.7% sales increase; meanwhile, Kaviar edged down from #4 to #5 with sales down 5.0%. The pattern—downward rank movement over both the year (-10) and the last three months (-7) against competitors that are rising—implies RVRS is ceding relative shelf position and must either reprice or refresh assortment to arrest share erosion.
Notable Products
Roobies - Snacks Rosin Infused Pre-Roll 3-Pack (1.5g) posted the largest month-over-month surge at 92.8% and secured rank 1, while Banana Shack Live Rosin (1g) rose 73.6% to rank 7. Roobie - Indica Rosin Infused Pre-Roll (2g) gained 50.0% and reached rank 2, whereas Roobie - Sativa Rosin Infused Pre-Roll (1.5g) slipped 2.5% at rank 6. With eight of the top ten in Pre-Roll formats and only one Concentrates SKU in the top seven, the mix points to RVRS leaning into infused Pre-Roll velocity while treating Concentrates as a secondary growth lane.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

