

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
(the) Essence is stocked at 533 licensed dispensaries across Illinois, New Jersey, and 9 other states, 130 of them in Illinois, with the deepest coverage in Chicago, Normal, Quincy, Joliet, and Springfield. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
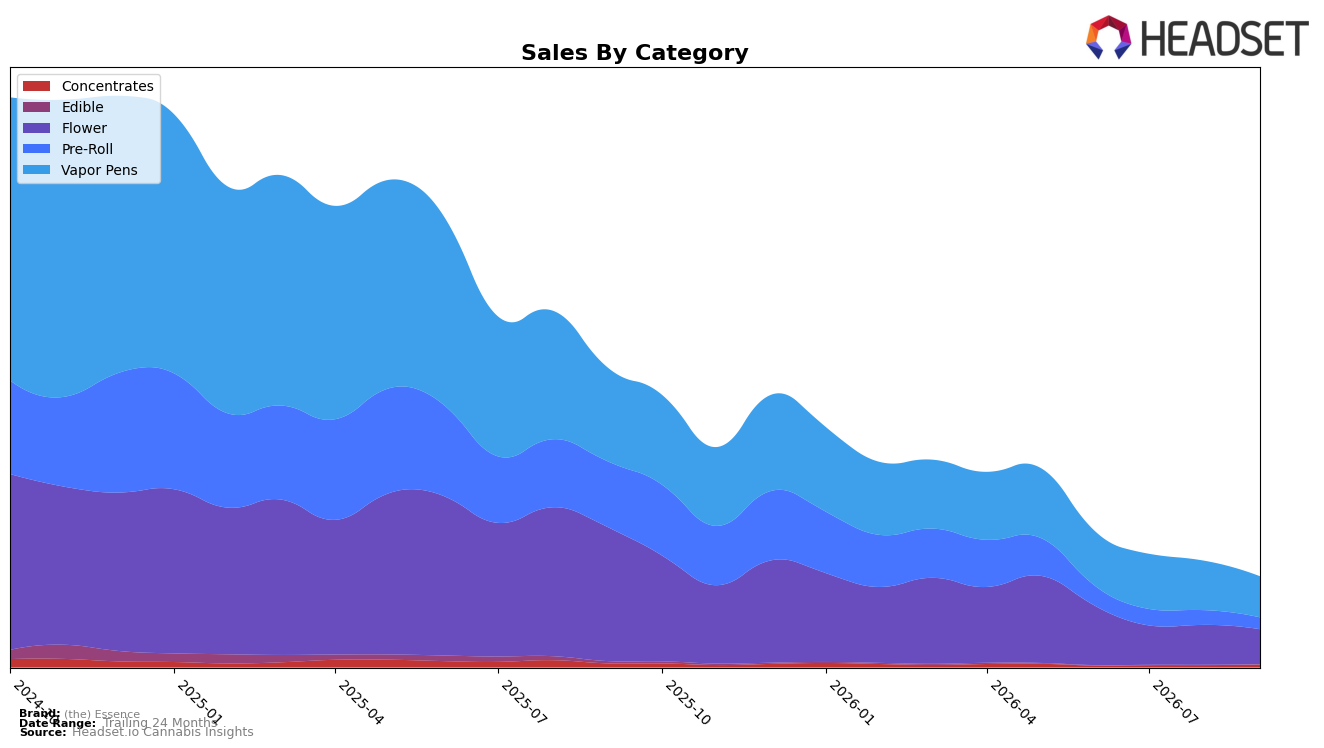
(the) Essence concentrated 45.25% of September 2026 sales in Vapor Pens with a year-over-year decline of 56.17% and a month-over-month decline of 16.78%, while Flower held 38.48% share with steeper year-over-year erosion of 73.94% and a 12.34% month-over-month dip; Pre-Roll at 12.91% share fell 82.18% year-over-year and 19.84% month-over-month. In contrast, Concentrates represented 3.11% share with a 29.86% year-over-year decline but a 21.37% month-over-month increase, and Edible at 0.25% share dropped 89.47% year-over-year despite a 77.79% month-over-month lift; together these pockets of sequential growth offset only a fraction of the brand’s overall 69.71% year-over-year decline and 4.76% price compression, implying the category mix is still anchored to segments with the heaviest contraction.
Positioning-wise, the 20th rank in Vapor Pens in Illinois combined with a 16.78% month-over-month contraction in that lead category and a 12.34% month-over-month decline in Flower suggests (the) Essence is overexposed to down-trending inhalable formats relative to its portfolio weightings. The 21.37% month-over-month gain in Concentrates and 77.79% month-over-month gain in Edible indicate testable footholds for diversification, yet their combined 3.36% share keeps them too small to materially shift trajectory; the implication is that near-term positioning requires either recapturing share within Vapor Pens where the brand currently ranks 20th, or reallocating mix toward faster-recovering niches where sequential momentum is already visible.
Competitive Landscape
(the) Essence sits at rank #20 in Illinois Vapor Pens in September 2026, down 12 spots year over year from #8 and 5 spots lower than June 2026’s #15, despite a historical peak at #4 in February 2025; meanwhile, &Shine moved up from #2 to #1 and Fernway surged from #13 to #3 alongside a 308.8% YoY sales gain, while Savvy slid from #3 to #5 with a -32.7% YoY decline. Compared with Select drifting from #1 to #2 and RYTHM edging up from #5 to #4, (the) Essence’s move from #8 to #20 signals a shift from prior peak positioning toward the lower tier of the top 20, implying that recapturing share now requires countering competitors that have either consolidated leadership or accelerated faster up the rankings.

Notable Products
Project 900 Pre-Roll (1g) posted the single largest move with a 59.0% month-over-month increase and climbed to rank 2, while Hyphen - Strawberry Cough Distillate Cartridge (1g) fell 15.3% MoM and slid to rank 8. Hyphen - Bombsicle Distillate Cartridge (1g) rose 28.1% MoM to hold rank 1, and Tres Leches Pre-Roll (1g) declined 11.8% MoM at rank 5. With four of the top ten as Pre-Rolls and three as Vapor Pens, the mix indicates (the) Essence is tilting toward value-forward inhalables where volatility in Pre-Rolls can quickly translate to share shifts across adjacent Vapor Pen SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

