

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Treehaus Cannabis is stocked at 88 licensed dispensaries across Washington and Ohio, 73 of them in Washington, with the deepest coverage in Seattle, Everett, Spokane, Tacoma, and Bellingham. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
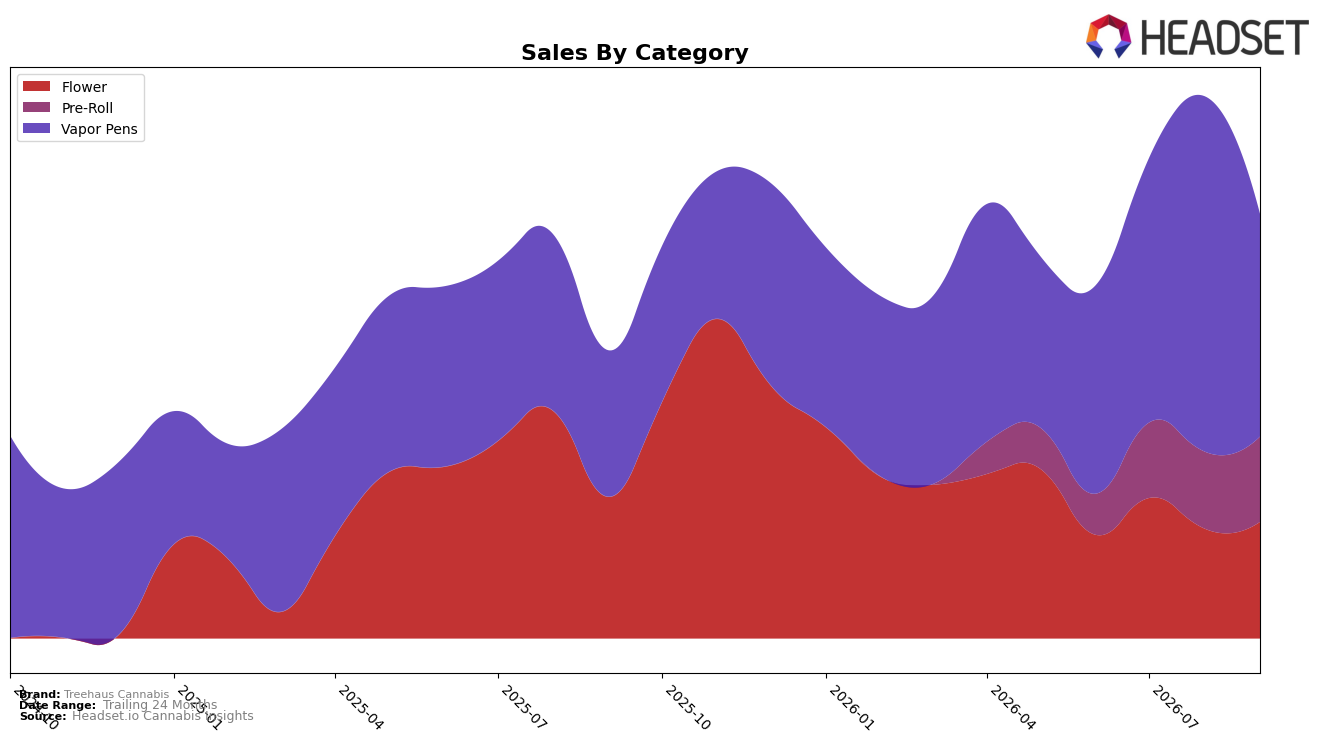
Treehaus Cannabis concentrated 52.50% of September 2026 sales in Vapor Pens, where year-over-year growth was 52.34% despite a month-over-month decline of 37.32%, while Flower held 27.45% share with a 17.65% YoY contraction and a 6.14% MoM lift. Pre-Roll expanded to 20.05% share with a 10.74% MoM gain and no year-over-year baseline, and the brand sat at rank 31 in Vapor Pens in Washington even as average price fell 43.07% YoY to $20.68. The pattern implies a deliberate pivot toward volume-led Vapor Pen scale tempered by recent monthly pullback, with Flower stability and Pre-Roll entry cushioning mix volatility.
The September 2026 mix signals a positioning anchored in Vapor Pens scale (52.50% share, rank 31 in Washington) complemented by counter-cyclical hedges: Flower’s 6.14% MoM uptick offsets pen softness, and Pre-Roll’s 10.74% MoM rise builds a value on-ramp under a 43.07% YoY price reset. With Vapor Pens up 52.34% YoY yet down 37.32% MoM, and Flower down 17.65% YoY while Pre-Roll expands to 20.05% share, Treehaus Cannabis is tilting toward price-accessible inhalables to capture share near-term while keeping a foothold in higher-ticket Flower to preserve premium cues.
Competitive Landscape
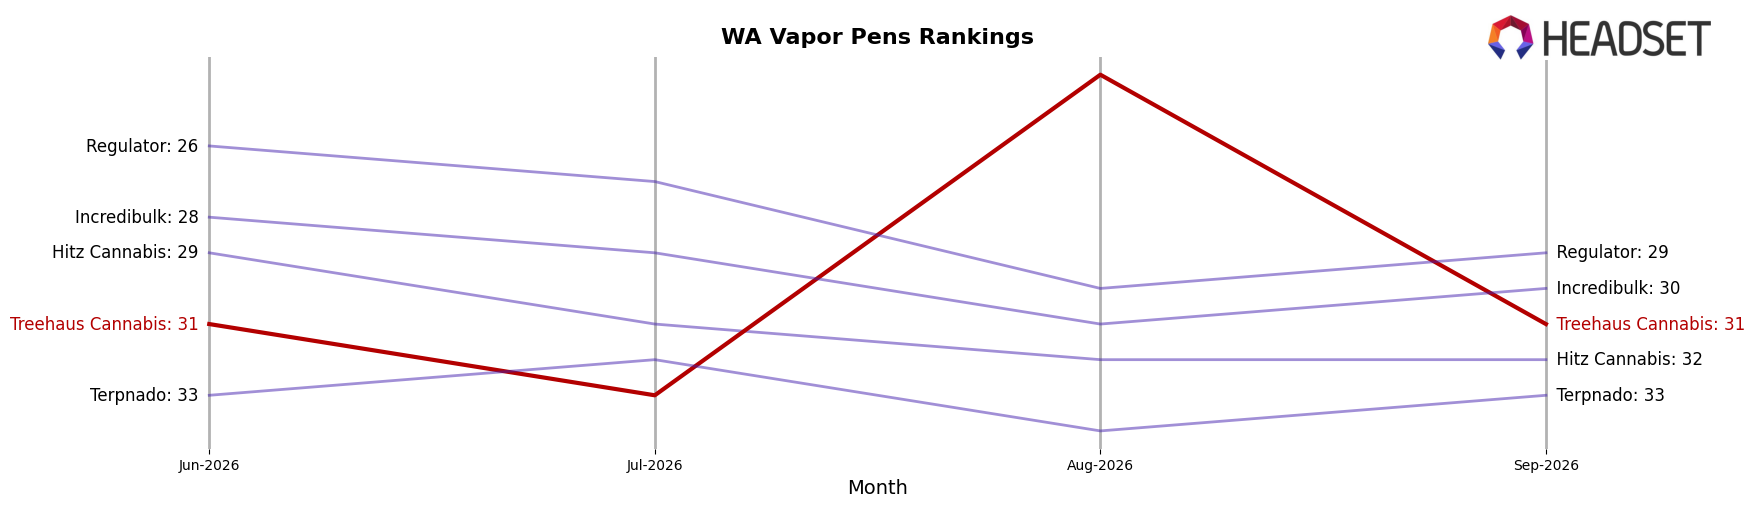
Treehaus Cannabis sits at rank #31 in Washington Vapor Pens for September 2026, improving 8 positions from #39 year over year, while holding flat versus June 2026 at #31 and coming off a peak of #24 in August 2026. In contrast, Crystal Clear climbed from #3 to #1 with 26.4% year-over-year sales growth, whereas Mfused slipped from #1 to #2 with a 30.9% decline, indicating that Treehaus Cannabis’s modest rank gain amid top-tier volatility suggests incremental distribution or SKU mix gains rather than broad share capture, implying a trajectory of gradual improvement that will require a further 7-rank climb to revisit its August 2026 peak.
Notable Products
El Diablo Pre-Roll (1g) posted the steepest decline in September 2026 at -61.0% while dropping into rank 9, as Ube Latte Distillate Cartridge (1g) fell -37.7% at rank 10, indicating demand is concentrating away from lower-ranked SKUs. In contrast, Sunset Wedding Pre-Roll (1g) surged +94.9% to rank 2 and Blueberry Lemonade Pre-Roll (1g) rose +18.6% to rank 3, while four of the top ten are Pre-Roll SKUs clustered in ranks 1–3 and 7–9, implying format-led momentum despite volatility at the tail. Vapor Pens were mixed, with Cascade Kush Hash Rosin Disposable (1g) up +21.0% at rank 4 versus Twin Peaks Hash Rosin Disposable (1g) down -1.4% at rank 5, and Cosmic Crispy Treat Rosin Disposable (1g) debuting at rank 6 with $18,932, suggesting solventless-led Vapor Pens can lift share even as distillate weakens. The pattern implies Treehaus Cannabis is consolidating around top-tier Pre-Roll winners and solventless Vapor Pens, tilting assortment toward fewer, higher-velocity SKUs and away from lagging flavors.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

