
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Common Citizen is stocked at 281 licensed dispensaries across Michigan, Ohio, and Pennsylvania, 248 of them in Michigan, with the deepest coverage in Detroit, Monroe, New Buffalo, Grand Rapids, and Kalamazoo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
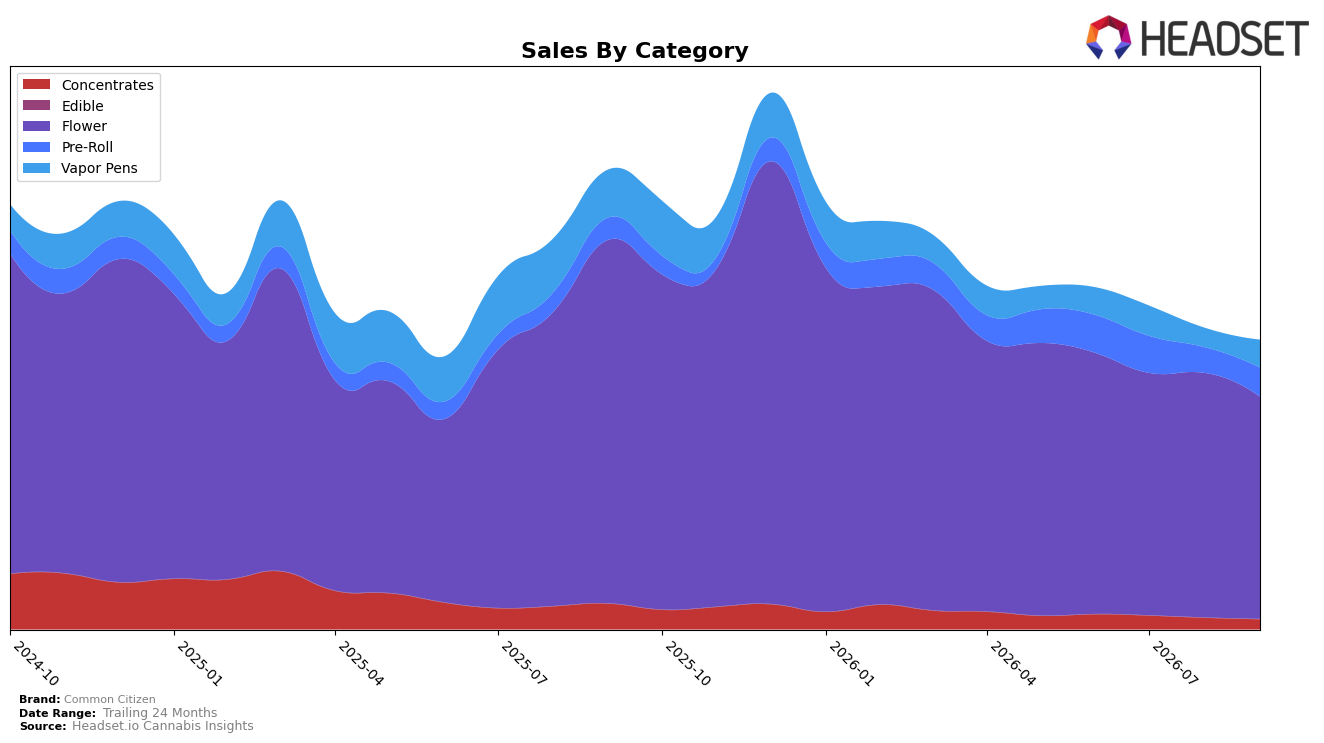
In September 2026, Common Citizen concentrated 77.06% of sales in Flower, where year-over-year sales fell 38.91% and month-over-month declined 9.15%, while the average price across the brand dropped 33.27% year over year. Pre-Roll expanded to a 9.98% share with 31.02% YoY growth and 13.49% MoM growth, and Vapor Pens held 9.55% share despite a 42.31% YoY decline but a 44.31% MoM rebound; Concentrates slipped to 3.41% share with a 61.36% YoY decline and a 12.91% MoM drop. With Common Citizen ranked 11 in Flower in Michigan, the mix now leans on a large but contracting flagship category while momentum shifts toward Pre-Roll and a short-term recovery in Vapor Pens, implying a transition away from overexposure to Flower.
The simultaneous 38.91% YoY contraction in Flower against a 31.02% YoY rise in Pre-Roll suggests substitution toward lower-price, convenience formats, reinforced by the brand’s 33.27% YoY average price reduction. The 44.31% MoM bounce in Vapor Pens alongside a 9.15% MoM decline in Flower indicates recapture of inhalable share within non-Flower formats, while the 12.91% MoM drop in Concentrates points to a pruning of niche offerings rather than a portfolio push. Net effect: Common Citizen’s competitive posture in Michigan is tilting toward value-led, quick-turn items (Pre-Roll, select Vapor Pens) to stabilize share while Flower scale sustains rank 11 but no longer anchors growth.
Competitive Landscape
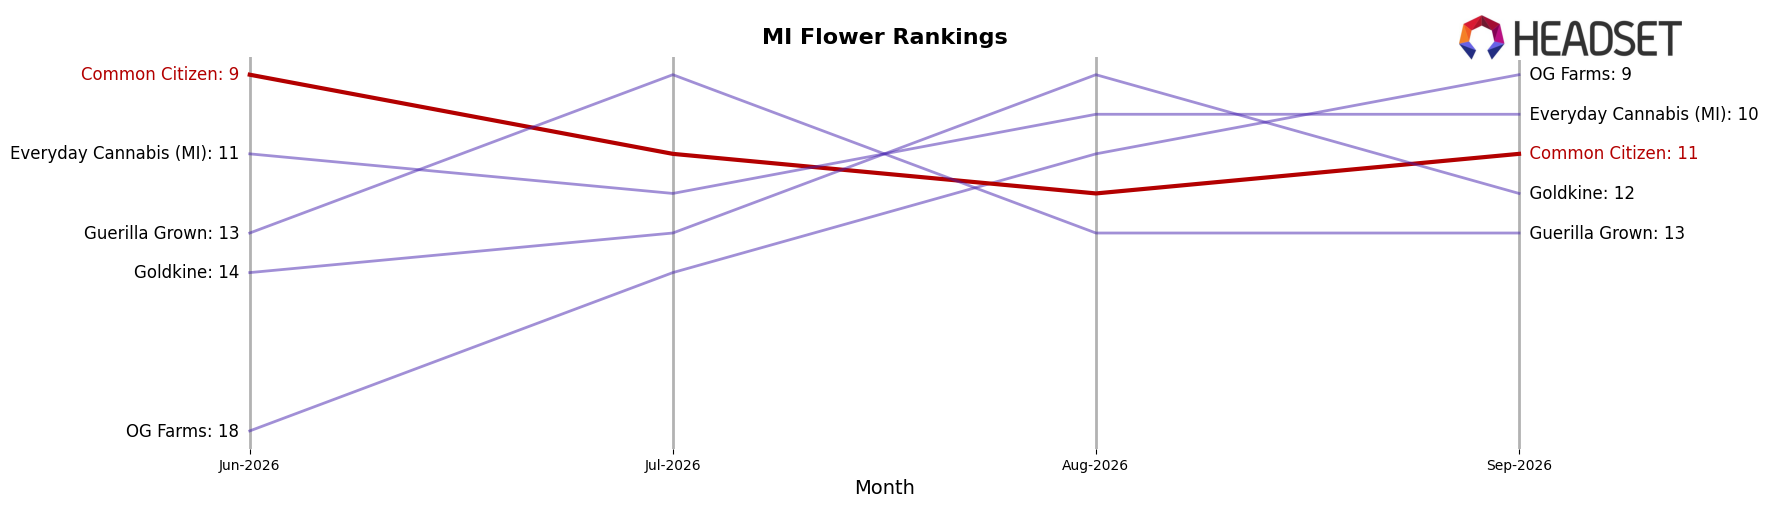
Common Citizen is currently ranked #11 in Michigan Flower, down 3 positions year over year from #8 and down 2 positions from #9 in June 2026, while its historical peak was #4 in December 2024. In contrast, Play Cannabis advanced from #7 to #2 alongside a 33.3% year-over-year sales increase, and Pro Gro moved from #6 to #3 with 25.5% year-over-year growth, whereas category leader High Minded held #1 but posted a -3.3% year-over-year sales change. This divergence—Common Citizen slipping from a prior #4 peak while adjacent rivals climb multiple ranks—implies a share reallocation toward faster-movers and a need for SKU or pricing repositioning to arrest downward rank momentum.
Notable Products
Z Lato (3.5g) posted the steepest movement in September 2026 with a -44.1% month-over-month decline while sliding to rank 6, and Dracoz (3.5g) also fell -25.2% while sitting at rank 9. Tropical Runtz (1g) held rank 1 and Banana Orange Pineapple (3.5g) held rank 2, and eight of the top ten SKUs are Flower, concentrating the mix despite a -44.1% hit within that same category. The dominance of Flower at high ranks alongside double-digit declines within mid-pack Flower SKUs implies assortment pruning is needed to protect premium placements and stabilize mid-tier volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

