


Where to Buy
Viola is stocked at 54 licensed dispensaries across Colorado, Arizona, and Maryland, 52 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Aurora, Brighton, and Durango. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
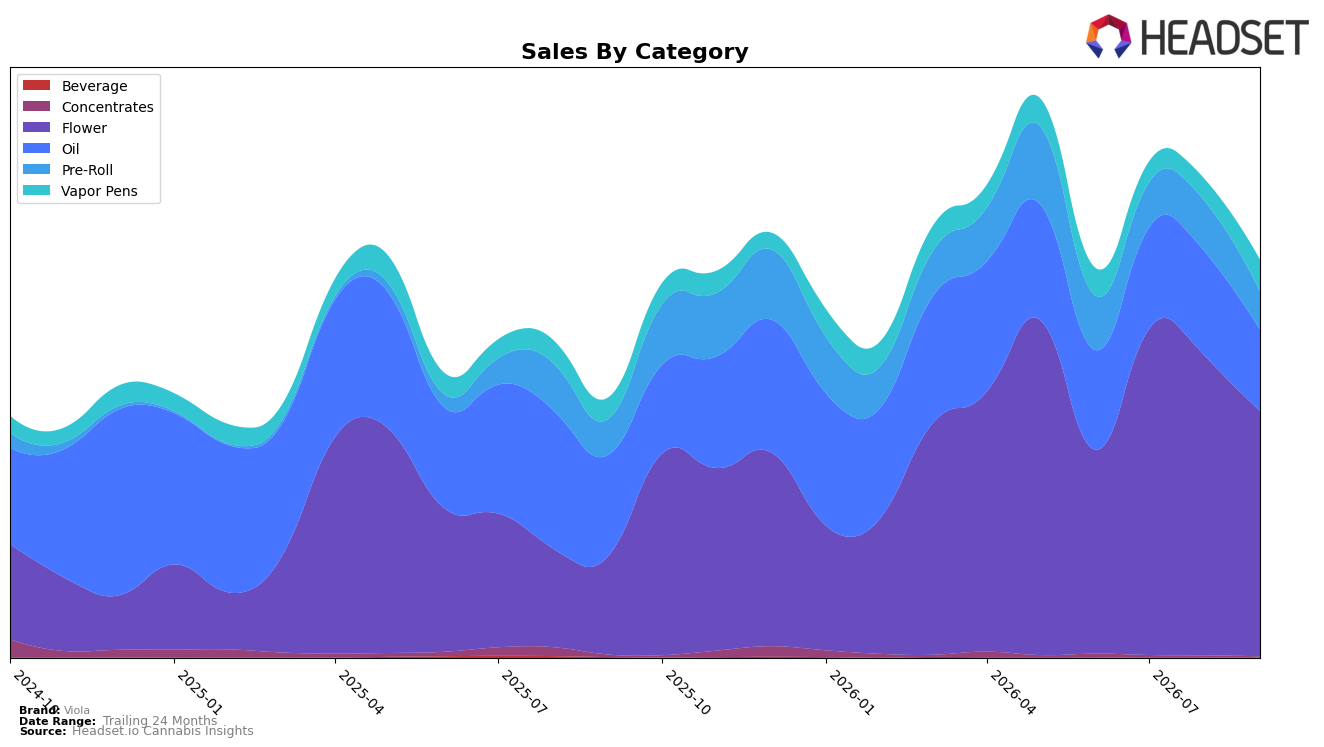
Flower now accounts for 61.75% share with 149.44% year-over-year growth but a -18.23% month-over-month drop, while Oil holds 20.45% share with -19.54% year-over-year and -21.90% month-over-month declines. Pre-Roll sits at 9.60% share with 6.76% year-over-year growth but a -23.97% month-over-month slide, and Vapor Pens at 7.91% share surged 47.79% year-over-year and 44.81% month-over-month. Against a brand-level 53.28% year-over-year sales increase and an -18.75% average price change, the mix tilts toward lower-priced Flower (average price $7.02) even as higher-ticket Oil (average price $30.37) contracts; this pattern implies September 2026 volume gains are concentrated in value segments while premium extracts retrench.
With Flower’s share expanding to 61.75% alongside a -18.23% month-over-month pullback and Vapor Pens climbing 44.81% month-over-month to 7.91% share, Viola is shifting toward inhalable value and convenience, trading average price down -18.75% year-over-year to reinforce volume. Oil’s share at 20.45% amid -21.90% month-over-month and -19.54% year-over-year declines, plus Concentrates’ -45.19% month-over-month and -50.59% year-over-year drops to 0.27% share, compress the premium extract footprint; paired with a Flower rank of 34 in Colorado, the mix implies the brand’s competitive posture depends on scaling mainstream Flower while using Vapor Pens as a growth wedge rather than leaning on declining extract categories.
Competitive Landscape
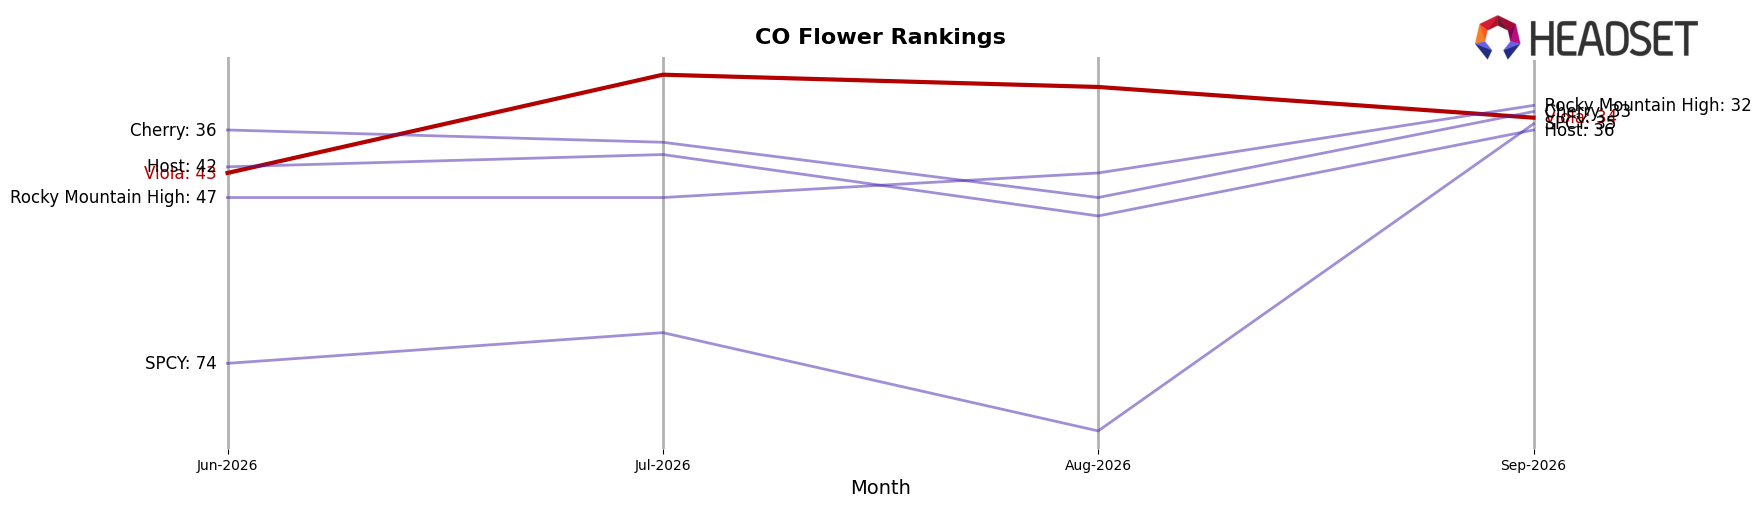
Viola sits at rank 34 in CO Flower in September 2026, up 32 positions year over year from rank 66, and 9 spots higher than June 2026’s rank 43, while still trailing its peak rank 27 from July 2026; in the same period, Green Label Cannabis held at #1 year over year with +38.0% sales growth and Seed & Strain Cannabis Co. slid from #2 to #4 with -33.5% sales, indicating Viola’s mid-pack ascent has come during leadership stability at the top and volatility just ahead of it. This pattern implies Viola’s rank trajectory is moving from fringe to contender, with headroom to consolidate gains against sliding incumbents if it converts July 2026’s peak ranking into sustained placement.
Notable Products
Crown Jewel Smalls (Bulk) posted the sharpest movement in September 2026 with an -84.7% MoM drop while falling to rank 10, whereas Bubblegum Gusher Smalls (Bulk) climbed to rank 1 on a +50.0% MoM surge, indicating volatility within the Flower lineup. The Drop THC Extract Oil (20ml) slid -21.9% MoM at rank 7 against a higher-ranked Flower surge, and Flower SKUs occupied 8 of the top 10 positions, pointing to a category concentration that is widening even as Oil weakens. With a $98,470 pull from The Drop THC Extract Oil (20ml) still anchoring non-Flower spend and a countervailing rise at the top of Flower, the mix implies Viola is tilting toward bulk Flower momentum while relying on fewer Oil bets to carry revenue stability.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

