

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
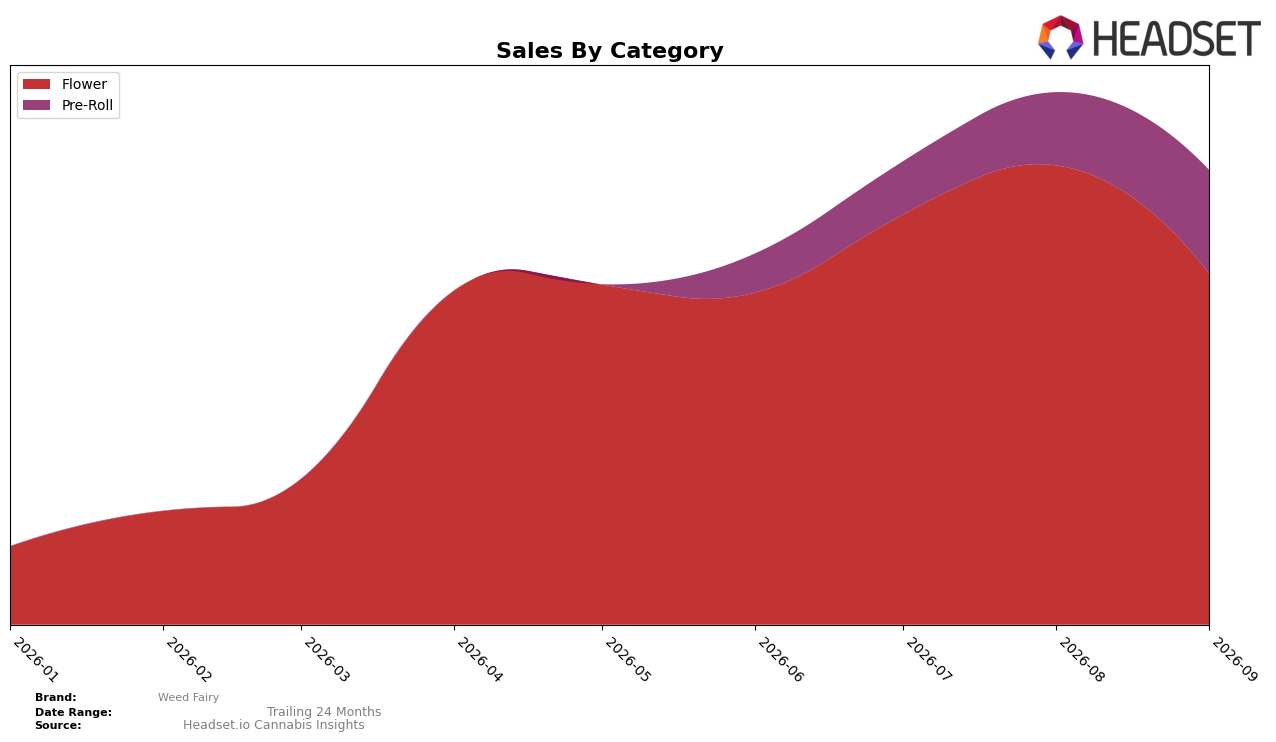
Weed Fairy concentrated 77.29% of September 2026 sales in Flower with a month-over-month decline of 23.57%, while Pre-Roll expanded to 22.71% share on a 41.42% MoM increase; the average Flower price sat at $48.55 versus a $9.97 Pre-Roll average, indicating a widening price-tier split. Within Flower, the brand held rank 18 in Saskatchewan, and the mix shift toward Pre-Roll suggests a relative pivot away from higher-ticket units as Flower volume contracted and value-oriented formats accelerated, implying margin pressure unless mix management offsets the -23.57% swing with the 41.42% Pre-Roll uplift.
The September 2026 step-down in Flower share concurrent with a Pre-Roll surge indicates that Weed Fairy’s positioning is tilting toward accessibility and trial rather than premium depth, given the large gap between $48.55 and $9.97 average prices and the 22.71% Pre-Roll share now shouldering more of the basket. Holding rank 18 in Saskatchewan Flower while Flower fell 23.57% MoM points to a need for differentiated SKUs or pricing architecture in Flower, while the 41.42% MoM gain in Pre-Roll implies headroom to convert trial into repeat, pushing a barbell strategy that leverages Pre-Roll acquisition to defend Flower rank and stabilize category contribution.
Competitive Landscape
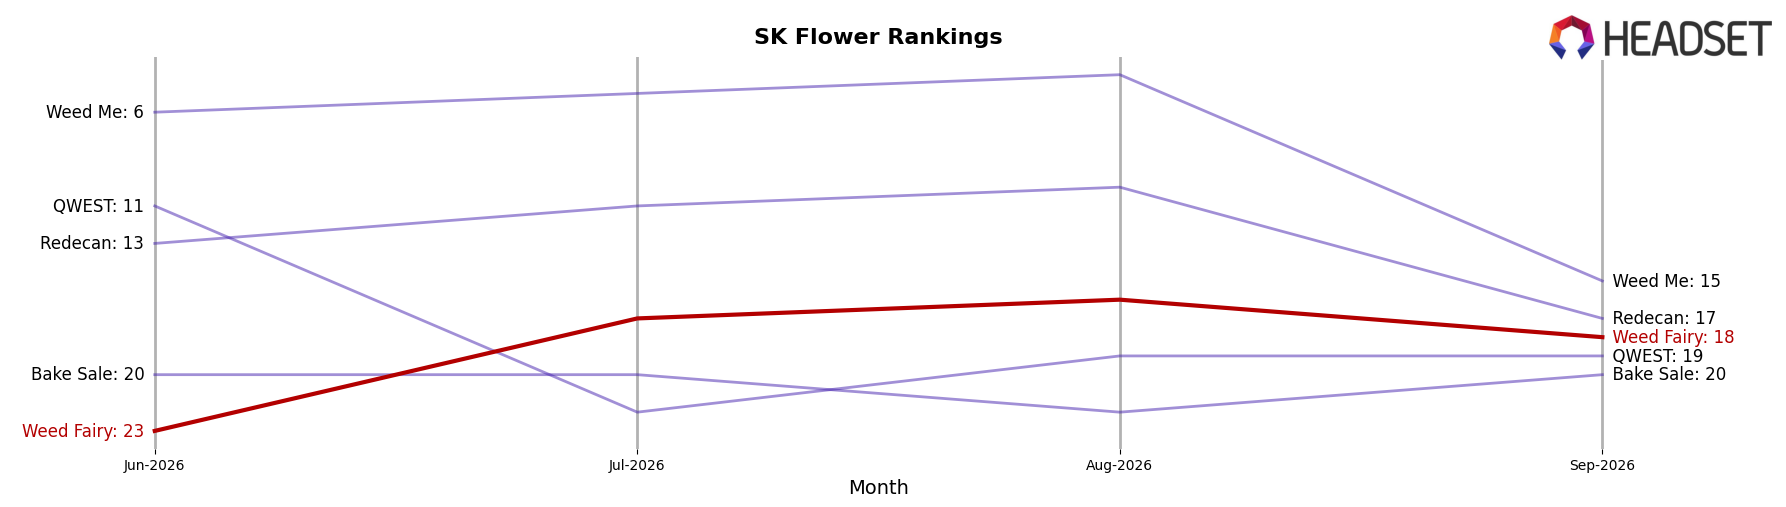
Weed Fairy is ranked #18 in SK Flower in September 2026, improving 5 positions from #23 in June 2026 and sitting 2 spots below its peak of #16 in August 2026; by contrast, Spinach advanced to #2 with a 60.16% year-over-year sales increase while Zippy (Canada) surged to #5 with a 32-rank climb and 364.66% year-over-year sales growth. Compared with category leadership where Back Forty / Back 40 Cannabis holds #1 and Good Supply is #4 after a 3-rank year-over-year gain, Weed Fairy’s 2-rank slide from its August 2026 peak and 5-rank quarter-over-quarter rise indicate mid-pack momentum without breakout acceleration, implying the brand is stabilizing around the high teens unless it captures share from faster risers.
Notable Products
Kush Mints Pre-Roll 3-Pack (1.5g) posted the sharpest move with a 232.8% month-over-month surge to rank 3, while White Cookies Pre-Roll 3-Pack (1.5g) gained 61.9% to rank 1, and White Cookies Pre-Roll (1g) fell 36.3% to rank 2. Three of the top three SKUs are Pre-Rolls, concentrating the podium in a single category and implying multipack formats are displacing single sticks at the point of choice.
In Flower, Black Betty (3.5g) climbed 29.5% to rank 4 as Kush Mints (3.5g) dropped 51.3% to rank 7, while White Cookies (7g) inched up 3.2% to rank 6 and OG Mango (3.5g) edged 3.6% to rank 8. With five of the top ten belonging to Flower but none cracking the top two, the mix indicates Weed Fairy’s near-term revenue leadership is shifting toward value-forward Pre-Roll multipacks even as Flower sustains breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

