

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
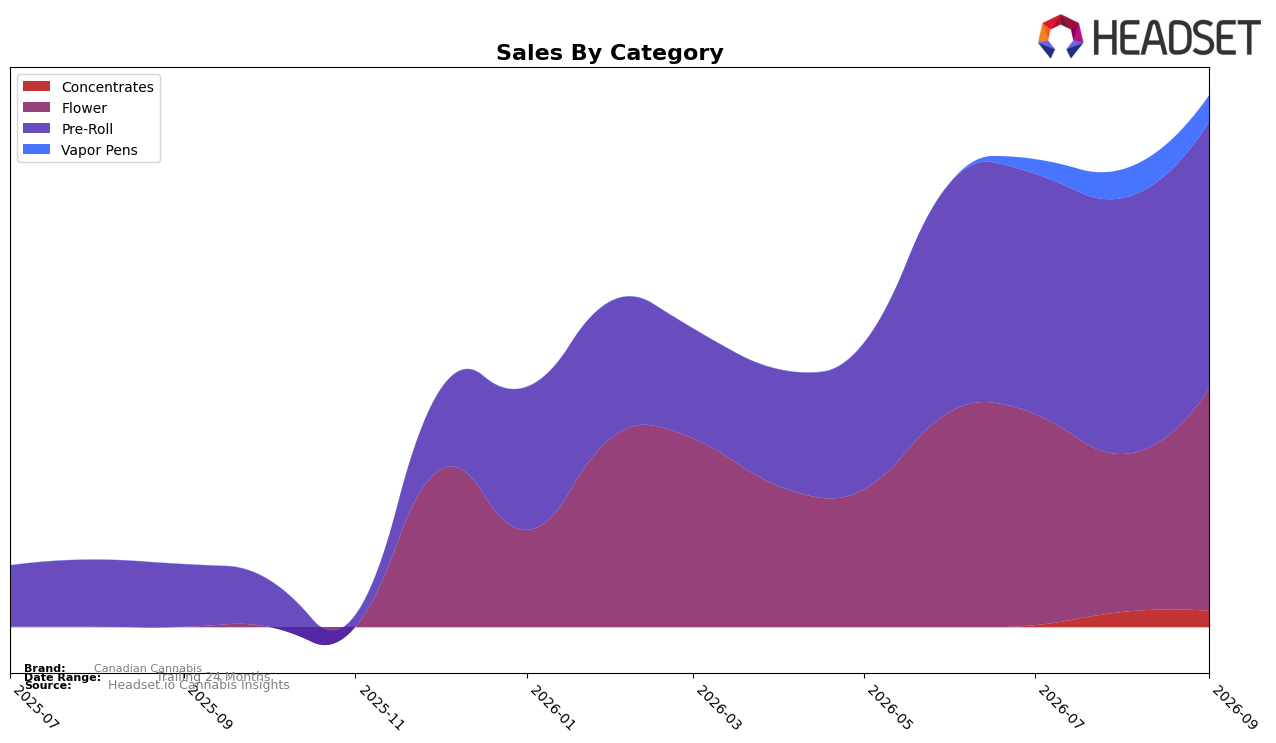
Canadian Cannabis concentrated over half of September 2026 sales in Pre-Roll at 50.20% share with 4.34% month-over-month growth, while Flower held 41.76% share with a 40.68% month-over-month surge; Pre-Roll also posted 327.71% year-over-year growth and the brand’s overall sales were up 751.95% year over year. Vapor Pens slipped to 4.99% share with a -6.96% month-over-month decline, whereas Concentrates at 3.05% share rose 7.68% month over month; average price climbed 117.38% year over year to $20.28 alongside Pre-Roll’s average price at 13.16. In Alberta Pre-Roll, the brand stood at rank 21, which—paired with the Pre-Roll share breaching 50% and Flower’s rapid month-over-month expansion—implies a pivot toward a two-category core that is building scale faster than the rest of the mix.
The pairing of a 50.20% Pre-Roll share and a 41.76% Flower share, alongside a 117.38% jump in average price and a 4.34% versus 40.68% month-over-month split, suggests a trade-up dynamic where Flower is lifting basket value while Pre-Roll supplies volume. With Vapor Pens shrinking -6.96% month over month to 4.99% share and Concentrates limited to 3.05% despite a 7.68% month-over-month lift, the portfolio tilt indicates Canadian Cannabis is positioning around combustion formats while de-emphasizing inhalable devices; holding rank 21 in Alberta Pre-Roll and posting 327.71% year-over-year growth in that category implies the brand can gain distribution-led share by reinforcing these two anchors rather than reallocating toward smaller, slower channels.
Competitive Landscape
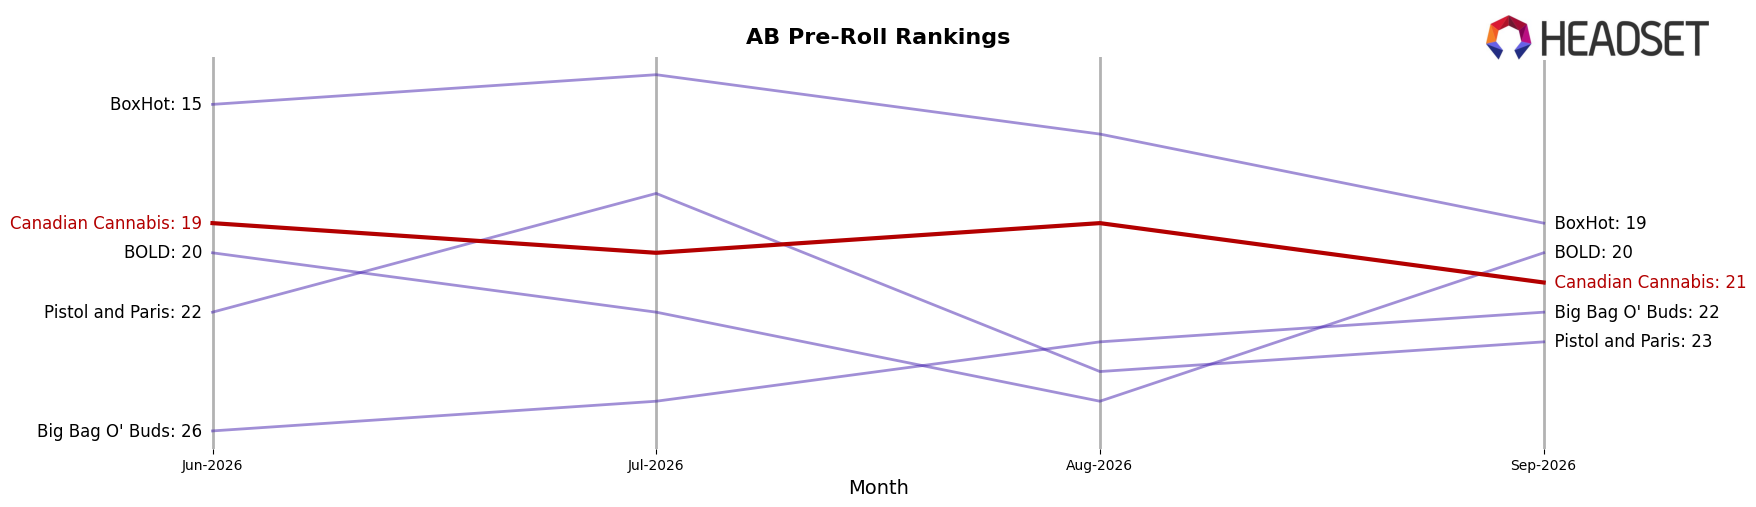
Canadian Cannabis sits at rank 21 in AB Pre-Roll for September 2026 after climbing 34 positions year over year from rank 55, while slipping 2 spots from its three-month mark at rank 19 and matching its peak rank of 19 in August 2026; in contrast, Back Forty / Back 40 Cannabis advanced from rank 3 to rank 1 with 26.2% YoY sales growth and General Admission fell from rank 1 to rank 2 with a 27.9% YoY sales decline, indicating that Canadian Cannabis’s mid-pack rise alongside churn at the top suggests a window to consolidate share if it can convert its August peak at rank 19 into sustained gains.
Notable Products
Sativa Eh! Pre-Roll 2-Pack (2g) posted the steepest decline at -19.1% MoM while holding rank 2, and Indica Eh! Pre-Roll 2-Pack (2g) slipped -10.7% yet stayed at rank 1, pointing to volume durability at the top despite contraction. Organic Sugar Haze Pre-Roll 2-Pack (2g) rose +18.2% MoM at rank 5 as Organic Sugar Haze Pre-Roll (0.5g) fell -25.3% at rank 7, indicating pack-size trade-up within the same strain family. Eight of the top ten SKUs are Pre-Roll products, and Mango Hashplant Pre-Roll (0.5g) declined -20.0% at rank 10 while Apex Kush Pre-Roll (0.5g) eased -5.9% at rank 3, concentrating share in higher-ranked formats rather than new entries. The pattern implies Canadian Cannabis is consolidating around larger or multi-pack Pre-Rolls while smaller single 0.5g formats cede momentum, suggesting a pricing and value-pack orientation for late 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

