
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
White Mousse is stocked at 95 licensed dispensaries across Colorado and Oklahoma, 67 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Aurora, Commerce City, and Longmont. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
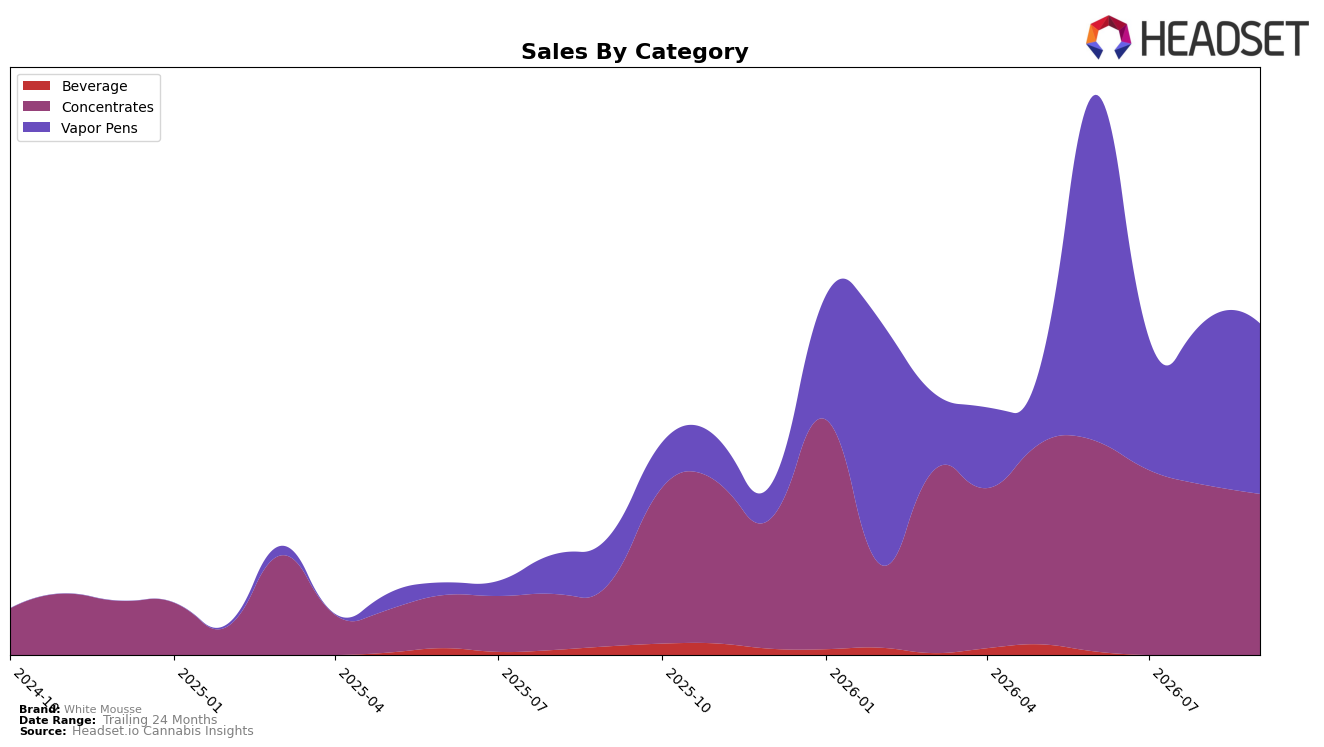
In September 2026, White Mousse split nearly evenly between Vapor Pens at 51.4% share and Concentrates at 48.6% share, but the momentum tilted toward Vapor Pens with 262.3% year-over-year growth versus 161.6% in Concentrates and a 4.1% month-over-month lift versus a 5.3% month-over-month decline. Average prices diverged at $32.19 in Vapor Pens versus $13.33 in Concentrates, aligning with the overall 21.6% year-over-year price increase and suggesting mix-led ticket expansion; this mix helps explain brand sales growth of 182.4% year over year despite a softer Concentrates month. The thesis is that White Mousse is migrating toward higher-priced Vapor Pens while Concentrates funds volume, with the category split cushioning volatility from the Concentrates month-over-month dip.
That shift implies a positioning pivot toward premiumized inhalables, as Vapor Pens gain share and price while the brand sits at rank 51 in Vapor Pens in Colorado, a rank that leaves room to trade up without sacrificing breadth. With Vapor Pens up 262.3% year over year and 4.1% month over month while Concentrates lags at -5.3% month over month despite 161.6% year-over-year expansion, the near-term play is to lean into the higher-price ladder where average price is $32.19, using Concentrates at $13.33 as an entry point to defend volume. The thesis is that the brand can climb from rank 51 in Vapor Pens by converting Concentrates buyers into higher-value Vapor Pen customers, improving revenue yield while maintaining a two-category hedge.
Competitive Landscape
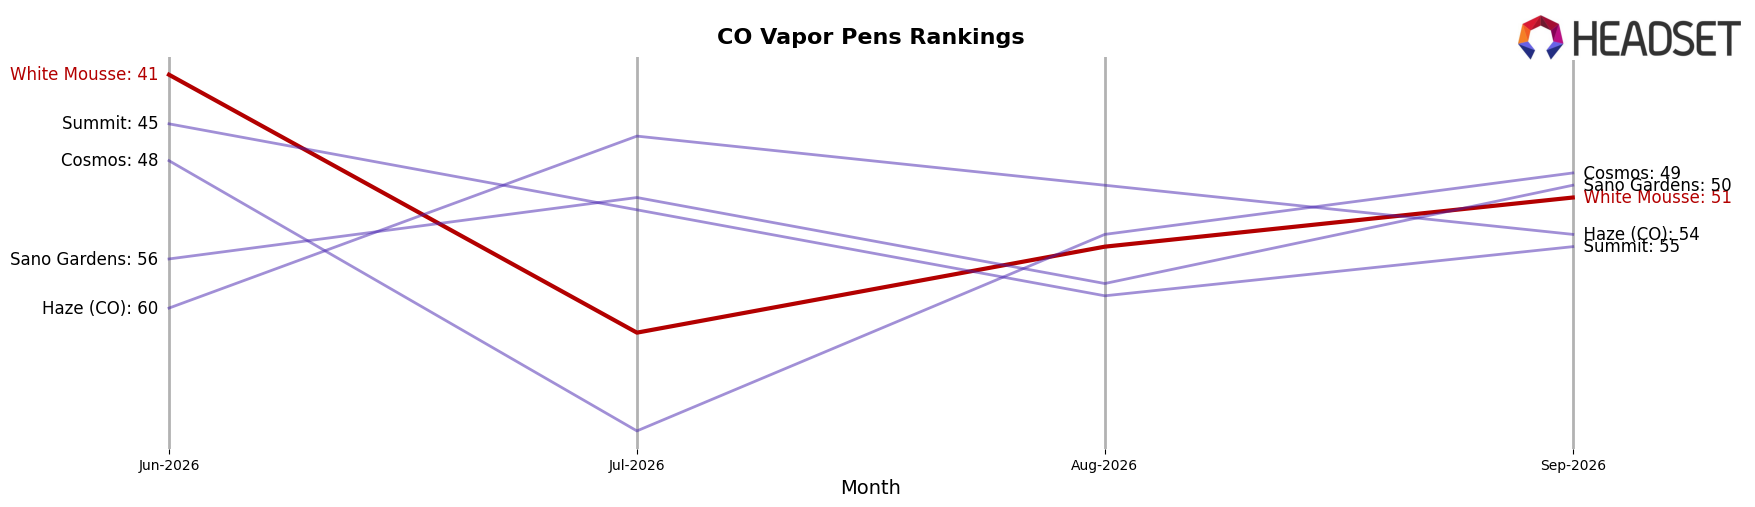
White Mousse sits at rank #51 in Colorado Vapor Pens in September 2026, a 25-place YoY climb from #76 and a 10-place slide from its June 2026 peak at #41, indicating momentum YoY but recent slippage within the quarter; meanwhile, Spherex held at #1 YoY with a 1.9% sales increase and PAX rose from #3 to #2 on 34.7% YoY growth, positioning category leaders to widen distance as White Mousse moves down 10 ranks from June 2026 to September 2026 and sits 50 places behind #1. This pattern implies White Mousse’s YoY recovery is intact but its quarter-over-quarter rank reversal signals share pressure intensifying as top competitors consolidate at #1–#2.
Notable Products
Sunrise Live Resin Cartridge (1g) delivered the standout move in September 2026 with a 50.1% month-over-month gain that pushed it to rank 2, while Garlic Fields Live Resin Cartridge (1g) held rank 1 without a reported month-over-month change, indicating the Vapor Pens tier is consolidating around two leaders. Air Fighter Sugar Wax (1g) rose 19.4% month over month at rank 5 as Garlic Breath Sugar Wax (1g) inched up 7.7% at rank 8, and four of the top ten are Concentrates SKUs, pointing to a balanced mix where dab formats still carry breadth even as pens capture the spikes. With Jam Session Live Resin Cartridge (1g) also in the top six and Vapor Pens contributing the only 50%+ mover alongside a $7,599 month’s take for Garlic Fields Live Resin Cartridge (1g), the product mix implies White Mousse is tilting assortment and demand toward live resin pens while maintaining depth in sugar and cured wax to stabilize ranks.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

